What Is a Sinking Fund and How Does It Work?
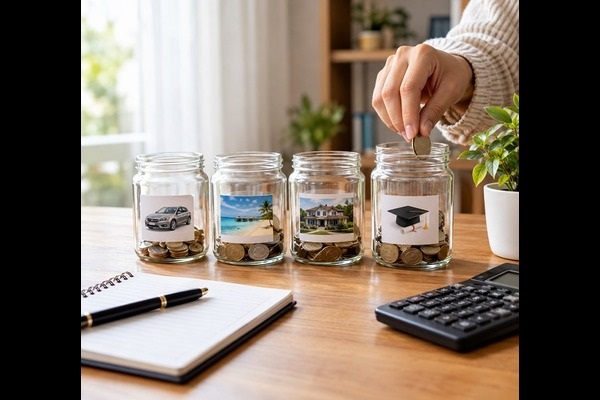
A sinking fund is a simple money-management method used to save gradually for a known future expense. Instead of trying to find a large amount when a bill arrives, you set aside smaller amounts regularly so the money is ready when you need it.
It is different from an emergency fund because a sinking fund is generally meant for an expense that you already expect.
How Does a Sinking Fund Work?
The process is straightforward. First, identify an upcoming expense and estimate how much money you will need. Then determine when the payment will be required and divide the target amount into regular savings contributions.
For example, suppose you expect to spend Rs12,000 on annual insurance after 12 months. Setting aside Rs1,000 per month would give you Rs12,000 by the time the payment is due.
The exact contribution can be adjusted depending on how frequently you receive income.
What Expenses Can a Sinking Fund Cover?
Sinking funds can be useful for expenses that are predictable but do not occur every month. Examples include annual insurance premiums, vehicle servicing, festival shopping, school fees, travel, home repairs, electronic upgrades, or yearly subscriptions.
The idea is to turn an occasional large expense into a series of smaller planned savings contributions.
Sinking Fund vs Emergency Fund
The two serve different purposes.
An **emergency fund** is designed for unexpected financial situations such as an urgent repair, sudden loss of income, or other unforeseen expenses.
A **sinking fund** is created for expenses that are known or reasonably predictable.
Keeping the two separate can make it easier to understand how much money is genuinely available for emergencies.
Why Sinking Funds Can Make Budgeting Easier
Large periodic expenses can disrupt a monthly budget when they are treated as surprises. A sinking fund spreads the cost across several months.
This can make cash flow more predictable and reduce the need to use credit cards or loans for planned purchases.
For example, instead of suddenly paying Rs6,000 for vehicle maintenance, you could save Rs500 per month toward that expected expense.
### How Many Sinking Funds Should You Have?
There is no fixed number. Some people prefer one general account for planned expenses, while others create separate categories for things such as travel, car maintenance, insurance, and gifts.
Too many categories can make money management unnecessarily complicated. The goal is to create a system that is easy to maintain.
Where Should the Money Be Kept?
For short-term goals, the priority is generally accessibility and capital preservation rather than chasing high returns. The money should be kept somewhere appropriate for the time frame and risk involved.
A separate savings account or clearly tracked savings category can make it easier to avoid accidentally spending the money on something else.
What If the Expense Is More Expensive Than Expected?
It is useful to review sinking funds periodically. If the expected cost increases, you can raise the monthly contribution or extend the saving period when possible.
For example, if a planned Rs20,000 expense is now expected to cost Rs24,000, the target should be updated rather than waiting until the payment date.
### What Happens After You Reach the Goal?
Once the target amount has been reached, you can pause contributions until the expense occurs. After making the payment, the fund can be restarted for the next cycle.
This makes sinking funds particularly useful for recurring annual expenses.
A Simple Way to Start
Choose one upcoming expense rather than trying to create several funds immediately. Estimate the amount, calculate how much time remains, and divide the target by the number of saving periods.
For a Rs15,000 expense due in 10 months:
**Rs15,000 ÷ 10 = Rs1,500 per month**
Automating that amount after receiving your income can make the habit easier to maintain.
The Bottom Line
A sinking fund is essentially a planned savings bucket for a future expense. By putting aside smaller amounts regularly, you can prepare for predictable costs without putting sudden pressure on your monthly budget.
The method works best when the target, deadline, and contribution amount are clearly defined and reviewed whenever the expected expense changes.