How Assets and Liabilities Shape Your Financial Position
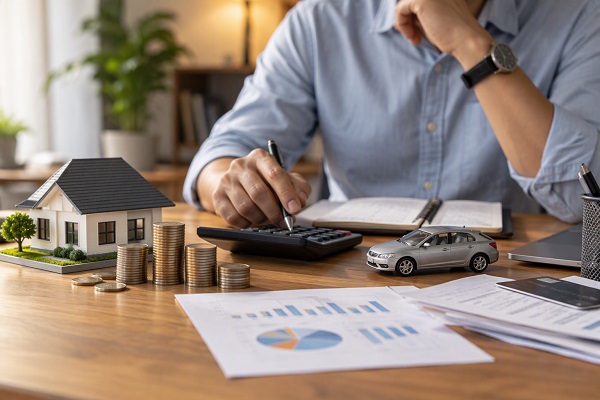
Your financial position is not determined only by how much money you earn every month. What you own and what you owe are also important. This is where assets and liabilities come into the picture. Understanding the difference between the two can give you a clearer view of your overall financial health.
Assets are things that have financial value and belong to you. They can include cash, bank balances, investments, property, gold and other valuable possessions. Some assets may generate income, while others may simply hold value over time.
Liabilities, on the other hand, represent money that you owe to someone else. Home loans, vehicle loans, personal loans, credit card balances and other outstanding debts are common examples. A liability can reduce the amount of wealth you actually control.
The relationship between your assets and liabilities helps determine your net worth. In simple terms, net worth is the value of what you own after subtracting what you owe. Someone may own a valuable property, for example, but if a large loan is still outstanding against it, the person's actual financial position is different from the property's full value.
This is why income alone cannot tell the complete financial story. Two people earning the same salary can have very different financial positions. One may have savings and investments with little debt, while the other may have similar income but several loans and high monthly repayments.
Assets can strengthen financial stability in different ways. Cash and liquid investments can provide access to money when needed, while long-term investments may help build wealth over time. Income-generating assets can potentially create an additional source of cash flow.
Liabilities are not always automatically bad. Borrowing can sometimes help someone purchase a home, fund education or acquire something that has long-term value. The important question is whether the debt is manageable and whether the repayment burden fits comfortably within the person's finances.
The cost of debt matters too. A high-interest liability can grow quickly and reduce the money available for saving and investing. This is why controlling expensive debt can be an important part of improving your financial position.
Another useful concept is liquidity. An asset may have a high value but still be difficult to convert into cash quickly. Property is a common example. Having wealth tied up in long-term assets can be very different from having enough easily accessible money for an unexpected expense.
Regularly reviewing assets and liabilities can therefore reveal changes that a monthly salary figure cannot. Your investments may be growing, your loan balance may be falling or your cash savings may be increasing. Looking at these changes over time helps show whether your financial position is moving in the right direction.
It is also helpful to avoid confusing consumption with wealth creation. Expensive items may have a high purchase price but can lose value over time. Their financial impact should be considered alongside the debt or cash used to purchase them.
A simple personal balance sheet can make all of this easier to understand. List your major assets, list your outstanding liabilities and compare the two. Repeating this exercise periodically can help you see how your financial position evolves.
Ultimately, financial strength is not just about earning more. It is also about building valuable assets, managing liabilities responsibly and gradually increasing the gap between what you own and what you owe.
The goal is not to have zero liabilities at all times or to own a large number of assets. The goal is to create a financial position that gives you stability today while improving your ability to build wealth in the future.

.jpg)