How Small Financial Habits Can Build Long-Term Wealth
Building wealth does not always require a high salary or major investment decisions. Often, it begins with small financial habits that gradually improve the way people manage their money. Simple actions such as tracking expenses, saving regularly, and avoiding unnecessary purchases can create a stronger financial foundation over time.
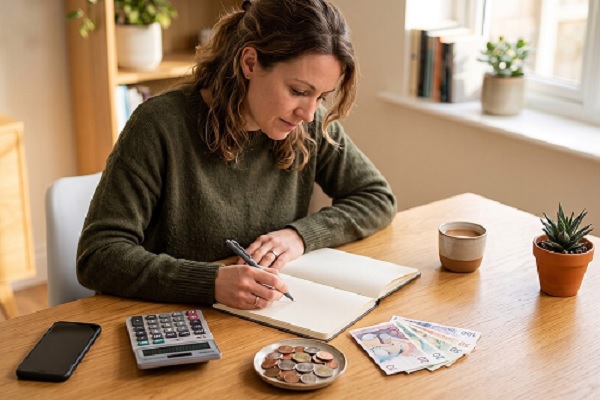
One of the most useful habits is understanding where money goes each month. Recording everyday expenses helps people identify spending patterns and recognise areas where they can save. Even small savings on frequent purchases can add up when maintained consistently.
Another important step is setting clear financial goals. Whether someone wants to build an emergency fund, purchase a home, or prepare for retirement, having a specific target makes saving more purposeful. Dividing a large goal into smaller monthly contributions can also make it feel more manageable.
Consistency matters more than occasional large efforts. Saving a fixed portion of income whenever possible helps develop financial discipline. As savings grow, individuals can explore suitable investment options based on their goals, time horizon, and comfort with risk. Understanding an investment before committing money is essential, as returns are never guaranteed.
Equally important is controlling lifestyle inflation. When income increases, it can be tempting to increase spending at the same pace. Maintaining a balance between enjoying the present and preparing for the future allows more money to go toward long-term financial goals.
Ultimately, wealth building is a gradual process shaped by everyday decisions. Tracking expenses, saving consistently, setting realistic goals, and making informed financial choices can help people improve their financial stability and work toward greater independence over time.