How to Make Your Money Work Harder for You
Earning money is important, but knowing how to manage, save and invest it effectively can make an even bigger difference to your financial future. Many people focus on increasing their income, yet building wealth also requires making smart decisions with the money they already have.
Making your money work harder means putting your savings and investments to productive use instead of allowing your entire income to remain idle. With proper financial planning, disciplined spending and a long-term investment approach, you can gradually build wealth and improve your financial security.
Here are some practical ways to make your money work harder for you.
1. Set Clear Financial Goals
The first step towards managing money effectively is understanding what you want to achieve. Your financial goals may include purchasing a home, funding your child's education, planning a holiday, building retirement savings or achieving financial independence.
Divide your goals into three categories:
Short-term goals: Expenses you expect to meet within the next three years.
Medium-term goals: Financial objectives that may take three to seven years.
Long-term goals: Retirement planning, wealth creation and other goals that require more than seven years.
Clear goals help you select appropriate savings and investment options based on your time horizon and risk tolerance.
2. Create a Monthly Budget
A budget helps you understand where your money goes every month. Without a spending plan, small expenses can gradually reduce the amount available for saving and investing.
One popular approach is the 50-30-20 budgeting rule:
50% of income for essential expenses such as rent, groceries and bills.
30% for lifestyle spending and personal interests.
20% for savings, investments and debt repayment.
You can adjust these percentages according to your income, responsibilities and financial goals. The important thing is to make saving a regular part of your budget.
3. Start Investing Early
Time is one of the most valuable factors in wealth creation. Starting investments early gives your money more time to potentially grow through compounding.
Compounding occurs when the returns earned on an investment are reinvested, allowing future returns to build on the original investment and previous gains.
For example, investing regularly over several decades may help create a substantial corpus, depending on the amount invested and the returns achieved.
Instead of waiting until you have a large amount of money, consider starting with an affordable investment amount and increasing it as your income grows.
4. Take Advantage of Systematic Investment Plans (SIPs)
Systematic Investment Plans (SIPs) allow investors to invest a fixed amount in mutual funds at regular intervals, usually monthly.
SIPs can help develop investment discipline and reduce the pressure of trying to predict market movements. They also allow investors to purchase more mutual fund units when prices are lower and fewer when prices are higher, a process known as rupee cost averaging.
However, mutual fund investments are subject to market risks. Returns are not guaranteed, and investors should select funds based on their financial goals, investment horizon and risk appetite.
5. Build an Emergency Fund
Before focusing entirely on wealth creation, establish an emergency fund to manage unexpected financial situations.
Medical expenses, job loss, urgent repairs or other unforeseen costs can disturb your financial plans. An emergency fund helps you meet these expenses without selling long-term investments or taking expensive loans.
A common starting target is three to six months of essential living expenses. Individuals with irregular income or greater financial responsibilities may need a larger reserve.
Keep this money in accessible and relatively low-risk options, such as a savings account or suitable liquid savings instruments.
6. Diversify Your Investments
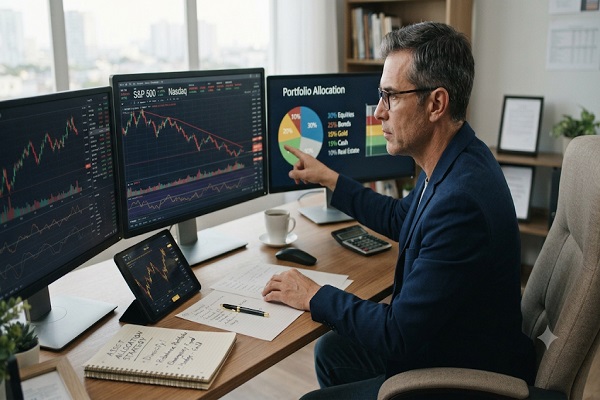
Putting all your money into one investment category can expose your finances to unnecessary risk. Diversification means spreading investments across different asset classes to reduce dependence on a single market or investment.
Depending on your financial goals and risk tolerance, your portfolio may include:
Equity mutual funds and stocks.
Fixed deposits and other debt instruments.
Public Provident Fund (PPF).
Gold and gold-related investment products.
Real estate and Real Estate Investment Trusts (REITs).
Each asset class has different risks, liquidity features and return potential. A diversified portfolio should reflect your individual financial circumstances rather than simply following market trends.
7. Reduce High-Interest Debt
High-interest debt can consume a significant portion of your income and limit your ability to invest.
Credit card balances and expensive personal loans may carry interest costs that outweigh the potential returns from many investments.
Make a repayment plan by listing outstanding debts, interest rates and minimum payments. Prioritise expensive debt while maintaining necessary payments on other obligations.
Reducing high-interest debt can improve cash flow and free up more money for savings and investments.
8. Make Your Savings Earn Interest
Keeping all your money in a regular savings account may not be the most effective approach for every financial goal.
Explore suitable options such as fixed deposits, recurring deposits and other regulated savings products. Compare interest rates, lock-in periods, withdrawal conditions, taxation and deposit protection before making a decision.
The right choice depends on when you need the money and how much risk you are willing to take.
9. Reinvest Your Investment Returns
Reinvesting returns can support long-term wealth creation. Instead of withdrawing every dividend, interest payment or investment gain, consider reinvesting the money when it aligns with your financial goals.
Reinvestment allows your capital to remain invested and potentially benefit from compounding.
However, remember that investment returns can fluctuate. Past performance does not guarantee future results, and reinvestment decisions should consider taxation, costs and portfolio allocation.
10. Increase Your Investments When Your Income Grows
When your salary or business income increases, it can be tempting to upgrade your lifestyle immediately. While enjoying the benefits of higher income is reasonable, allocating a portion of every increase towards investments can accelerate wealth creation.
For example, whenever you receive a salary hike, bonus or additional income, consider increasing your SIP contributions or adding to your long-term savings.
This approach helps prevent lifestyle inflation from consuming your entire income growth.
11. Review Your Financial Portfolio Regularly
Financial planning is not a one-time activity. Your income, responsibilities, goals and market conditions can change over time.
Review your portfolio periodically to check whether your investments remain aligned with your objectives. Rebalancing may be necessary when certain assets become a larger or smaller share of your portfolio than intended.
You should also review investment costs, tax implications, insurance coverage and emergency savings.
Avoid making frequent changes simply because of short-term market movements.
12. Protect Your Wealth with Insurance
Building wealth is important, but protecting it is equally essential. An unexpected medical emergency or loss of income can affect years of financial progress.
Health insurance can help manage eligible medical expenses, while term life insurance can provide financial protection to dependants in the event of the policyholder's death.
Choose coverage based on your family's needs, existing protection and financial responsibilities. Understand exclusions, waiting periods, policy conditions and premiums before purchasing insurance.
13. Avoid Investment Decisions Based on Market Hype
Social media trends, rumours and promises of unusually high returns can influence investment decisions. Investing without understanding the underlying risks may lead to financial losses.
Before investing, research the product, understand its risk profile and verify whether the provider is appropriately regulated.
Be cautious of guaranteed high-return claims, pressure to invest quickly and unverified investment schemes. A well-planned investment strategy should focus on your financial goals rather than short-term excitement.
14. Improve Your Financial Knowledge
Financial literacy helps you make informed decisions about saving, investing, borrowing and taxation.
Spend time understanding basic financial concepts such as inflation, compounding, asset allocation, risk diversification and tax planning.
Read reliable financial publications, study investment product documents and seek advice from a qualified financial professional when necessary.
The more you understand your financial choices, the better equipped you will be to manage your money responsibly.
Conclusion
Making your money work harder is not about finding a shortcut to becoming wealthy. It is about developing consistent financial habits, setting clear goals and making informed decisions.
Start by budgeting your income, building an emergency fund, reducing expensive debt and investing according to your financial objectives. Gradually increase your investments, diversify your portfolio and review your progress regularly.
Small financial decisions made consistently over time can create meaningful opportunities for long-term wealth creation. The earlier you begin managing your money effectively, the more time you give your financial plan to work towards a secure future.