Asset Management Companies : Fragmentation increasing in the AMC sector by Prabhudas Lilladher Ltd
Due to weak equity returns, 1-year weighted alpha over the last year across major MF players has reduced, leading to fragmentation in net equity flows. Contribution of top 3/10 players in net flows (ex-NFOs) has fallen from 42%/73% in FY26 to 34%/65% over Apr-Jul’26. Listed AMCs are underperforming as (1) sub-optimal returns are affecting market share in net equity flows; (2) global/macro uncertainty may lead to weak equity returns; and (3) core PAT growth in FY27 may be soft at 10% YoY. In contrast, non-AMC players like PRUDENT & KFINTECH have performed better over last 3-6 months due to more diversified revenue stream. Non-AMCs are likely to post superior core PAT CAGR vs listed AMCs over FY26-29E. While the AMC space is exposed to near-term risks, we are optimistic over the medium term as listed AMCs could see healthy core PAT CAGR of ~16% over FY27-29E. HDFCAMC & ICICIAMC remain our preferred picks.
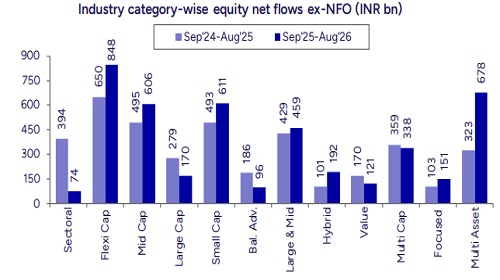
Equity returns have been sub-optimal: MF industry’s overall CLAuM as of Aug’26 stood at INR87.1trn with equity (+bal) at INR48.7trn. Returns for broader indices from Mar’25 till date have been sub-optimal, i.e., NIFTY 50 (-0.8%), NIFTY 100 (2.0%), BSE 200 (3.5%) and BSE 500 (6.5%). However, mid/small-cap indices have performed better (14-22% returns). In terms of categories, large and flexi-caps have returned only 7%/13%, while mid/small caps have delivered superior returns at 25%/29% and multi-cap & large & midcap have seen good returns at 17.9%/17.5%. In terms of net flows, we have seen flows shift from sectoral/thematic and large-cap to flexi/mid/small cap and multi-asset.
MTM for FY27 an overhang; we trim CLAuM growth for MF industry: We had initially estimated equity (+bal) CLAuM growth of 21% YoY for FY27; however, with moderation in net flows in the balanced category, and sub-optimal market returns following geopolitical uncertainty, we trim equity CLAuM growth by 250bps to 18.5% YoY. Also, due to weak returns, 1-year weighted alpha over the last year across major MF players has reduced, which has resulted in more fragmented net equity flows. Hence, contribution of top 3/10 players to net equity flows (ex-NFOs) has fallen from 42%/73% in FY26 to 34%/65% over Apr-Jul’26. In terms of performance, smaller MFs like Bandhan, HSBC, Invesco and Edelweiss are seeing strong performance in the 1/3-yr buckets.
Near-term overhang for AMCs; we remain positive for the medium term: Listed AMCs are underperforming as (1) market share of listed AMCs in net equity flows has fallen due to weak equity returns; (2) geopolitical/macroeconomic uncertainty may lead to flattish equity markets and (3) core earnings growth could be weak in FY27. In contrast, nonAMCs like PRUDENT and KFINTECH have seen better returns over the last 3-6 months due to a more diversified revenue stream (higher non-MF revenue share). Non-AMCs are likely to post superior core earnings CAGR compared to listed AMCs over FY26-29E. While the AMC space is exposed to near-term risks, we are optimistic for the medium term, as despite soft core PAT growth of 10% in FY27, listed AMCs could see decent ~16% CAGR in core PAT over FY27-29E.
Please refer disclaimer at https://www.plindia.com/disclaimer/
SEBI Registration No. INH000000271