U.S. Wheat Stocks Rise as Global Trade Forecast Weakens by Amit Gupta, Kedia Advisory
The 2026/27 wheat outlook points to higher U.S. supplies, increased domestic consumption, lower exports and rising ending stocks. U.S. wheat production is estimated at 1,534 million bushels, the smallest since 1970, while ending stocks are projected at 740 million bushels, 20% below last year. The season-average farm price forecast has been lowered to $6.30 per bushel. Globally, wheat supplies are projected at 1,103.9 million tonnes and consumption at 827.9 million tonnes. World trade is reduced by 2.8 million tonnes to 209 million tonnes, while ending stocks edge lower to 276 million tonnes amid changing export prospects.
Key Highlights
- U.S. wheat production reaches 1,534 million bushels, the lowest level since 1970.
- U.S. ending stocks rise 23 million bushels to 740 million, remaining 20% below last year.
- The U.S. season-average farm price forecast falls $0.10 to $6.30 per bushel.
- Global wheat trade declines 2.8 million tonnes to 209 million tonnes for 2026/27.
- Russian wheat exports fall to a five-year low of 40 million tonnes amid Black Sea disruptions.
The 2026/27 wheat outlook indicates increasing U.S. supplies and domestic consumption, alongside weaker export prospects and higher ending stocks. The season-average U.S. farm price forecast has been reduced by $0.10 per bushel to $6.30, reflecting increased stocks, reported prices and expectations for futures and cash prices during the remainder of the marketing year. Despite the production increase, U.S. wheat output remains historically low.
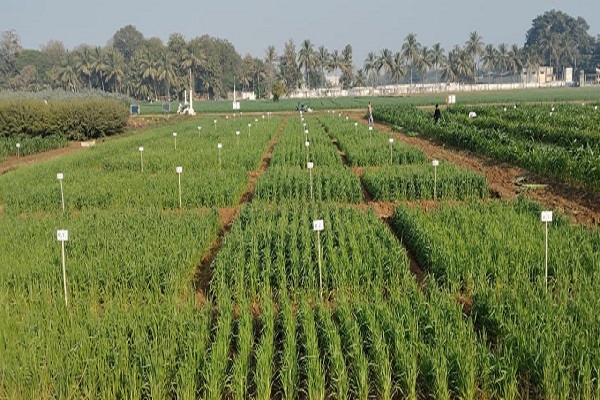
U.S. wheat supplies are projected to increase by 8 million bushels, supported by higher imports and production. The NASS Small Grains Annual Summary estimated production at 1,534 million bushels, as improved yields more than offset reduced harvested area. This remains the smallest U.S. wheat crop since 1970. Domestic use is raised by 10 million bushels due to higher feed and residual consumption, following stronger-than-expected disappearance during June–August. Conversely, exports are cut by 25 million bushels to 750 million, primarily because of weaker Hard Red Winter and Hard Red Spring sales and shipments. Higher White wheat exports partly offset the decline, while HRW remains uncompetitive internationally due to significantly higher prices than a year earlier.
Globally, wheat supplies are forecast to rise by 0.9 million tonnes to 1,103.9 million tonnes, mainly reflecting higher beginning stocks in Australia. Consumption increases by 1.2 million tonnes to 827.9 million tonnes, driven by higher feed and residual use in China and the European Union. EU production falls by 0.8 million tonnes to 133 million, while Canadian and Turkish production each rise by 0.5 million tonnes.
World wheat trade is projected to decline by 2.8 million tonnes to 209 million tonnes. Russian exports are reduced to 40 million tonnes, the lowest in five years, as Black Sea logistical disruptions constrain shipments. Global ending stocks edge lower to 276 million tonnes.
Higher U.S. stocks and reduced global trade reflect weaker export prospects, while historically low U.S. production and Black Sea disruptions continue to shape the wheat outlook.
Above views are of the author and not of the website kindly read disclaimer

.jpg)