Higher Soybean Output Lifts U.S. Oilseed Supplies, Palm Oil Weakens by Amit Gupta, Kedia Advisory

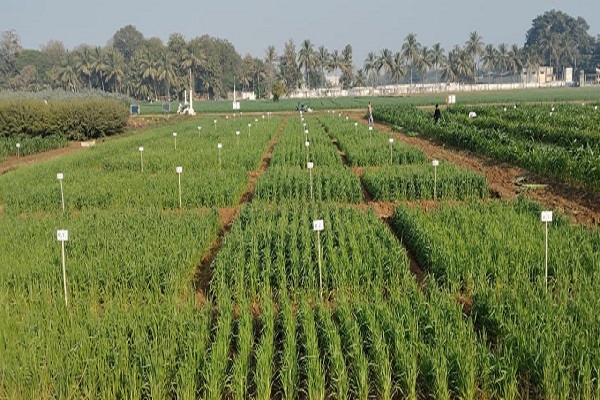
U.S. oilseed production for 2026/27 is forecast at 133.6 million tonnes, up 0.7 million tonnes from the previous month, driven by higher soybean and cottonseed output. Soybean production is projected at 4.56 billion bushels, with yields rising to 53.1 bushels per acre. U.S. soybean ending stocks increase to 315 million bushels, while the season-average price remains forecast at $12 per bushel. Global soybean production rises to 442.7 million tonnes, and ending stocks reach 124.3 million tonnes. Conversely, Indonesia’s palm oil production forecast falls by 2.2 million tonnes to 45 million tonnes amid dry weather.
Key Highlights
- U.S. oilseed production rises 0.7 million tonnes to 133.6 million tonnes for 2026/27.
- U.S. soybean production increases 27 million bushels to 4.56 billion bushels on higher yields.
- U.S. soybean ending stocks climb 5 million bushels to 315 million bushels.
- Global soybean production rises 0.4 million tonnes to 442.7 million tonnes, with ending stocks at 124.3 million tonnes.
- Indonesia’s palm oil production forecast falls 2.2 million tonnes to 45 million tonnes due to dry weather.
U.S. oilseed production for 2026/27 is forecast at 133.6 million tonnes, an increase of 0.7 million tonnes from the previous month. Higher soybean and cottonseed production more than offsets reductions in peanut, canola and sunflowerseed output. In the soybean market, the U.S. season-average price forecast remains unchanged at $12.00 per bushel, while soybean meal and soybean oil prices are projected at $340 per short ton and 70 cents per pound, respectively.
U.S. soybean production is projected at 4.56 billion bushels, up 27 million bushels from the previous forecast, as yields improve to 53.1 bushels per acre from September’s estimate of 52.8 bushels. Harvested area remains unchanged at 85.9 million acres. Soybean supplies increase by 17 million bushels to 4.90 billion, supported by higher production despite lower beginning stocks. With exports raised by 10 million bushels and crush unchanged, ending stocks are forecast to rise by 5 million bushels to 315 million.
Globally, soybean production for 2026/27 is projected to increase by 0.4 million tonnes to 442.7 million tonnes, primarily due to higher U.S. output. Lower production forecasts for India and the European Union partly offset this increase. Global crush is raised on stronger expectations for Argentina and Thailand, while exports increase on higher shipments from the United States and Nigeria. Global soybean ending stocks are forecast to rise slightly by 0.3 million tonnes to 124.3 million tonnes, despite reduced beginning stocks, including lower stocks in Argentina and the United States.
Meanwhile, Indonesia’s palm oil production forecast is cut by 2.2 million tonnes to 45 million tonnes due to dry weather over recent months. Global palm oil production in 2026/27 is expected to decline by 2.5 million tonnes from the previous marketing year, with global stocks falling to their lowest level since 2017/18.
Higher soybean production supports global supply growth, while dry weather in Indonesia tightens palm oil prospects and pushes global stocks toward multiyear lows.
Above views are of the author and not of the website kindly read disclaimer
.jpg)