Oil and Gas Sector Update : Crude Compass: Global Disruptions Reinforce Diesel Crack Strength Choice Institutional Equities
Developments over the past week:
* Ukraine struck Russia’s Syzran refinery, damaging its main crude-processing unit and tank farm during the week, despite discussions over a potential energy truce. Neither Russia nor Ukraine has confirmed an agreement to halt energy attacks. Continued strikes have curtailed Russian refining and exports, adding pressure to an already tight global diesel market. Moreover, Russia has extended its ban on export of diesel to October 31, as ~25% of the country’s refining capacity remains completely offline.
* Diesel inventories held by China’s state-owned fuel suppliers have declined to their lowest level in 15 months, while gasoline stocks are at their lowest since 2022. Meanwhile, Singapore’s distillate inventories, including diesel, remain significantly below their fiveyear average.
* Saudi Aramco has halted contracted crude supplies to Indian refiners following attacks on its East-West pipeline, previously a key alternative to Hormuz. Saudi Aramco has accounted for ~9% of India’s crude imports since the conflict began. Meanwhile, spot Brent prices are trading at USD20-30/b above respective futures price.
In our opinion:
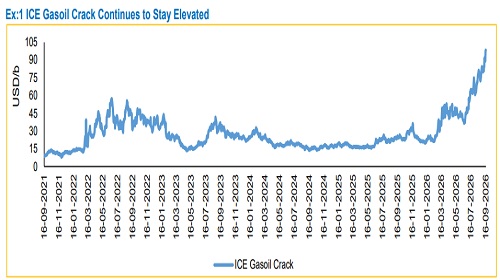
* Russian refinery outages add further upside risk to our base-case diesel crack estimates, particularly as disruptions coincide with the refinery maintenance season, continued constraints on Middle East-to-Europe product flows and multi-year-low inventories across key markets. Together, these factors support our thesis that we expect diesel cracks to remain elevated through FY27.
* Loss of Saudi term barrels forces refiners toward potentially higher-cost replacement crude while elevated freight further raises landed costs. However, if Russian refinery outages and low Asian inventories keep diesel cracks exceptionally strong, higher middledistillate realizations could outweigh crude-cost pressure - making diesel yield and refinery complexity increasingly important differentiators.
* While higher crude prices remain a headwind for OMCs, CPCL and MRPL continue to benefit from strengthening diesel cracks, with diesel prices rising faster than crude, as detailed in our Refinery Thematic report. We have TP of INR 215/sh and INR 1,540/sh for MRPL and CPCL respectively, implying current upside of 29.4% and 5.8% respectively. We may or may not revise our target price for MRPL and CPCL during Q2FY27 preview as we mark-to-market our estimates for the quarter
For Detailed Report With Disclaimer Visit. https://choicebroking.in/disclaimer
SEBI Registration no.: INZ 000160131