Oil and Gas Sector Update : Jul-Sep'26 Earnings Preview by Prabhudas Lilladher Ltd
We expect aggregate sales growth of 4.1%/39.4% QoQ/YoY in Q2FY27. EBITDA/PAT are expected to decline 5.6%/11.1% YoY, but improve 41.2%/51.9% QoQ, led by a recovery in OMC’s and a resilient upstream. Brent averaged USD91.4/bbl in Q2FY27 vs. USD96.9/bbl in Q1FY27. Upstream earnings of ONGC/OIL should remain supported by healthy crude realizations, albeit with some QoQ moderation. OMC performance is expected to improve sequentially, supported by stronger refining margins, although implied GMM’s are likely to remain under pressure, albeit with a sequential improvement. CGDs are expected to remain under pressure, as higher spot LNG prices and declining APM gas availability outweigh the benefit of price hikes, resulting in lower EBITDA/scm QoQ despite healthy volume growth. GAIL and PLNG are expected to deliver mixed performance, GAIL EBITDA is expected at INR46.7bn vs. INR63.8bn in Q1FY27, with the decline primarily reflecting normalization in the Trading business while PLNG utilization remains broadly stable. We remain positive on MGL and IGL, supported by healthy volume growth and an expected improvement in margins as gas supply constraints normalize and the impact of price hikes is captured fully.
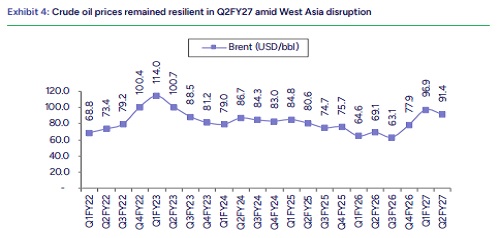
Crude prices rebound sharply on renewed US-Iran tensions: Brent crude prices remained relatively stable during the 1 st 2 months of Q2FY27, averaging USD86.0/bbl in July-Aug’26. However, renewed conflict between the US and Iran and fading prospects of peace talks triggered a sharp rally in Sep’26, with Brent peaking at USD108.8/bbl, taking the Q2FY27 average to USD91.4/bbl. The higher crude price environment is expected to support upstream earnings of ONGC and OIL. However, performance is likely to moderate QoQ, as crude realizations soften to USD91.4/bbl from USD96.9/bbl in Q1FY27. We ex[ect ONGC/OINL EBITDA of USD260.2/31.3bn in Q2FY27 vs USD294.5/40.8bn in Q1FY27.
CGD volumes remain resilient, but higher LNG costs weigh on margins: Qatar LNG supply shortfalls were largely offset by alternative supplies from the US, Nigeria, Oman and Mexico. However, spot LNG prices increased to USD22.1/MMBtu in Q2FY27 from USD17.7/MMBtu in Q1FY27, driven by prolonged disruption to LNG flows through the Strait of Hormuz, aggressive European restocking and increased spot buying from Asia. Meanwhile, HH remained broadly stable at USD2.9/MMBtu. Higher spot LNG costs, coupled with declining domestic APM gas availability, more than offset price hikes taken by CGDs, putting pressure on margins despite healthy volume growth. We expect EBITDA/scm to decline to INR2.4/7.0/4.5 for IGL/MGL/GGL in Q2FY27, from INR3.4/7.9/5.2 in Q1FY27, respectively. IGL and MGL volumes are expected to grow 2.1%/1.9% QoQ, respectively, while GUJENERG CGD volumes are likely to decline to 9.0mmscmd from 12.3mmscmd, led by lower Morbi volumes, as supply of alternative fuel - propane improves.
OMCs to see sequential improvement, supported by stronger refining margins: OMCs are expected to report a sequential improvement in Q2FY27, supported by stronger product cracks and softer crude prices QoQ, which should aid refining margins. However, marketing margins are likely to remain under albeit with an improvement in QoQ. We estimate GRMs of USD20.8/19.2/15.4/11.2/bbl for IOCL/BPCL/HPCL/MRPL, respectively, in Q2FY27. GMMs are also expected to improve sequentially, with losses narrowing to INR3.5/3.6/3.6/ltr for IOCL/BPCL/HPCL, respectively, from INR12.8/16.3/14.9/ltr in Q1FY27 based on Pre-SAED GRM’s. Consequently, we expect IOCL and BPCL to report EBITDA of INR94bn and INR21.3bn, respectively, while HPCL is likely to report an EBITDA loss of INR20.9bn, compared with EBITDA profit of INR20.2bn for IOCL and EBITDA loss of INR40.8bn/INR161.4bn, respectively, in Q1FY27.
Gas utilities: GAIL earnings to moderate QoQ; PLNG utilization remains stable: GAIL is expected to report transmission volumes of ~126mmscmd in Q2FY27, vs 122.4 in Q1FY27. Transmission volumes are estimated at 96.4mmscmd vs. 93.8mmscmd QoQ. EBITDA is expected at INR46.7bn vs. INR63.8bn in Q1FY27, with the decline primarily reflecting normalization in the Trading business. PLNG utilization is expected to improve from 60% to ~62% QoQ, with Dahej and Kochi operating at ~71% and 20% utilization, respectively, vs. 68%/24% in Q1FY27. Total regasification volumes are expected at 215TBtu in Q2FY27, up from 207TBtu in Q1FY27, supported by higher 3 rd party volumes. We estimate EBITDA at ~INR14.5bn, compared with INR15.3bn in Q1FY27.
RIL EBITDA expected to improve sequentially: We expect RIL’s standalone EBITDA to remain broadly flat QoQ at INR195.4bn. RJIL is expected to deliver 3.0% QoQ EBITDA growth, while the Retail business is likely to report broadly flat EBITDA growth YoY. On a consolidated basis, we expect RIL’s EBITDA to grow 3.4% QoQ to INR491.4bn.
Change in estimates: For ONGC/OINL, higher crude oil realizations have led us to raise our FY28E EPS estimates in the range of 2-8%. For OMCs, Q2FY27 is expected to improve sequentially, supported by better refining performance and softer crude prices QoQ; accordingly, we have revised FY27E EPS estimates upwards. Within the CGD space, we have cut FY28E EPS estimates for MGL and IGL by ~1-4%. In addition, given the improvement in refining performance, we upgrade BPCL to Accumulate from Hold and HPCL to Hold from Reduce.
Top picks: MGL and IGL remain our preferred CGD picks, supported by strong CNG and PNG volume growth, which is expected to accelerate as higher gas normalizes post the US-Iran conflict and the impact of price hikes is captured fully
Please refer disclaimer at https://www.plindia.com/disclaimer/
SEBI Registration No. INH000000271

More News

Education Sector Update : RM inflation continues to weigh on margins by Prabhudas Lilladher ...