Oil & Gas Sector Update : 2QFY27 preview - Sequential improvement across players by Emkay Global Financial Services Ltd
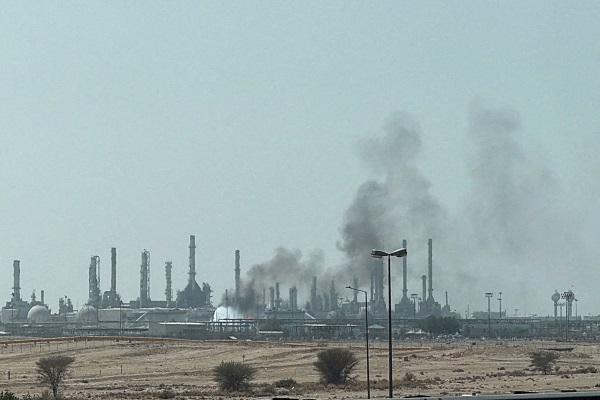
Supply disruptions and elevated prices amid the ME conflict continued to impact the sector in 2Q, though a brief de-escalation early in the quarter pulled average crude prices down. Refining cracks remained elevated, while OMC marketing losses narrowed, on lower crude prices and full impact of retail price hikes. Gas demand was resilient despite supply disruptions, supported by alternative supplies. OIL is expected to deliver strong oil production growth
Narrowing marketing losses and inventory gains to support OMCs’ earnings
Benchmark GRMs softened qoq to $18.0/bbl from $24.7/bbl, though petrol/diesel cracks remained elevated amid supply disruption. OMCs’ petrol/diesel marketing margins (unadjusted for windfall levy) improved to Rs2.9/(Rs16.7) per ltr in 2QFY27 vs (Rs12)/(Rs32) per ltr in 1QFY27, supported by lower crude prices and full impact of retail price hikes. ATF margins also improved, following the regular price hikes from Jul-26, while LPG under-recoveries also narrowed, to ~Rs290/cyl. Brent averaged at ~$97/bbl in 2Q, down 6% qoq, but closed higher at ~$120/bbl vs ~$72/bbl at 1QFY27-end, implying significant inventory gains. However, we build in inventory gains of $3.5/1.5 per bbl for HPCL/BPCL, while IOCL is expected to record a $2.0/bbl inventory loss due to its longer inventory cycle. With marketing losses narrowing gradually, OMCs’ earnings are expected to improve, with IOCL/BPCL/HPCL EBITDA at Rs86.9/69.7/21.8bn.
Lower realizations to weigh on upstream earnings; OIL records strong oil output OIL’s total crude output
is estimated to grow a strong 20% yoy, while that of ONGC would decline 6%. Gas output is likely to decline ~3% yoy for both. With crude oil prices declining qoq, oil realization is expected to fall ~6% qoq; we expect gas realization to decline for ONGC (lower NWG prices qoq) and remain broadly flat for OIL. Despite the stronger production, we expect OIL’s EBITDA to decline 5% qoq on higher opex, while ONGC’s EBITDA is likely to fall 8% qoq owing to lower production and higher opex. We estimate ONGC/OIL’s RPAT at Rs171.9/25.0bn for 2QFY27. NRL’s EBITDA is expected to be broadly steady qoq, at Rs18.5bn, with book GRMs largely flat at $45.0/bbl.
GAIL’s earnings normalize from a high base; PLNG better on higher utilization
GAIL’s EBITDA is expected to decline 20% qoq to Rs51.2bn, albeit from a high 1QFY27 base. Gas transmission volumes are likely to rise 10% qoq to 135mmscmd. Gas marketing EBITDA is expected to decline 36% qoq, as margins normalize from the 1Q highs, albeit remaining robust. Petchem should turn EBITDA-positive to Rs490mn, supported by 95% utilization and lower unit opex. LPG earnings are likely to decline qoq on weaker realizations, partly offset by lower unit opex. Despite supply disruption, PLNG’s Dahej utilization is expected to improve to 72%, supported by healthy gas demand, while Kochi utilization is likely to be stable at 25%. EBITDA is expected to rise 5% qoq to Rs17.2bn, with marketing margin improving slightly to $8.4/mmbtu.
CGD’s earnings improve sequentially; volume growth steady
MGL is expected to report volume growth of 8% yoy, impacted by lower I/CPNG volumes. EBITDA is expected to increase 1% qoq to Rs3.4bn; however, unit EBITDA is likely to decline 4% qoq to Rs7.6/scm on higher gas costs and opex. For IGL, despite the higher gas costs, EBITDA/scm is expected to improve 7% qoq to Rs3.6, supported by lower unit opex, driving a 12% qoq uptick in EBITDA to Rs3.3bn. Volume growth is expected at 7% yoy, amid the supply rationalization in 2QFY27.
O2C to drive strong earnings growth for RIL; Jio remains healthy
We estimate RIL’s consolidated EBITDA to increase 11% qoq to Rs525bn (up 14% yoy). O2C EBITDA is expected to rise 22% qoq to Rs207bn, driven by stronger distillate spreads, better petchem realizations, and higher throughput. For Jio, we expect net subscriber addition of 10mn, with ARPU improving 1% qoq to Rs217.8, driving a 3% qoq EBITDA growth. Retail EBITDA is likely to decline 1% yoy at Rs67bn (up 7% qoq) on account of the modest 2% yoy revenue growth. Despite the ~3% sequential decline in gas production, upstream EBITDA should be flat qoq at Rs49bn on lower opex. We estimate consolidated APAT (after MI) to rise 11% qoq to Rs232bn
Healthy volume growth for Gulf Oil Lube to offset margin moderation
We estimate core lube volumes to grow 15% yoy, while AdBlue volumes are expected to increase ~6% yoy. EBITDA/ltr is likely to decline 5% qoq to Rs18.3 on higher RM costs and unit opex. RPAT is expected to increase 31% yoy to Rs1.1bn.
For More Emkay Global Financial Services Ltd Disclaimer http://www.emkayglobal.com/Uploads/disclaimer.pdf & SEBI Registration number is INH000000354


More News
Aviation and Renewables Sector Update : 2QFY27 preview - RE resilient; fuel and forex weigh ...