Defence & Aerospace Sector Update : Execution Takes Centre Stage; Exports Add Upside by Choice Institutional Equities Ltd
Execution Takes Centre Stage; Exports Add Upside
We expect Q2FY27 to mark the beginning of an execution-led phase for the Indian defence & aerospace sector. After a seasonally soft Q1, production and deliveries are likely to improve sequentially across missiles, defence electronics, aerospace and shipbuilding, although quarterly performance will remain lumpy given milestone-based revenue recognition. With order books already at elevated levels, the market is likely to focus less on order additions and more on production ramp-ups and delivery schedules. We expect this to drive greater earnings differentiation through H2FY27, favouring companies with visible execution and diversified programme exposure.
The medium-term pipeline remains strong, with QRSAM, P-75(I), NextGeneration Corvettes, additional Scorpene submarines, Next Generation Missile Vessels, NGOPVs and other missile and air-defence programmes moving towards contract awards and execution. Recent DAC approvals of ~INR 1.1 Trn, along with the earlier ~INR 520 Bn package, reinforce the breadth of opportunities across air defence, counter-drone systems, missiles, naval platforms, electronic warfare and unmanned systems. We, therefore, see FY27–FY30 as a strong multi-year manufacturing opportunity, with the key upside coming from the conversion of these approvals into contracts and, subsequently, into domestic production.
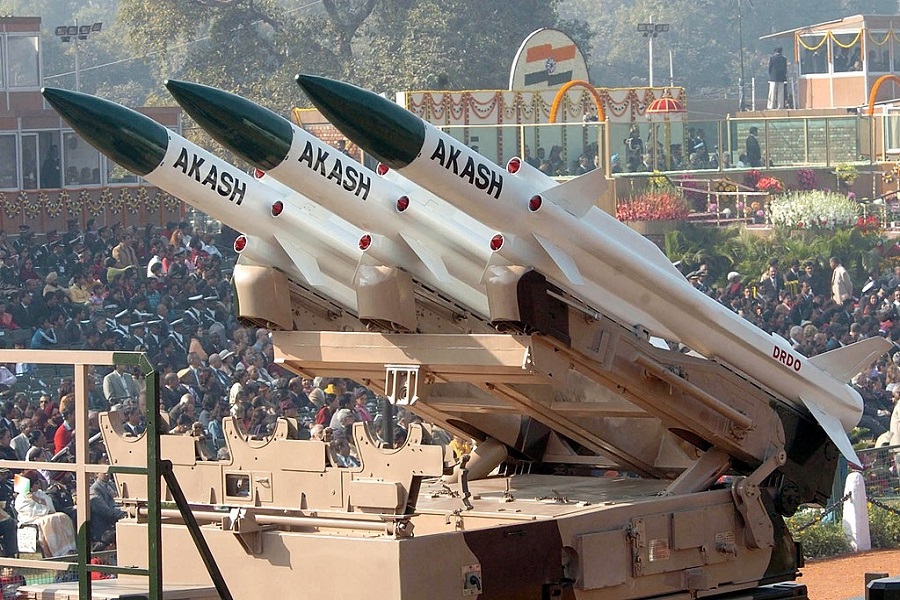
Exports are emerging as a meaningful second growth engine for Indian defence manufacturing. Defence exports reached a record INR 38,424 crore in FY26, up 62.7% YoY, with Indian defence products now reaching 80+ countries. More importantly, the mix is shifting towards high-value indigenous weapon systems, with BrahMos and Akash gaining traction in overseas markets. BrahMos’ Philippines order, along with potential opportunities in Indonesia and Vietnam, could take its export pipeline beyond USD 600 Mn, while Akash has expanded its customer base beyond Armenia to Tajikistan and Turkmenistan. We see rising exports as a structural positive, with repeat orders and aftermarket opportunities potentially expanding the addressable market beyond domestic procurement.
Execution Improves, but Earnings Recovery Remains Uneven
We expect Q2 to mark the transition from the strong order-book buildup of the past 12–24 months towards a more visible H2FY27 earnings cycle. While platform-heavy businesses remain vulnerable to delivery and milestone phasing, defence electronics and specialised engineering are likely to have relatively better visibility, supported by shorter production cycles and multi-platform exposure. We, therefore, see Q2 as a differentiation quarter rather than a broad-based sector re-rating, with execution quality, margin sustainability and cash conversion emerging as the key earnings drivers.
Our view : We remain constructive on Indian defence & aerospace, but see the opportunity becoming increasingly stock-specific. We prefer companies with visible execution, high indigenous content, diversified programme exposure and export optionality. The next leg of the defence cycle will be defined less by order-book creation and more by the speed and quality of order-book conversion into revenues and cash flows.
Risk associated with our view: Execution delays remain the key nearterm risk, particularly due to customer acceptance, imported components and milestone-based deliveries. Order-book conversion and quarterly execution phasing could drive earnings volatility.
High-conviction investment ideas:
We remain positive on BDL, GRSE and BEL, which are expected to deliver healthy Q2FY27 results, while offering strong medium-term earnings visibility and favourable riskreward at current levels.
For Detailed Report With Disclaimer Visit. https://choicebroking.in/disclaimer
SEBI Registration no.: INZ 000160131
Tag News
Revised SOP for using proof ranges, field firing ranges, test facilities approved for Indian...