Monthly Auto Sales - September 2026 by ARETE Securities Ltd
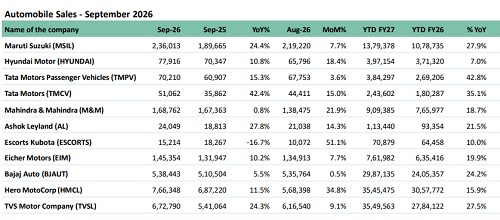
Auto industry volumes rose 14% YoY and 14% MoM in September, as OEMs stepped up dispatches to restock dealers ahead of a festive season that starts later than last year, with Navratri beginning on October 11 versus September 22 last year. PV dispatches grew 21% YoY and 5% MoM, led by MSIL, as dealer stocking ran ahead of retail registrations. CV dispatches rose 28% YoY and 17% MoM, the strongest YoY growth among segments, with Trucks leading and EIM and TMCV outpacing peers. 2W volumes grew 13% YoY and 15% MoM, with HMCL regaining the monthly lead over TVSL and extending its YTD lead. Tractor volumes declined 20% YoY though rose 70% MoM, as the later festive season and a high GST-led base from September 2025 weighed. Exports rose 26% YoY though eased 2% MoM, with their contribution slipping to ~22%, below the 12-month average of ~24%. Overall, the increase in sales reflects pre-festive restocking across segments, with tractors the only segment to decline YoY on calendar and base effects.
PV Segment
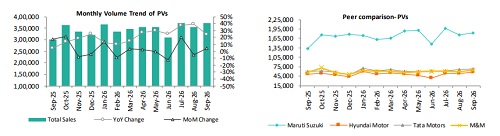
PV domestic dispatches rose 21% YoY and 5% MoM. MSIL led growth at 30% YoY and 3% MoM, followed by TMPV at 15% YoY and 5% MoM, while MM rose 14% YoY and 8% MoM and HYUNDAI grew 11% YoY and 5% MoM. Industry dispatches were estimated to have run well ahead of registrations as dealers restocked for the festive season, with Navratri moving to October and the final days of September falling in Shraddh, when purchases are typically deferred. Exports rose 7% YoY and 39% MoM, as HYUNDAI recovered 82% MoM from August's West Asia-linked logistics constraints and MSIL grew 31% MoM
CV Segment
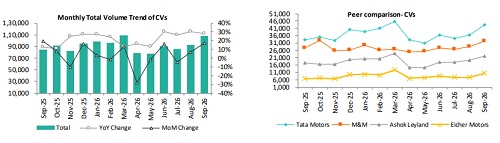
CV dispatches rose 28% YoY and 17% MoM, led by Trucks. Trucks, accounting for 67% of volumes, grew 32% YoY and 22% MoM, led by EIM's 61% YoY surge even as M&M remained the largest contributor by volume. LCVs (18% mix) rose 21% YoY and 9% MoM, led by TMCV's 32% YoY growth, which also added the bulk of incremental volume. Buses (8% mix) grew 39% YoY and 2% MoM, led by TMCV's 55% YoY growth even as AL and M&M eased sequentially. Freight demand, infrastructure activity and fleet replacement were cited as key drivers, while TMCV's price increase effective October 1 potentially pulled some purchases into September.
2W Segment
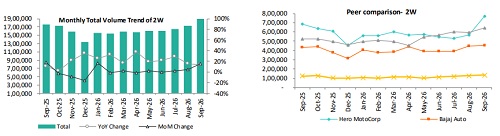
2W volumes rose 13% YoY and 15% MoM. Domestic dispatches rose 9% YoY and 22% MoM, led by TVSL's 17% YoY growth and HMCL's 36% MoM jump, even as BJAUT declined 12% YoY. Exports rose 30% YoY though eased 5% MoM, led by TVSL's 48% YoY surge, even as HMCL's export shipments declined and BJAUT eased sequentially. HMCL regained the lead over TVSL on monthly 2W dispatches (~19% ahead) and extended its YTD FY27 lead on a like-for-like 2W basis to ~4%. The e-2W segment saw TVSL/BJAUT/HMCL accounting for 27%/24%/ 12% share and 54.0k/48.4k/24.3k registrations, respectively. Elevated petrol prices continued to support the TCO-led shift toward e2Ws.
Tractor Segment
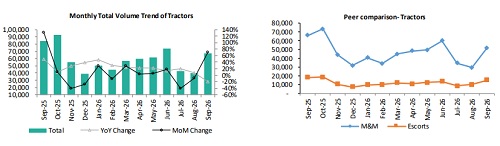
Tractor domestic dispatches declined 21% YoY though rose 75% MoM, with MM down 23% YoY to 50.2k units and ESC down 16% YoY to 14.9k units. Both companies attributed the YoY decline to the festive season shifting into October and a high September 2025 base, which benefited from the GST rate cut, while ESC also cited a patchy monsoon and lower kharif sowing. Exports rose 35% YoY though eased 11% MoM, taking total tractor volumes down 20% YoY though up 70% MoM.
Please refer disclaimer at http://www.aretesecurities.com/
SEBI Regn. No.: INM000012

More News

Power Sector Update : A good quarter led by power demand uptick by Prabhudas Liladhar Capital