Commodity Daily Insights 16th Sept 2026 By - HDFC Securities Ltd
GLOBAL MARKET ROUND UP
Precious metals rebounded during Wednesday’s Asian session, although gains remained limited as investors adopted a cautious stance ahead of the Federal Reserve’s policy decision later today. Markets are widely expecting a 25-basis-point rate hike, with CME FedWatch indicating a 92.4% probability of such a move. The decision will be followed by a press conference from Fed Chair Kevin Warsh, with forward guidance likely to be more important for the market direction.
A hawkish policy stance or guidance could place further pressure on gold by supporting the U.S. dollar and Treasury yields, while softer signals could ease rate-hike expectations and provide some relief to bullion. Meanwhile, traders continue to monitor elevated oil prices and developments in the Middle East, with Saudi Arabia issuing security alerts across parts of the country following recent attacks by Iranaligned forces.
Overall, today’s Fed decision and forward policy guidance will be the key catalysts for gold, with the dollar and Treasury yields likely to determine the broader market reaction.
WTI crude oil futures held above $105 per barrel on Wednesday, remaining near a four-month high as supply disruptions across the Middle East intensified. Saudi Arabia reportedly cancelled several September shipments after drone attacks forced the closure of its East-West pipeline, with European customers notified of the cuts. The pipeline provides an alternative export route around the Strait of Hormuz, but there is no clear timeline for the resumption of operations as Iran-backed Houthi militants renewed attacks on Saudi Arabia. Supply concerns were further heightened after Libya’s national oil company suspended operations at two oilfields and a pumping station amid ongoing protests. However, prices pulled back after industry data showed a surprise build in U.S. crude inventories, despite widening supply disruptions in the Middle East. API data showed U.S. crude stockpiles increased by 7.14 million barrels last week, following a 300,000-barrel drawdown in the previous week and defying expectations for another decline.
Natural gas futures posted a second consecutive gain as above-average summer heat extended into September, supporting cooling demand. However, the advance remains limited as temperatures gradually ease with the season progressing.
Gold
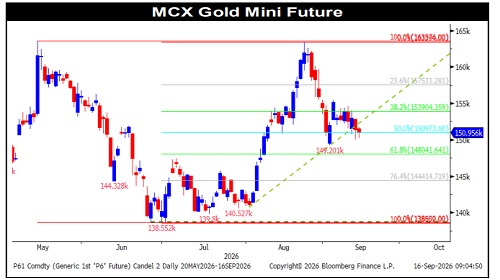
• Trading Range: 150180 to 153480
• Intraday Trading Strategy: Buy Gold Mini Sep Fut at 151400-151425 SL 150680 Target 152380/152900
Silver
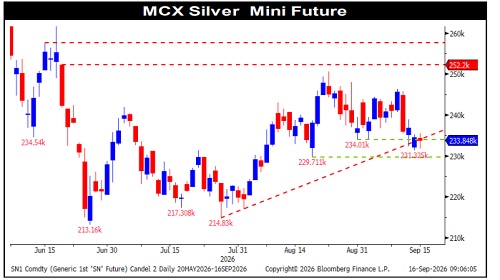
• Trading Range: 232050 to 239900
• Intraday Trading Strategy: Buy Silver Mini Nov Fut at 235350-233375 SL 233900 Target 237450/238500
Crude Oil
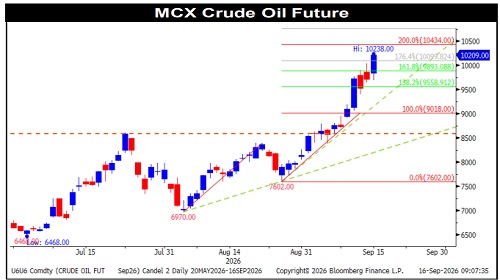
• Trading Range: 9575 to 10350
• Intraday Trading Strategy: Sell Crude Oil Sep Fut at 10125-10135 SL 10300 Target 9950/9905
Natural Gas
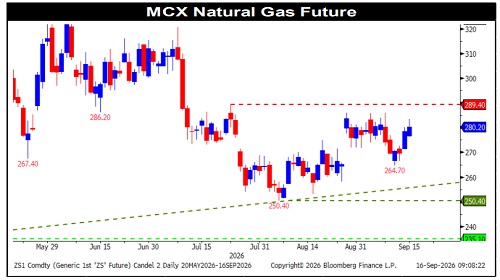
• Trading Range: 272 to 294
• Intraday Trading Strategy: Sell Natural Gas Sep Fut at 285-286 SL 291 Target 279.80/277
Copper
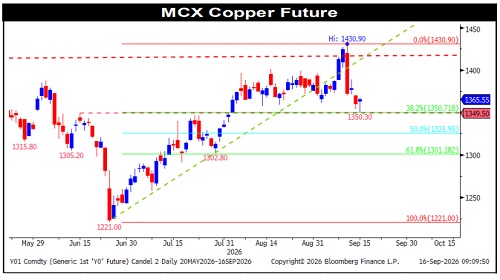
• Trading Range: 1356 to 1382
• Intraday Trading Strategy: Sell Copper Sep Fut at 1379-1379.50 SL 1387 Target 1372/1367.0
Zinc
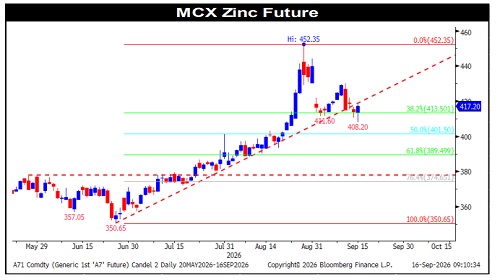
• Trading Range: 409 to 426
• Intraday Trading Strategy: Buy Zinc Sep Fut at 415.0- 415.50 SL 412.0 Target 420.8/422.0
Please refer disclaimer at https://www.hdfcsec.com/article/disclaimer-1795
SEBI Registration number is INZ00017133