Buy Ashok Leyland Ltd For Target Rs.179 By Geojit Financial Services Ltd
Strong Volume Momentum, Margin Pressure Transient
Ashok Leyland Ltd. (AL) is the second-largest Commercial Vehicle (CV) manufacturer in India. It has a strong presence in the truck segment, with a domestic MHCV market share of ~31% for FY26.
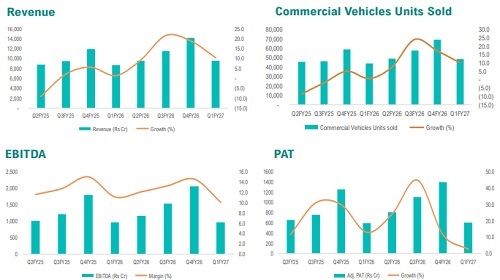
* AL reported its highest ever Q1 revenue of Rs. 9,634cr (+10% YoY), PAT of Rs. 609cr (+3% YoY) and record Q1 CV volumes of 48,763 units.
* EBITDA was flat YoY at Rs. 970cr and margin contracted 100bps YoY to 10.1%, as material cost rose on commodity inflation, partly offset by price hikes and cost savings.
* Domestic MHCV truck volume grew 15% YoY to 22,998 units and LCV rose 21% YoY to a Q1 record of 18,874 units. Bus volumes fell as AL avoided unprofitable orders.
* Non-CV businesses stayed strong, with aftermarket revenue up 12.7%, power solutions up 51% and defence up 64% YoY. CV exports, however, fell 18% YoY to 2,461 units on war-led disruption.
* We expect revenue to grow by ~10% CAGR and earnings by ~11% CAGR over FY26- 28E, factoring in GST 2.0-led replacement demand, premiumisation and margin recovery in H2FY27.
Outlook & Valuation
The CV upcycle is led by GST 2.0, which has improved the economics of replacing an ageing BS3/BS4 fleet with a new BS6 truck. Volume growth stayed strong YoY in July and August, while price hikes, cost savings and a better mix should cushion margins. Hinduja Leyland Finance’s listing via merger into NDL Ventures, pending final NCLT sanction, will unlock value in AL's 61% stake and give HLF direct access to public capital. Given the volume upcycle and a net cash balance sheet, we value AL's standalone business at 12.5x EV/EBITDA to arrive at Rs. 164 per share and Hinduja Leyland Finance separately at Rs. 15 per share, arriving at a target price of Rs. 179, and reiterate the Buy rating at CMP.
Key Highlights
* Roughly a fourth of the quarter's material needs came from cheaper opening inventory, cushioning gross margin. We expect the Q2 commodity impact to exceed Q1, with relief largely from Q4.
* Cumulative price increases this fiscal year are ~2.25% for MHCV and over 3.5% for LCV, including a July 1 hike. A further hike and discount optimization are being evaluated.
* AL launched an industry-first air suspension in multi-axle trucks, offering a 4-tonne extra payload against the usual 2-tonne. HIPPO tractors and TAURUS tippers are seeing strong traction.
* Monthly MHCV volume needed to cover fixed costs has fallen from 6,000-7,000 trucks to 1,000-1,500, on lower fixed costs and nonMHCV growth.
* In Q1FY27, Hinduja Leyland Finance AUM grew 20% YoY to Rs. 60,310cr and PAT rose 37% YoY to Rs. 123cr, with a net NPA of 2.1%.
* AL added 33 touchpoints in the quarter, taking the network to 2,137, focused on North and East. Switch Mobility's order book stands at 2,100 e-buses.
* Capex for Q1 was Rs. 153cr, focused on alternate powertrains and EVs.
For More Geojit Financial Services Ltd Disclaimer https://www.geojit.com/disclaimer
SEBI Registration Number: INH200000345