Buy Petronet LNG Ltd for the Target Rs.360 by Emkay Global Financial Services Ltd
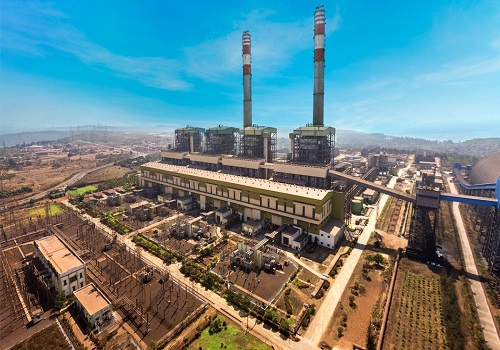
We visited PLNG’s Kochi terminal and interacted with top management. Despite the prevailing ME crisis and higher LNG prices, Indian LNG demand remains steady, driven by the fertilizer, power, and CGD sectors. With GAIL’s overseas volumes (HH) fully routed to India and Qatar Energy’s loss offset by liquefaction facilities elsewhere operating above nameplate capacities, physical supply conditions are stable. PLNG is benefiting as cargoes are currently preferred at Dahej, the country’s most well-connected terminal (6 evacuation pipelines with 35mmtpa capacity). Hence, 2Q volumes appear better than 1Q, and once Hormuz normalizes, volumes could see a material surge, with Qatar likely requiring only 2-4 weeks to ramp up and Dahej’s expanded capacity now available. The management also hinted that the renewal of Qatar’s 7.5mmtpa contract involves only a change in the delivery term from FOB to DES; hence, the shipping cost benefit (with slope largely remaining in line) would be passed on to customers, while other components of the regas tariff are unlikely to change. However, PLNG remains open to offering discounted rates on new capacity to existing long-term customers. We note that PLNG has a natural hedge against spot LNG prices, as higher prices, while impacting tolling volumes, can lead to sizeable trading margins, as seen in 1Q. We raise FY27E EPS by 12% on better volumes and margins, while slightly increasing FY28-29E EPS by 2-4% each. We reiterate BUY and TP of Rs360.
Kochi ramping and diversifying, Bangalore pipeline expected in FY27
The Kochi-Bangalore pipeline has only the Coimbatore-Bangalore section pending, which is expected to be completed in FY27. CGD opportunities within Kerala are also strong and should support Kochi’s ramp-up. The terminal also provides ancillary services such as GUCD, storage, and bunkering. GUCD has been ramped up, with 1-1.5 days of operational time, similar to Singapore. Truck-loading capacity is currently 40/day with 4 skids. Orders for key bunkering equipment have been placed, with all major equipment already received at site. Installation and integration activities are in progress and are expected to be completed by Mar-27.
Capex in progress; CBG in focus as Govardhan scheme provides support
PLNG’s capex plans, comprising the third jetty, petchem, and SS LNG, are progressing. While the third jetty has achieved 70% completion vs the 81% target and has seen monsoon and technical delays, it is expected to be commissioned next year. Engineering activities for the petchem project are at an advanced stage and ~80% complete. All longlead items and equipment have been ordered, while civil and mechanical works are in full swing. Overall, the project is ~42% complete and is likely to be commissioned by mid-FY29. C2-C3 handling capacity would be raised from 1.3 to 3mmtpa by Jun-28, driven by strong demand. Railways has also approved ethane transportation and rates.
For More Emkay Global Financial Services Ltd Disclaimer http://www.emkayglobal.com/Uploads/disclaimer.pdf & SEBI Registration number is INH000000354