Buy Petronet LNG Ltd for the Target Rs 362 by Motilal Oswal Financial Services Ltd
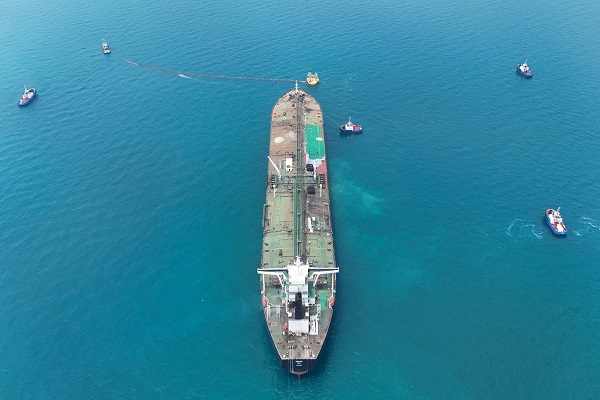
Kochi terminal to drive earnings: GUCD, grid connectivity, and bunkering open three new avenues
* PLNG has corrected ~11% over the last seven months, primarily due to:
1) Qatar Energy's declaration of force majeure
2) elevated spot LNG prices, averaging ~USD19-20/mmbtu in 1HFY27’YTD (vs. ~USD12/mmbtu in FY26), raising the risk of slowdown in gas demand
3) growing investor concerns around a regas tariff cut at Dahej.
* In this note, we highlight the following:
1) Kochi terminal could emerge as a new earnings driver for PLNG:
a) Gassing Up and Cooling Down (GUCD) is emerging as a new earnings stream, with annual revenue potential of INR1b, as turnaround time has already improved to 1.5 days from 4 earlier, on par with Singapore
b) the Kochi-Mangalore-Bangalore pipeline (KMBPL) could be commissioned within 6 months, by Mar'27 (GAIL is guiding for Dec'26), finally linking Kochi to the national gas grid. Volumes are currently capped to Kerala and a small quantity in Tamil Nadu, but management expects Kochi utilization to rise to ~40% over the next 2-3 years, aided by Kerala's CGD build-out and a pickup in LNG trucking
c) PLNG is also exploring bunker fuel supply at Kochi as a further, albeit still nascent, earnings avenue.
2) Dahej regas tariff: floor holds at current levels: In a recent investor interaction with PLNG management, attended by Shri Akshay Kumar Singh (MD and CEO) and team, management indicated that the new tariff for the 7.5mmtpa Qatar contract will not be lower than the current one, as Dahej already has the lowest tariff among terminals in the country.
Dahej tariff: Floor holds at current levels
* Investor concerns around a Dahej tariff cut appear overdone, in our view. Dahej is already the lowest-tariff LNG terminal in the country, and management has been explicit that the tariff on the renegotiated 7.5mmtpa Qatar contract now extended to CY48 and shifting from an FOB to a DES structure will not fall below the current level. Any reduction in shipping costs will simply be passed through to offtakers rather than reflected in a lower tariff.
* This provides comfort on roughly half of Dahej's book that runs on long-term contracts; the other half, tolling volumes, is contractually locked in through CY35 with defined tariffs and minimum utilization commitments. Our own DCF continues to bake in a 5% tariff cut at Dahej in FY28, followed by a 4% annual escalation, which we view as conservative relative to what management is now signaling.
Utilization: Waiting on price, not demand
* Dahej's expanded capacity of 22.5mmtpa (which can technically flex to 25mmtpa) came onstream two months ahead of schedule and at a striking INR5.6b, roughly a tenth of what a comparable greenfield terminal would cost, reinforcing PLNG's structural cost advantage over newer entrants.
* The near-term drag is simply price: LNG cost has more than doubled for end consumers, so offtakers are unwilling to commit to fresh long-term volumes at current levels, and we expect utilization to inflect only once prices normalize and latent demand re-emerges. There are already early signs of this happening—new ~0.5mmtpa contracts each with ExxonMobil and Equinor (Deepak Group) have started flowing this fiscal—but at a system level, India's LNG imports of 24-25mmt remain below the 26mmt pre-Covid run rate, underscoring how little net growth the industry has seen through a difficult fiveyear stretch.
* On the balance sheet side, the overhang from use-or-pay dues has shrunk sharply, from a peak of INR20b to INR3.1b net of provisions, and management does not expect any offtaker defaults this year.
* Valuation and view:
Our DCF-based TP of INR362 (WACC: 11.5%, TG = 2%) assumes a 5% tariff cut at the Dahej terminal in FY28, followed by a 4% rise for both terminals. While we have incorporated the full capex for the petchem plant, we value it conservatively at 0.5x FY29E P/B and discount this back to FY27.
For More Research Reports : Click Here
For More Motilal Oswal Securities Ltd Disclaimer
http://www.motilaloswal.com/MOSLdisclaimer/disclaimer.html
SEBI Registration number is INH000000412