Emergency Funds: Why Every Household Needs a Financial Safety Net
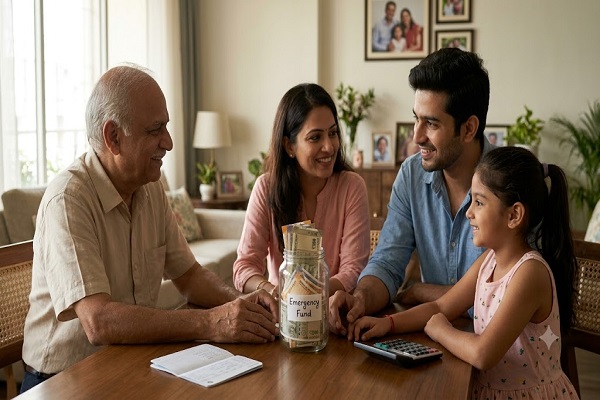
Life is full of uncertainties, and unexpected expenses can arise at any time. A medical emergency, sudden job loss, vehicle repair, home maintenance or an unexpected family responsibility can create financial pressure without warning. While regular savings and investments help people achieve long-term financial goals, having money readily available for emergencies is equally important.
This is where an emergency fund becomes essential. An emergency fund is a dedicated amount of money kept aside to manage unexpected expenses without disturbing regular household budgets, long-term investments or financial plans.
In 2026, as living costs and financial responsibilities continue to influence household budgets, building an emergency fund is an important step towards financial stability and peace of mind.
What Is an Emergency Fund?
An emergency fund is a financial safety net designed to cover unexpected expenses or temporary income disruptions.
Unlike regular savings meant for holidays, shopping or planned purchases, emergency funds are reserved for situations that require immediate financial attention.
For example, if a person suddenly loses their job, an emergency fund can help cover essential expenses such as rent, groceries, electricity bills, school fees and loan payments while they look for another source of income.
The main purpose is to ensure that unexpected financial challenges do not force households to depend heavily on credit cards, personal loans or borrowed money.
Why Does Every Household Need an Emergency Fund?
Unexpected situations can affect anyone, regardless of income level. Having a financial reserve helps households manage these situations more confidently.
1. Protection Against Job Loss
A sudden job loss or reduction in income can disrupt monthly financial commitments. An emergency fund provides temporary financial support while individuals search for new employment or alternative income opportunities.
2. Handling Medical Emergencies
Medical expenses can arise unexpectedly, even when a family has health insurance. Expenses such as deductibles, non-covered treatments, medicines and travel for medical care can create additional financial pressure.
3. Managing Unexpected Household Expenses
Home repairs, electrical problems, plumbing issues and essential appliance replacements can require immediate spending. An emergency fund helps manage these costs without affecting regular savings.
4. Avoiding High-Interest Debt
Without emergency savings, people may rely on credit cards or personal loans to manage unexpected expenses. Having readily available funds can reduce the need for expensive borrowing.
5. Maintaining Financial Independence
An emergency fund gives individuals greater control over their financial decisions. It allows them to manage difficult situations without immediately depending on friends, relatives or external borrowing.
How Much Money Should You Keep in an Emergency Fund?
The ideal emergency fund depends on household expenses, income stability, family responsibilities and existing financial commitments.
A commonly used financial planning guideline is to maintain savings equivalent to three to six months of essential living expenses.
For households with irregular income, multiple dependants, significant loan obligations or limited job security, a larger reserve may be more appropriate.
Emergency Fund?
An emergency fund should be easily accessible, relatively safe and separate from money reserved for long-term investments.
Some suitable options include:
1. Savings Account
A savings account offers easy access to money through digital banking, ATMs and online transfers. It is a convenient place to keep a portion of emergency savings.
2. Fixed Deposits
Bank fixed deposits can offer relatively predictable returns. However, consider premature withdrawal conditions and penalties before using them for emergency savings.
3. Sweep-In Fixed Deposits
Some banks offer sweep-in facilities that automatically transfer money between a savings account and linked fixed deposits when needed. This can help balance liquidity and interest earnings.
4. Liquid Mutual Funds
Liquid mutual funds invest primarily in short-term debt and money market instruments. They may be considered for a portion of emergency savings, but they are not guaranteed-return products and involve market and credit risks. Redemption timelines and applicable risks should be understood before investing.
A practical approach is to keep some money immediately accessible in a savings account and place the remaining reserve in suitable liquid and low-risk options.
How to Build an Emergency Fund Step by Step
Creating an emergency fund may seem difficult initially, particularly for households managing multiple financial responsibilities. However, consistent saving can make the process easier.
Step 1: Calculate Your Essential Monthly Expenses
Start by identifying necessary expenses, including housing, food, electricity, transportation, insurance and loan payments.
Step 2: Set a Realistic Savings Target
Choose an initial target, such as one month's essential expenses. Gradually work towards building a reserve covering three to six months.
Step 3: Start Saving Every Month
Set aside a fixed amount from your monthly income. Even small contributions can help build a financial reserve over time.
Step 4: Automate Your Savings
Set up an automatic transfer to a separate savings account immediately after receiving your salary. This encourages consistency and reduces unnecessary spending.
Step 5: Use Additional Income Wisely
Bonuses, incentives, tax refunds and other unexpected income can help accelerate emergency fund creation.
Step 6: Review Your Emergency Fund Regularly
Household expenses and financial responsibilities change over time. Review your savings target whenever your income, family size or monthly commitments change.
Common Mistakes to Avoid While Building an Emergency Fund
Although saving money is important, certain mistakes can reduce the effectiveness of an emergency fund.
Investing all emergency savings in risky assets: Equity investments and volatile assets may lose value when money is urgently required.
Keeping insufficient savings: A very small reserve may not provide enough protection during an extended income disruption.
Using emergency money for unnecessary purchases: Holidays, shopping and lifestyle upgrades should be funded separately.
Ignoring inflation: As household expenses increase, the emergency fund should also be reviewed and adjusted.
Not replenishing withdrawals: If you use emergency savings, make rebuilding the fund a financial priority once the situation stabilises.
Depending entirely on insurance: Insurance is important, but it may not cover every expense or provide immediate cash for all emergencies.
Why Emergency Funds Are Important for Financial Independence
Financial independence is not only about earning more or building investments. It also involves being prepared for unexpected situations.
A well-maintained emergency fund can protect long-term investments from premature withdrawals during difficult financial periods. It can also reduce financial stress and provide greater flexibility when making important life decisions.
For young professionals, families, self-employed individuals and retirees, having an accessible financial reserve can make a significant difference in managing uncertainty.
Conclusion
An emergency fund is one of the foundations of responsible financial planning. It provides households with a safety net against unexpected expenses, income disruptions and financial uncertainties.
Building this reserve does not require a large income or significant savings from the beginning. What matters most is setting a realistic target, saving consistently and keeping the money accessible for genuine emergencies.
In 2026, financial security is not just about growing wealth but also about protecting what you have already earned. An emergency fund may not generate extraordinary returns, but its real value lies in the financial confidence and stability it provides when life takes an unexpected turn.
Remember: A strong financial future begins not only with investing for tomorrow but also with preparing for the unexpected today.