Financial Resilience: How to Protect and Preserve Your Wealth in Uncertain Times
Building wealth is an important financial goal, but protecting it is equally essential. Economic uncertainty, rising living costs, unexpected expenses and changing market conditions can affect even carefully planned finances. This makes financial resilience an important part of long-term wealth management.
Financial resilience is the ability to manage financial challenges while maintaining stability and working towards future goals. It involves preparing for unexpected situations, managing risks and making informed financial decisions.
Build a Strong Emergency Fund
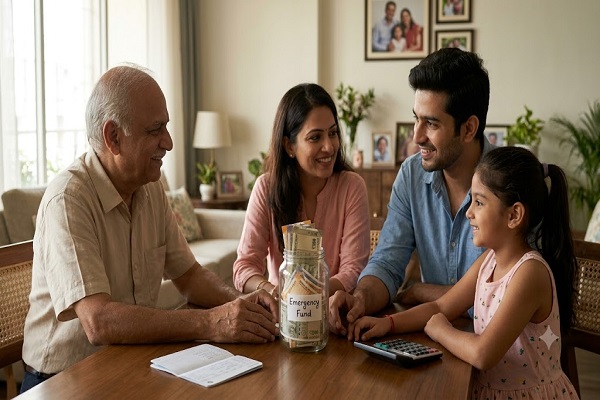
An emergency fund provides financial protection against unexpected situations such as medical expenses, temporary unemployment or urgent household repairs.
Financial experts commonly recommend keeping three to six months of essential living expenses in an easily accessible savings account or other suitable liquid instruments. Having this reserve can reduce dependence on high-interest loans and prevent individuals from selling long-term investments during difficult periods.
Diversify Your Investments
Depending entirely on one investment category can expose investors to unnecessary financial risks. Diversification involves spreading investments across different asset classes, such as equities, fixed-income instruments, gold and real estate.
Different assets may respond differently to economic conditions. A diversified portfolio can help manage overall investment risk, although it cannot eliminate the possibility of losses.
Manage Debt Responsibly
Debt management plays an important role in preserving wealth. High-interest borrowing, particularly through credit cards and unsecured personal loans, can create financial pressure and reduce the ability to save or invest.
Prioritising expensive debt repayment, maintaining a manageable borrowing level and making timely payments can strengthen financial stability.
Protect Your Wealth Through Insurance
Insurance is an important financial risk-management tool. Health insurance can help manage unexpected medical costs, while suitable life insurance can provide financial protection for dependants.
Choosing coverage based on personal circumstances, existing financial responsibilities and potential risks can help prevent unexpected events from disrupting long-term financial plans.
Adjust Financial Plans During Economic Changes
Inflation, interest rate movements and market volatility can influence purchasing power and investment returns. Reviewing financial goals periodically allows investors to assess whether their existing strategies remain suitable.
Rather than reacting emotionally to short-term market movements, investors should focus on their investment horizon, financial objectives and risk tolerance.
Develop Long-Term Financial Discipline
Preserving wealth requires consistent financial habits. Regular savings, controlled spending, proper budgeting and periodic portfolio reviews can help individuals remain prepared for changing circumstances.
Financial knowledge is equally important. Understanding taxation, investment risks and financial products enables people to make better decisions and avoid unrealistic return promises.
Conclusion
Financial resilience is about more than accumulating money. It is about protecting financial resources, preparing for uncertainty and maintaining stability through changing economic conditions.
Building an emergency fund, diversifying investments, managing debt and maintaining appropriate insurance coverage can create a stronger financial foundation. Ultimately, sustainable wealth management depends not only on how much wealth is created but also on how effectively it is protected.