Economics : RBI- growth comfort provides room to fight inflation by Elara Capital
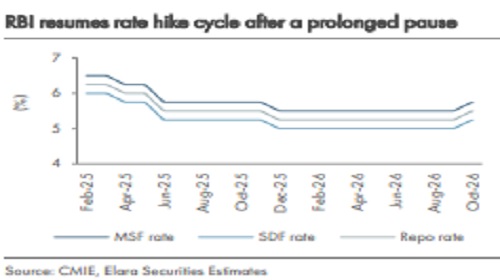
The RBI ’s Monetary Policy Committee (MPC) raised the policy repo rate by 25bp to 5.5%, in line with our expectations, amid broadening inflation risks . The decision was supported by resilient domestic growth, hawkish global DM central banks , and a challenging geopolitical backdrop. The MPC also changed its monetary policy stance to “calibrated tightening ” from neutral , with a 4-2 majority vote , marking a turn in the interest rates cycle . We expect the RBI to deliver another 25bp hike in December 2026 and see a higher probability of another 25 bp hike in Feb -27 as strong growth allows pass -through of higher producer prices to consumers. Inflation risks continue to build , while growth risks remain broadly contained , and DM central banks appear set to maintain a hawkish policy path.
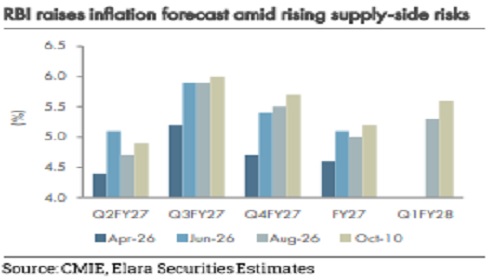
Broadening and rising inflation risks: Governor Sanjay Malhotra acknowledged price pressures are increasingly extending beyond food and fuel. The RBI projected core inflation at 4.4% v s 4.3% earlier and headline CPI at 5.2% ( our estimates: 5.1%) vs 5 .0% earlier with H 2FY27 at an averag e of near 6 .0%. Domestic demand and credit growth remain resilient for faster pass through of elevated input cost , providing the RBI room to prioriti ze inflation management. T herefore , we expect the policy stance to remain focused on ensuring food, energy , and imported cost pressures do not generate a more persistent rise in underlying inflation.
Food inflation remains particularly vulnerable to weather conditions. Cumulative Monsoon rainfall was ~ 12-13% below average as on September -end, increasing uncertainty around agricultural output and food prices. At the same time, firms are facing renewed cost pressures from supply chain disruptions, energy, freight , and industrial commodities. T he indirect effects through transportation, manufacturing , and services cost is likely to become progressively important. Therefore, t he risk is tilted to the upside for second -round transmission into underlying inflation expectations and corporate pricing behaviour.
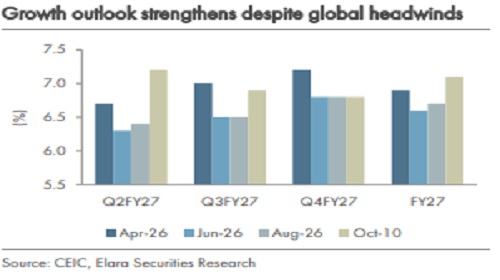
Resilient growth provides opportunity to prioritize inflation: Domestic activity remains supportive, allowing the MPC to act pre -emptively on inflation without materially jeopardi zing the growth outlook. Resilient household demand, continued investment activity, strong services momentum, and robust credit growth should keep underlying economic activity firm. The RBI has revised FY27E real GDP growth to 7.1% vs 6.7% earlier (vs. our estimate of 7.1%) . Consequently, we do not view a cumulative 50 -75bp tightening cycle as adequately restrictive to derail the growth trajectory.
However, downside risks to growth exist in the sidelines. Prolonged geopolitical conflict could simultaneously raise supply chain bottlenecks, input cost , and weaken external demand, while deficient rainfall could weigh on agricultural output and rural purchasing power. Therefore, beyond the December hike, we expect the RBI to become increasingly data -dependent, balancing inflation persistence against lagged transmission of tighter financial conditions .
Outlook: Another 25bp hike in December remains our base case , but the probability of another 25bp hike (75bp total including today’s) has gone up substantially . The principal drivers of our call are: 1) headline inflation is moving higher while growth risks have softened ,2) core inflation uptrend suggests price pressures are broadening , 3) deficient rainfall raises food inflation risks , 4) elevated crude, commodity , and freight cost is increasingly being passed through by firms , 5) resilient domestic demand to accelerate price pass through in the festiv al season , and 6) renewed tightening by the Fed, the BoJ , and other central banks limits the RBI's policy flexibility. A combination of upside inflation risks and the RBI’s intent to contain it is negative for India ’s benchmark government bond yields. Given the global bond market sell -off and India’s domestic factors, we do not rule out 7. 4-7.5%+ 10Y bond yields in the up coming months.
Above views are of the author and not of the website kindly read disclaimer