Comparison of RBI Monetary Policy Statement by Namrata Mittal, CFA, Chief Economist, SBI Funds Management Limited
|
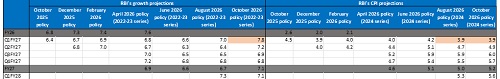
The October policy marks a decisive shift in the RBI’s reaction function. The MPC unanimously (6:0) delivered a 25 bps hike, lifting the repo rate to 5.50%, and formally shifted the stance to calibrated tightening. Two members - Dr. Nagesh Kumar and Prof. Ram Singh - were of the view that the stance be retained at neutral. Unlike earlier policies where the RBI emphasised patience and tolerance for supply-driven inflation, today’s communication leaves little ambiguity: rate cuts are off the table, and every meeting ahead is now a live one for further tightening. Why the backdrop matters? There has been a decisive turn in both global and domestic inflation narratives since the August policy. And after months of intense debate, shifting expectations and mixed signalling, the US has finally entered a hiking phase of its own, with markets pricing three further moves over the next year. In India too, the shift in tone was evident. The RBI’s messaging in the August policy looked distinctly dovish, but the minutes released a fortnight later carried a sharper and more cautionary flavour. Global dynamics have hardened The macro backdrop has changed materially. The sudden re-escalation of the West Asia conflict in September and a sharp rise in crude (Indian basket at USD 116/bbl in September versus USD 82/bbl in July) have hardened global financial conditions. Inflation abroad has picked up, central banks remain hawkish, and global yields have repriced higher. India continues to benefit from strong domestic fundamentals, yet the global headwinds are now too large to ignore. We had always believed that a rate hike in India was inevitable. Historically, India has never witnessed petrol and diesel price revisions of this magnitude without a follow through hiking cycle. Yet the Governor’s remarkably dovish August communication made us reassess the timing, prompting us to push back our expectation to December 2026 or even February 2027. However, as the global landscape turned materially more hawkish through September, and given the hardening in crude, global yields and policy stances elsewhere, we — like the broader market — were fully convinced of an October hike well before today’s policy announcement. The volatility of global expectations The last few weeks have also underscored the sheer volatility of global dynamics. For instance, US labour market data released just last week abruptly lowered the implied probability of an October FOMC hike from 70–80% to around 20%. A growing cohort of global experts now argues that the Fed’s window to tighten further may be extremely narrow, potentially limited to early 2027. This oscillation in global expectations is a timely reminder that policy paths everywhere are far less linear than they appear. Domestic growth momentum and resilience Now coming back to current Indian dynamics, domestic momentum remains firm. Q1 FY27 growth printed at 7.8% and high-frequency indicators through Q2 show resilience in consumption, services, investment and exports. Manufacturing and services PMIs remain comfortably in expansion, capex indicators are healthy, and discretionary demand has held up. However, weak monsoon performance, strong El Niño, elevated import bills present emerging risks. The Governor revised the FY27 growth projection to 7.1% (bang in line with our expectation), explicitly highlighting a 40 bps upgrade despite substantial global turbulence, a signal that growth resilience gives the RBI room to tighten without materially endangering the recovery. An inflation profile that is no longer benign Headline CPI is expected to average almost 5.8% for the next three quarters, materially above past expectations. Core inflation has picked up to 4.2%, early signs of generalisation have appeared, and diffusion indices reflect a broader share of items printing above 4%. Food-price spikes in sugar and onions, stronger fuel inflation (5.2%), and pervasively higher input costs have altered the near-term trajectory. Against this backdrop, the central bank is no longer comfortable relying on transient supply corrections. Its willingness to “watch” in August has been replaced by the need to “recalibrate” policy today. Our own projection for FY27 CPI is 5.4%, slightly higher than the RBI’s 5.2%, reflecting persistent food risks. RBI’s growth and inflation projections across different monetary policy
Source: RBI MPC statement; NB: Coloured value highlights the actuals
Liquidity remains the transmission challenge The liquidity backdrop remains pivotal. Surplus liquidity surged to Rs. 5.9 trillion on account of FX inflows and recent dollar mobilisation measures. The WACR has traded materially below the repo rate, blunting monetary transmission at a time when calibrated tightening demands firmer short term rates. Thus, the alignment of the WACR with the repo rate is warranted. In our view, liquidity withdrawal will continue through VRRRs, OMO sales and potentially FX swaps. The liquidity overhang will need to be neutralised for the stance change to be meaningful. At the post-policy press conference, the Governor indicated that sell-buy swaps and spot intervention to support the rupee will drain the surplus within the current financial year. An expected Rs. 3–4 trillion rise in currency in circulation (CIC) leakage will add to the drain, so the surplus is unlikely to stay this high for long. A CRR increase has not been ruled out, but it remains the least preferred tool for absorbing liquidity. The difference between domestic borrowing costs and global dollar funding costs has widened to around 150–160 bps, encouraging onshore borrowing for offshore use — effectively exporting capital. This raises medium-term macro-stability considerations and strengthens the case for higher domestic rates. Twin inflation risks for India In India, the inflation outlook presents two key concerns. First, the cost of crude imported into India is hovering around USD 120/bbl. This impact has been largely absorbed by oil marketing companies and partly offset through excise duty cuts, keeping the passthrough to consumers deliberately modest. This shielding has been central in anchoring core inflation. India’s core inflation has historically shown a strong correlation with domestic transportation costs, which explains why core inflation expectations remain remarkably stable at 4.4% for FY27 (vs. 4.3% earlier) even as food inflation is likely to run into double digits. Given upcoming state elections, especially in Uttar Pradesh, further retail price passthrough at current Brent levels will likely remain nominal. But should Brent rise meaningfully from here, all these equations will need urgent reassessment. Conversely, a shift in global geopolitics or oil dynamics could just as easily neutralise energy risks. Second, food inflation poses a more pronounced risk. Government communications indicate that this may be one of the worst drought episodes in recent history, with reservoir levels declining rapidly across major basins. As a result, food inflation could remain elevated through the first half of 2027 — our estimates suggest 10–12%. Government responsiveness in managing food supply chains, import pipelines and stock buffers will be critical to containing broader price drift. Policy path ahead: the case for further tightening Against this evolving backdrop, we continue to expect a cumulative 75 bps of hikes through this cycle (one each in next two policies) taking the repo rate to 6.00%. The stance revision, the inflation trajectory (5.8% for the next three quarters), and the recalibration needed for forward-looking real rates all support this view. Rate hikes of 75 bps would finally lift real rates into slightly positive territory, aligning domestic conditions with global real-rate repricing and strengthening capital flow dynamics. But a significant disclaimer is warranted: the environment is exceptionally fluid. Today, market expectations may appear at the hawkish extreme, and justifiably so, but given the pace at which global conditions are shifting, it is essential to stay nimble and open ended in our forward expectations. Market reaction and curve dynamics Markets have quickly aligned with this new reality. Bond yields hardened post policy, while the rupee remained broadly stable. Offshore traders are unlikely to materially alter their FX positioning based on a single 25 bps hike, but the Governor’s communication sets the foundation for a stronger rupee defence in the coming months. Equity markets have reacted positively, reflecting the favourable impact of higher rates on bank margins and the absence of liquidity-disruptive measures like CRR hikes.
Above views are of the author and not of the website kindly read disclaimer |