OMCs Lead Earnings Recovery as Refining Margins Stay Elevated, While CGDs Face Margin Pressure: PL Capital
Aggregate Q2FY27 EBITDA is expected to improve 41.2% QoQ to INR 973.9 billion, led by OMCs and a resilient upstream, while PL Capital remains Overweight on the sector with MGL and IGL as preferred CGD picks
PL Capital’s research team, in its latest Jul-Sep’26 earnings preview for the Indian oil and gas sector, expects a sequential recovery in earnings in Q2FY27, led by oil marketing companies (OMCs) and a resilient upstream segment, while city gas distribution (CGD) companies are likely to remain under pressure from higher LNG costs.
The report expects aggregate sales for the coverage universe to grow 4.1% QoQ and 39.4% YoY to INR 10,541.1 billion in Q2FY27. EBITDA and PAT are estimated at INR 973.9 billion and INR 457.3 billion, respectively, reflecting a decline of 5.6% and 11.1% YoY, but an improvement of 41.2% and 51.9% QoQ. PL Capital maintains an Overweight rating on the sector.
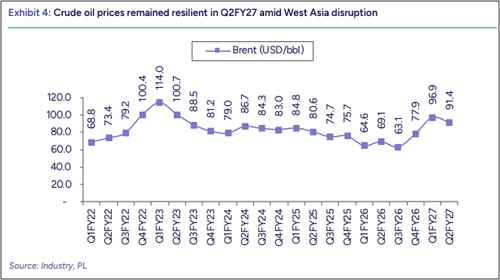
Crude prices rebound sharply on renewed US-Iran tensions
Brent crude averaged US$86.0 per barrel in July-August 2026, but renewed conflict between the US and Iran and fading prospects of peace talks triggered a sharp rally in September, with Brent peaking at US$108.8 per barrel. This took the Q2FY27 average to US$91.4 per barrel, compared with US$96.9 per barrel in Q1FY27. PL Capital believes the higher crude price environment should continue to support the upstream earnings of ONGC and Oil India, although performance is likely to moderate sequentially. ONGC’s EBITDA is estimated at INR 260.2 billion in Q2FY27, against INR 294.5 billion in Q1FY27.
Elevated refining cracks support OMC recovery
Global refining margins remained elevated in Q2FY27, supported by tight product balances and persistent supply constraints. Post-SAED cracks for MS, HSD and ATF averaged US$31.4/38.7/40.9 per barrel, compared with US$31.6/20.4/38.7 per barrel in Q1FY27. Supported by stronger product cracks and softer crude prices QoQ, the report estimates GRMs of US$20.8/19.2/15.4/11.2 per barrel for IOCL, BPCL, HPCL and MRPL, respectively. Marketing margins are expected to remain under pressure, albeit with a sequential improvement, as losses narrow to INR 3.5/3.6/3.6 per litre for IOCL, BPCL and HPCL, from INR 12.8/16.3/14.9 per litre in Q1FY27.
Consequently, PL Capital expects IOCL and BPCL to report EBITDA of INR 94.0 billion and INR 21.3 billion, respectively, compared with INR 20.2 billion and an EBITDA loss of INR 40.8 billion in Q1FY27, while HPCL is likely to report an EBITDA loss of INR 20.9 billion. MRPL’s EBITDA is estimated to improve to INR 23.3 billion from INR 13.2 billion QoQ. LPG under-recoveries are expected to remain high, but lower than in the previous quarter.
CGDs under pressure as higher LNG costs weigh on margins
CGD volumes are expected to remain resilient, with Qatar LNG supply shortfalls largely offset by alternative supplies from the US, Nigeria, Oman and Mexico. However, spot LNG prices increased to US$22.1/MMBtu in Q2FY27 from US$17.7/MMBtu in Q1FY27, driven by prolonged disruption to LNG flows through the Strait of Hormuz, aggressive European restocking and increased spot buying from Asia. Higher gas costs, coupled with declining domestic APM gas availability, are expected to more than offset the benefit of price hikes taken by CGDs. EBITDA per scm is estimated to decline to INR 2.4/7.0/4.5 for IGL, MGL and Gujarat Energy, respectively, from INR 3.4/7.9/5.2 in Q1FY27, even as IGL and MGL volumes are expected to grow 2.1% and 1.9% QoQ, respectively.
Gas utilities and Reliance Industries
GAIL is expected to report transmission volumes of ~126 mmscmd in Q2FY27, compared with 122.4 mmscmd in Q1FY27, while EBITDA is estimated to moderate to INR 46.7 billion from INR 63.8 billion, primarily reflecting normalisation in the trading business. Petronet LNG’s utilisation is expected to improve to ~62% from 60%, with total regasification volumes rising to 215 TBtu from 207 TBtu and EBITDA estimated at ~INR 14.5 billion, compared with INR 15.3 billion in Q1FY27. For Reliance Industries, consolidated EBITDA is expected to grow 3.4% QoQ to INR 491.4 billion, with standalone EBITDA broadly flat QoQ at INR 195.4 billion.
PL Capital has raised its FY28E EPS estimates for ONGC and Oil India on higher crude oil realizations and revised its FY27E EPS estimates for OMCs upwards, while cutting FY28E EPS estimates for MGL and IGL by ~1-4%. Given the improvement in refining performance, PL Capital has upgraded BPCL to Accumulate from Hold and HPCL to Hold from Reduce. MGL and IGL remain its preferred CGD picks, supported by strong CNG and PNG volume growth, which is expected to accelerate as gas supply constraints normalise and the impact of price hikes is captured fully.
Above views are of the author and not of the website kindly read disclaimer