Diwali Picks 2026 : Tata Power Company Ltd for the Target Rs.421 by Axis Securities Ltd
Renewables-Led Growth and Improving Business Mix to Drive Earnings Expansion
Tata Power is transitioning from a conventional power utility into an integrated energy platform, spanning generation, renewables, transmission, distribution, solar manufacturing and emerging clean-energy solutions. Its diversified operating model combines the earnings stability of regulated businesses with structural growth opportunities arising from India’s rising electricity demand and energy transition. Expanding renewable capacity, improving distribution profitability and scaling solar manufacturing are expected to strengthen earnings visibility. While the transition requires substantial capital investment, a favourable business mix provides a foundation for sustained medium-term earnings growth.
Renewable Capacity Expansion and Solar Manufacturing to Drive Growth: Tata Power commissioned approximately 2.5 GW of renewable capacity in FY26, taking its renewable portfolio to 11.6 GW, including 5.1 GW under construction. The renewables business delivered 59% YoY PAT growth in FY26, reflecting improving scale and operating leverage. Solar manufacturing contributed Rs. 857 crore in PAT, supported by module production of 3,825 MW and cell production of 3,759 MW. Rooftop solar installations reached 1.7 GWp during FY26, taking cumulative installations beyond 4.8 GWp. Further capacity additions, improved manufacturing utilisation, backward integration and rising rooftop adoption should support growth.
Regulated Businesses Provide Stability and Strengthen Cash-Flow Visibility: The transmission and distribution business reported 49% PAT growth to Rs. 2,978 crore in FY26, while Odisha DISCOMs recorded PAT of Rs. 809 crore, up 84% YoY. These businesses provide relatively predictable earnings and cash flows, complementing the higher-growth renewable and manufacturing segments. Continued improvements in operational efficiency, collection performance and distribution economics should strengthen earnings quality and support funding requirements for the company’s expansion programme.
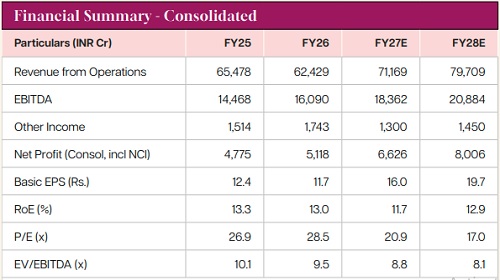
Favourable Business Mix to Support Earnings Outperformance: Revenue is projected to grow at a 13.0% CAGR over FY26–FY28E, while PAT is expected to compound at approximately 25%. Earnings growth is likely to outpace revenue expansion, supported by operating leverage, renewable capacity commissioning, solar manufacturing scale-up, rooftop solar growth and improving profitability across regulated operations. Pumped-hydro storage and nuclear power provide additional long-term opportunities. However, these initiatives remain subject to regulatory approvals, project execution and commercial viability
Capital Allocation and Leverage Remain Key Monitorables: Planned capital expenditure of Rs. 25,000 crore in FY27 and Rs. 27,000 crore in FY28 underscores the investment intensity of Tata Power’s growth strategy. Net debt is expected to increase from Rs. 46,600 crore in FY26 to Rs. 62,600 crore in FY28E. Timely commissioning, capacity utilisation and operating cash-flow generation will therefore remain critical to managing leverage and protecting balance-sheet flexibility.
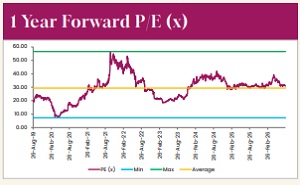
Valuation and Outlook: We maintain a BUY rating on Tata Power with a target price of Rs. 421, based on our blended P/E and EV/EBITDA valuation approach. We estimate PAT to grow at a CAGR of 25% over FY26–FY28E, supported by renewable capacity additions, a higher contribution from solar manufacturing and stable regulated earnings. The ramp-up of new capacities should drive earnings growth, while the shift towards renewables and manufacturing strengthens the company’s long-term growth profile. Although elevated capex and rising leverage remain key monitorables, we expect improving asset utilisation and cash-flow generation to support the next phase of growth. At our target price, we see scope for value creation as capacity expansion translates into earnings growth and a stronger business mix. Timely execution and returns on invested capital will be key to sustaining this upside.
For More Axis Securities Disclaimer https://simplehai.axisdirect.in/disclaimer-home
SEBI Registration number is INZ000161633