Diwali Picks 2026 : Glenmark Pharmaceuticals Ltd for the Target Rs.2,897 by Axis Securities Ltd

Advancing Global Healthcare Through Innovation
Glenmark Pharmaceuticals Ltd. is a research-led pharmaceutical company with presence across 80+ countries, supported by 11 manufacturing facilities and six R&D centres. Its portfolio spans branded, innovative and generic medicines, with key focus areas including respiratory, dermatology and oncology. RYALTRIS®, WINLEVI® and oncology assets remain important growth drivers, while the IGI pipeline adds innovation-led opportunities. The AbbVie licensing agreement for ISB 2001, comprising a US$700 million upfront payment and potential deal value of US$1.925 billion, strengthens Glenmark’s specialty profile. Its diversified geographic footprint, commercial infrastructure and increasing focus on differentiated therapies are expected to improve business mix and earnings quality.
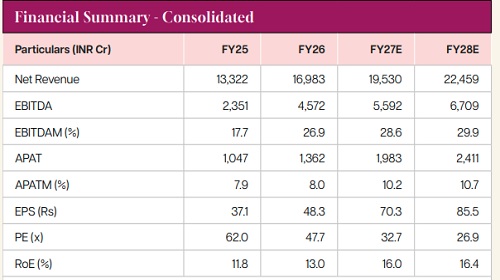
Strong Financial Performance: Delivered growth in FY26, with consolidated revenue rising 27.5% YoY to Rs. 16,983 crore. EBITDA stood at Rs. 4,572 crore, translating into a 26.9% margin, while adjusted PAT reached Rs. 1,362 crore. Momentum continued in Q1FY27, with revenue increasing 23.1% YoY to Rs. 4,019 crore, EBITDA growing 38.6% to Rs. 805 crore and PAT reaching Rs. 483 crore. Performance was broad-based, with India, North America, Europe and Emerging Markets advancing 15.5%, 41.1%, 11.9% and 27.7%, respectively. Improving operating leverage, product traction and specialty contribution are expected to reinforce profitability, supporting further revenue and earnings progression.
Specialty Portfolio & New Launches Drive Growth: A specialty-led strategy offers a platform for expansion across respiratory, dermatology and oncology. RYALTRIS® remains a key growth driver, supported by wider geographic reach and increasing penetration, while upcoming respiratory and oncology launches can broaden the franchise. Trastuzumab Rezetecan and Aumolertinib are strengthening the oncology pipeline alongside proprietary IGI assets. India is expected to sustain healthy growth through core therapies and new products, with differentiated medicines likely to enhance business quality. Portfolio optimisation, specialty launches and penetration are expected to protect margins and create a runway for future earnings.
US Opportunity & Pipeline Monetisation Enhance Visibility: International opportunity is underpinned by its US respiratory franchise, niche launches and pipeline commercialisation. FY27 US growth is expected to remain robust, aided by new products and regulatory approvals, while RYALTRIS® offers additional potential across overseas markets. The ISB 2001 agreement with AbbVie provides upfront economics and strengthens validation of Glenmark’s innovation capabilities. Further IGI assets could generate licensing opportunities, while expansion across Europe and Emerging Markets through respiratory, dermatology and oncology offerings broadens the addressable opportunity. Higher product penetration and pipeline monetisation are expected to diversify revenue streams, improve visibility and support a healthy earnings trajectory
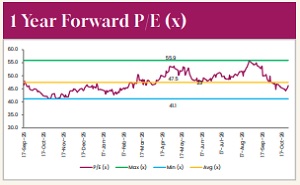
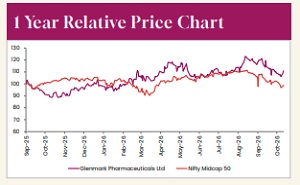
Outlook & Valuation: Specialty medicines, an established respiratory franchise, international reach and an innovation pipeline create avenues for expansion. RYALTRIS®, WINLEVI®, oncology assets and the AbbVie partnership are expected to lift the contribution from differentiated therapies, while new approvals can broaden the product base. We expect earnings growth to be supported by specialty expansion, overseas momentum and a better business mix. Greater contribution from higher-value therapies, product traction and potential IGI monetisation should reinforce earnings visibility. Accordingly, we initiate a coverage with a BUY rating and a target price of Rs. 2,897, based on 33.9x FY28E earnings, reflecting Glenmark’s specialty portfolio, innovation capabilities and growth opportunity
For More Axis Securities Disclaimer https://simplehai.axisdirect.in/disclaimer-home
SEBI Registration number is INZ000161633