Convex Choices Equity Strategy and High-Conviction Ideas Quarterly Q2FY27 by Choice Institutional Equities
The Macro Equation: Relief Meets Resistance
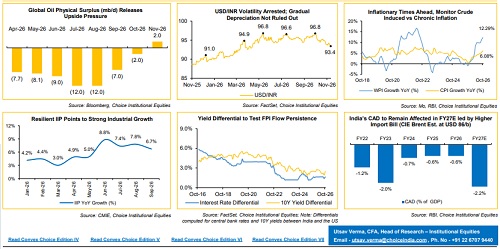
In our previous edition (read here), we identified three prerequisites for a sustained recovery in foreign portfolio flows, thus leading the way out from sub-optimal market returns: i) meaningful earnings upgrades, ii) INR stability and iii) favourable policy treatment for foreign capital. We also highlighted a potential rotation away from crowded global AI-led trades as an additional tailwind. Since then, the macro equation has begun to shift. Improving crude supply conditions and prospects of INR stabilisation could ease imported inflation, current account pressures and corporate input costs. Domestic growth has remained resilient, with September industrial production expanding 6.7% YoY and capital goods output rising 15% in H1FY27. The challenges, however, remain significant. October CPI climbed to 6.1%, breaching the RBI's tolerance band, while WPI reached 12.3%, signalling persistent cost pressures.
The fiscal deficit widened 24.7% YoY to INR 7.14 Tn in H1FY27, as revenue receipts grew only 3.6% against expenditure growth of 10.7%.
Market View
India's macro risks are becoming more manageable, even if headline indicators have yet to improve. Easing external pressures could create room to address domestic inflation and fiscal challenges through calibrated monetary policy, supply-side interventions and expenditure discipline, while resilient industrial activity provides a growth cushion. Crucially, a stabilising macro backdrop could help deliver the second pillar of our foreign-flow recovery thesis—INR stability—while sustained earnings upgrades and policy support remain essential. The opportunity is a transition from externally driven vulnerability towards greater domestic policy control, improving earnings visibility and a more constructive risk-reward for Indian equities. Our preference remains for fundamentally strong companies backed by structural policy support, favourable industry dynamics and visible earning upgrades.
High Conviction Portfolio Performance: Our equal-weighted Flexi Cap quarterly rebalancing strategy has delivered 60.4% since inception (March 2025) — reinforcing our preference for disciplined stock selection over broad market beta. Refer to page 5 and 6 for details.
Foreign Flows: The Return Of India's Relative Appeal
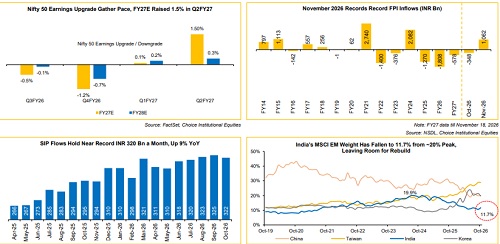
After nearly two years of sustained selling, foreign capital is returning to Indian equities. FPI flows deteriorated from a INR 376 Bn outflow in FY23 to INR 1,270 Bn of outflows in FY25, followed by INR 1,640 Bn of selling during April–October 2026. November has delivered a sharp reversal, with INR 1,062 Bn of inflows through November 18, reducing FY27 net outflows to approximately INR 578 Bn.
The earnings recovery is also gathering momentum. Nifty 50 (ex-financials) companies reported 27.6% YoY profit growth in Q2FY27, the strongest in 17 quarters, while broader corporate earnings grew 32% against expectations of 21%. Overall earnings upgrades outpaced downgrades; lifting Nifty EPS estimates by 1.5% for FY27E and 0.3% for FY28E. This marks an important shift from earnings resilience to actual upgrades.
Meanwhile, as investors reassess crowded global AI exposures, India offers DIVERSIFICATION THROUGH DEEP EQUITY-MARKET LIQUIDITY, IMPROVING EARNINGS PROSPECTS AND POTENTIAL INR STABILITY. The November MSCI review reinforces this positioning, with India's Emerging Markets IMI Index weight set to increase from 12.9% to 13.2%. On the other hand, India weight in MSCI EM Index declined from nearly 20% in 2024 to around 11.7% in October, 2026. We expect an upward revision soon.
Our View: Renewed FPI inflows, earnings upgrades and improving benchmark representation suggest that India's investment appeal is recovering. Of the three catalysts identified in our previous edition, earnings upgrades are materialising and prospects of INR stability are improving, while favourable policy treatment for foreign capital remains important. A rotation away from AI-led trades could provide an additional tailwind, strengthening the case for a sustained recovery in foreign allocations.
Valuation Discount Narrows, Earnings and Stock Selection Take Centre Stage
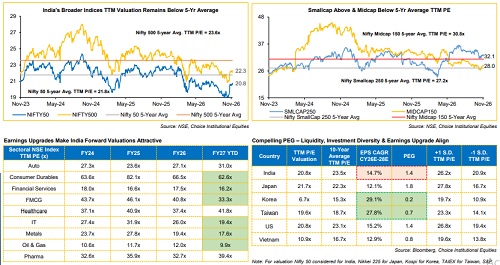
The valuation equation for Indian equities is turning favourable. After significant underperformance relative to AI-led markets, the recent reversal in the global AI trade has rapidly narrowed India's relative valuation disadvantage, although the adjustment remains incomplete. India’s Nifty 50 TTM P/E had declined to below 20x in October, from a peak of nearly ~24.4x in 2024. This compares with 13.7x for MSCI Emerging Markets and 19.6x for Taiwan’s TAIEX at the October reference point, indicating that India continues to command a substantial premium. The recent recovery in Indian equities, alongside improving earnings expectations, has reduced the valuation opportunity available from the earlier correction. However, some scope for multiple expansion remains, particularly as foreign allocations recover and earnings upgrades strengthen. With Nifty 50 (ex-financials) profits growing 27.6% YoY in Q2FY27 and FY27E/FY28E EPS estimates revised upwards, earnings are increasingly providing fundamental support to valuations.
Our View: India's relative valuation gap has narrowed faster than anticipated, but the re-rating opportunity is not exhausted. The scope for further multiple expansion is diminishing, making earnings growth, valuation discipline and bottom-up stock selection the principal drivers of future returns. We strongly favour Pharmaceuticals, Banks, NBFCs, Industrials, Chemicals, Auto & Auto Anc and select Consumer Discretionary & New-Age Tech, focusing on companies with sustainable earnings upgrades, strong balance sheets and reasonable valuations. The next phase of market outperformance will be driven less by broad valuation catch-up and more by research-led stock picking.
Above views are of the author and not of the website kindly read disclaimer




Tag News
Gift Nifty Sets an All-Time High Open Interest of US $22.21 billion on 18, November 2026
More News
Quote on Market Closing Comment Nov 20, 2026 from Ajit Mishra, SVP ? Research, Religare Broking