Diwali Picks 2026 : Kotak Mahindra Bank Ltd for the Target Rs.518 by Axis Securities Ltd
Improving Growth and Operating Leverage to Drive Earnings Recovery
Kotak Mahindra Bank is a leading private sector lender with a diversified franchise spanning retail, SME and corporate banking, complemented by subsidiaries across insurance, asset management and other financial services. Its strong capitalisation, established customer franchise and prudent underwriting provide a solid foundation for sustainable balancesheet expansion. Following a period of growth moderation and margin pressures, improving advances momentum, disciplined cost management and scope for NIM recovery are expected to support an improvement in earnings growth over the medium term.
Advances Growth to Accelerate Across Key Lending Segments: Gross advances increased 23% YoY to Rs. 6.27 lakh crore in Q2FY27. Excluding loans against FCNR(B) deposits and the transferred KMIL loan portfolio, underlying advances grew 19% YoY, supported by SME, corporate and retail banking. Management targets advances growth of 1.5–2x nominal GDP growth, while maintaining underwriting discipline. Excluding FCNR(B) deposits, the deposit base grew 13% YoY, while CASA would have improved to 41.8% from 40.3% in Q1FY27. Progressive deployment of FCNR(B) liquidity and sustained traction across lending segments should support credit growth over the medium term.
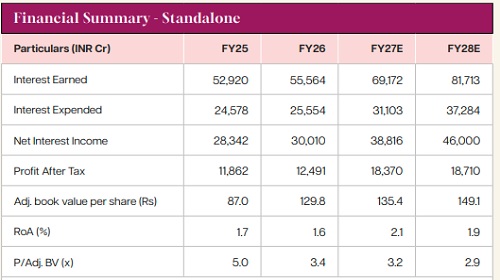
NIM Recovery Potential to Support Earnings Growth: NIM declined 22 bps QoQ to 4.31% in Q2FY27, with approximately 15 bps of the contraction attributable to FCNR(B) deposits and related advances. While the full-quarter impact may keep Q3 margins under pressure, gradual deployment of these funds into customer advances and repricing of floating-rate loans should support recovery. We expect further rate hikes to aid gradual NIM expansion, with margins estimated at 4.69% in FY27E and 4.94% in FY28E, supporting NII growth to Rs. 38,816 crore and Rs. 46,000 crore, respectively.
Operating Efficiency and Asset Quality to Support Profitability: The cost-to-income ratio improved to 45.2% in Q2FY27 from 46.8% a year earlier, reflecting disciplined expenditure management and operating efficiencies. Continued investments in technology, automation and customer acquisition should support productivity, while incremental revenue growth offers scope for operating leverage. Asset quality remains healthy, with GNPA and NNPA ratios at 1.04% and 0.24%, respectively, and credit costs at 0.35%. Strong capitalisation, with a capital adequacy ratio of 21.9%, further supports balance-sheet expansion without compromising underwriting standards.
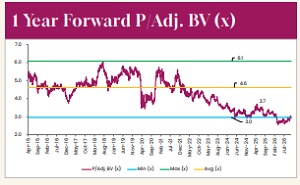
Valuation and Outlook: We maintain a Accumulate rating with a target price of Rs. 518. We estimate FY26–FY28E CAGRs of 23.8% in NII, 19.7% in PPoP and 22.4% in PAT, driven by advances growth, potential NIM recovery and operating leverage. The time-based price correction has resulted in a de-rating of the price-to-book multiple, improving the risk-reward profile. Given the bank’s strong capitalisation, healthy asset quality and improving earnings outlook, we see limited scope for further material de-rating. A gradual recovery in margins and sustained cost discipline should support earnings delivery over the medium term. Its scale and diversified revenue streams provide resilience across market cycles. Execution remains central to the thesis: converting liquidity into advances, sustaining deposit mobilisation and containing incremental operating costs will determine the pace of recovery. These factors underpin our constructive view despite margin volatility
For More Axis Securities Disclaimer https://simplehai.axisdirect.in/disclaimer-home
SEBI Registration number is INZ000161633