Diwali Picks 2026 : Indian Hotels Company Ltd for the Target Rs.990 by Axis Securities Ltd
Brand Strength, Asset-Light Growth and Hospitality Demand
The Indian Hotels Company Limited (IHCL) is one of India’s leading hospitality companies, with a diversified portfolio spanning luxury, upscale, midscale, boutique and wellness offerings. Its brands include Taj, Claridges Collection, SeleQtions, Vivanta, Gateway and Ginger, alongside experiential and wellness businesses such as Brij and Atmantan. The company also operates in air and institutional catering, providing additional revenue diversification. As of September 2026, its portfolio comprised 670 hotels, including 280 in the pipeline, across 15 countries and more than 300 locations. Its established brands and asset-light expansion model support growth across hospitality segments.
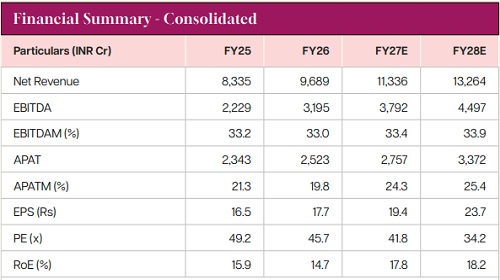
Financial Performance and Margins: IHCL reported FY26 revenue of Rs. 9,689 crore, up 16.2% YoY, EBITDA of Rs. 3,195 crore, up 15.3%, and adjusted PAT of Rs. 2,523 crore, up 7.7%, with EBITDA margin expanding to 33%. Growth was supported by higher RevPAR, catering, new businesses and management fees. In Q2FY27, consolidated revenue increased 21% YoY to Rs. 2,566 crore, EBITDA rose 21% to Rs. 788 crore, and PAT grew 23% to Rs. 349 crore. Standalone EBITDA margin expanded 400 bps to 38.9%, reflecting strong demand and operating leverage.
Asset-Light Expansion and Fee Income: The company continues to expand its hotel network through new signings and an asset-light growth strategy, enabling portfolio expansion without proportionate capital investment. It signed 47 hotels in H1FY27, taking its portfolio to 670 hotels, including a pipeline of 280 properties. Management fee income grew 25% YoY in Q2FY27, supported by new hotel openings. The expanding pipeline across brands and geographies is expected to strengthen recurring fee income, improve capital efficiency and support long-term growth. Timely project execution, hotel openings and the ability to maintain brand standards remain key monitorable factors.
Growth Drivers and Guidance: Management upgraded FY27 consolidated revenue growth guidance to 15-17% from 12-14%, while hotel segment revenue growth is expected at 17-19%. Growth is expected to be supported by demand from social and MICE events, higher room rates, new hotel openings and contributions from recently acquired businesses. Domestic same-store hotels recorded 25% RevPAR growth in Q2FY27, while full-service same-store hotels delivered 28% growth on a standalone basis. The expanding portfolio and premium brand positioning provide further growth opportunities, although demand seasonality, operating cost inflation and execution risks remain important monitorables.
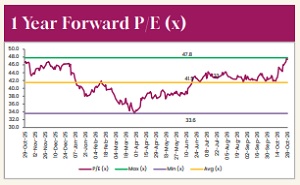
Outlook and Valuation: IHCL’s strong brand portfolio, sustained hospitality demand, expanding asset-light network and growing management fee income support its mediumterm growth prospects. The upgraded FY27 revenue guidance and healthy operating performance indicate sustained business momentum, while the proposed merger of Oriental Hotels Limited, effective April 1, 2027, is expected to simplify the group structure and strengthen growth opportunities. However, rising operating costs, potential moderation in room rates, seasonality and delays in hotel openings remain key risks. Accordingly, we initiate a coverage with a BUY rating and a target price of Rs. 990, based on 41.8x FY28E earnings, reflecting the company’s growth potential and earnings visibility.
For More Axis Securities Disclaimer https://simplehai.axisdirect.in/disclaimer-home
SEBI Registration number is INZ000161633