Diwali Picks 2026 : HCL Technologies Ltd for the Target Rs.1,680 by Axis Securities Ltd
AI-Led Growth, Strong Deal Pipeline and Improving Profitability
HCL Technologies Limited is a global technology company providing IT and business services, engineering and R&D services, and software products across multiple industries and geographies. Its portfolio spans digital transformation, cloud, cybersecurity, engineering, infrastructure management and enterprise software. The Services business remains its primary growth engine, supported by established client relationships and technology-led transformation capabilities. Investments in artificial intelligence, data centre infrastructure and strategic partnerships are expanding its addressable market. However, weakness in the software business and cautious enterprise spending remain near-term concerns. Its global delivery network and technical expertise support medium-term growth.
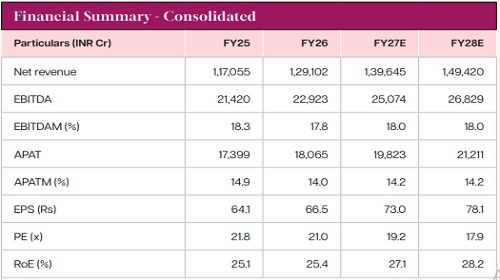
Improving Profitability and Strong Deal Bookings: HCLTech reported Q2FY27 revenue of Rs. 35,620 crore, up 11.5% YoY, while net income increased 21.2% to Rs. 5,132 crore. EBIT margin expanded 71 bps YoY to 18.2%, supported by operating efficiencies and higher-margin AI services. New deal bookings reached US$3.26 billion, up 27% YoY, while Advanced AI revenue grew 78% to US$219 million. Despite improving profitability and strong bookings, revenue growth remained moderate in constant-currency terms. Converting deal wins into sustained organic growth remains important for strengthening earnings visibility
Advanced AI and Strategic Partnerships Support Growth: The Advanced AI business is emerging as an important growth driver, with quarterly revenue reaching US$219 million, up 78% YoY. Its capabilities span enterprise transformation, intelligent automation, AI engineering and data centre infrastructure. Strategic partnerships, including its collaboration with Anthropic, support the development and deployment of agentic AI solutions. Investments in AI infrastructure and specialised engineering capabilities offer opportunities to capture rising enterprise technology spending. However, sustained monetisation, client adoption and potential AI-led pricing pressures remain key monitorable factors. Successful execution is expected to strengthen service differentiation and support higher-value revenue opportunities.
Services Momentum and Growth Visibility: The Services business continues to support growth, with IT and Business Services and Engineering and R&D Services recording positive YoY growth in Q2FY27. New deal bookings of US$3.26 billion provide a pipeline for future revenue conversion. Management raised the lower end of FY27 revenue growth guidance to 2.5%, retaining the range at 2.5-4.0% in constant-currency terms. Services revenue growth is expected at 3-4%, with EBIT margin guidance of 17.5-18.5%. Nevertheless, cautious client spending, geopolitical uncertainty and weakness in software products may constrain near-term growth.
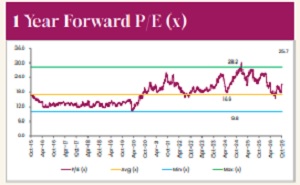
Outlook and Valuation: HCLTech’s strong deal pipeline, growing AI revenues, improving margins and diversified technology portfolio support medium-term growth prospects. However, moderate organic growth, cautious discretionary spending and potential AI-led pricing pressure may constrain near-term performance. Sustained deal conversion, software business recovery and AI monetisation are expected to strengthen earnings visibility. Accordingly, we initiate a coverage with a BUY rating and a target price of Rs. 1,680, based on 21.5x FY28E earnings, reflecting the company’s growth opportunities and potential for sustained earnings improvement.
For More Axis Securities Disclaimer https://simplehai.axisdirect.in/disclaimer-home
SEBI Registration number is INZ000161633


Tag News
HCL Tech rises on launching AI-Powered Nano GCC offering on AWS to help enterprises scale AI