Money Mistakes Women Should Avoid
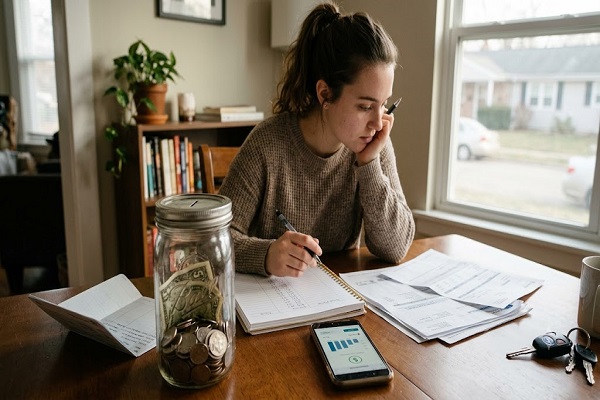
Financial independence is an important part of building a secure and confident future. Whether someone is earning independently, managing a household, or balancing both, understanding personal finance can make a major difference.
However, certain money mistakes can make it harder to build savings, manage unexpected expenses, and achieve long-term financial goals. Here are some common financial mistakes women should avoid.
1. Not Having a Personal Financial Plan
Many people manage money month to month without setting clear financial goals. Without a plan, it can be difficult to know how much to save, invest, or spend.
Women should consider setting specific goals such as building an emergency fund, buying a home, planning for retirement, or saving for education.
2. Depending Completely on Someone Else for Financial Decisions
Whether it is a spouse, parent, or another family member, relying completely on someone else to manage finances can create problems in the future.
Even when someone else handles most financial responsibilities, it is important to understand income, savings, investments, insurance, loans, and major financial commitments.
3. Ignoring Emergency Savings
Unexpected expenses can arise at any time. Medical bills, job changes, family emergencies, or urgent repairs can put pressure on finances.
Building an emergency fund can provide a financial cushion and reduce the need to rely on loans or credit cards during difficult periods.
4. Delaying Investments
Saving money is important, but keeping all savings in a low-growth option may not always be enough to achieve long-term financial goals.
Starting to invest early can give money more time to potentially grow through compounding. The right investment choices depend on individual goals, risk tolerance, and financial circumstances.
5. Avoiding Retirement Planning
Retirement may seem far away, especially when someone is early in their career. But delaying retirement planning can make the eventual savings requirement much larger.
Starting early, even with relatively small amounts, can help create a stronger retirement corpus over time.
6. Taking on Unnecessary Debt
Credit cards, personal loans, and other forms of borrowing can be useful when managed responsibly. However, high-interest debt can quickly become expensive.
Women should understand the interest rate, repayment schedule, fees, and total cost before taking on debt.
7. Not Checking Insurance Coverage
Insurance is an important part of financial planning. Depending on family members or an employer for all insurance needs may leave gaps in protection.
Health and life insurance requirements should be reviewed periodically based on income, dependents, existing coverage, and financial responsibilities.
8. Ignoring Their Credit Score
A credit score can influence access to loans and the terms offered by lenders.
Paying bills and loan EMIs on time, keeping credit utilisation under control, and regularly checking credit reports can help maintain a healthy credit profile.
9. Spending to Keep Up With Others
Social media can make expensive lifestyles appear normal. Constantly comparing spending habits with friends, influencers, or colleagues can encourage unnecessary purchases.
A better approach is to spend according to personal priorities and financial goals rather than trying to match someone else's lifestyle.
10. Not Negotiating Salary
Career income is one of the most important factors in long-term financial growth.
Not negotiating salary, promotions, or better opportunities can have a significant impact over many years. Understanding market compensation and confidently discussing professional value can help improve earning potential.
11. Failing to Keep Financial Documents Organised
Important documents such as insurance policies, investment statements, bank information, property documents, and tax records should be properly organised.
Keeping financial information accessible can make it easier to manage money and handle emergencies.
12. Not Understanding Investments
Investing without understanding where money is going can be risky. At the same time, avoiding investments entirely because they seem complicated can limit long-term financial growth.
Women can start by learning basic concepts such as mutual funds, stocks, bonds, fixed-income investments, diversification, risk, and compounding.
Conclusion
Avoiding common money mistakes is just as important as earning more money. Women can strengthen their financial future by creating clear goals, maintaining emergency savings, understanding investments, managing debt responsibly, and taking an active role in financial decisions.
Financial confidence doesn't require knowing everything from day one. Learning the basics and making consistent, informed decisions can be a strong step toward greater financial independence.