Indian mining and construction equipment industry to witness moderation in margins despite 8-10% growth in volumes in 2026-27: ICRA
-
Operating margin for ICRA’s sample set[1] of players to moderate by 100-150 bps in 2026-27, dampened by higher input as well as logistical costs
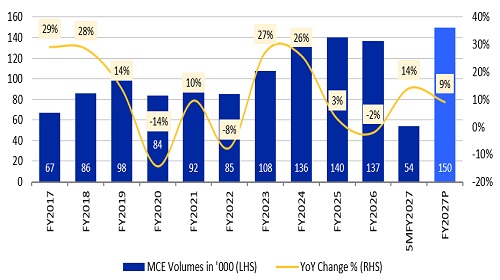
India’s mining and construction equipment (MCE) industry is set for a broad-based recovery with industry volumes expected to rise by 8-10% year-on-year (YoY) in 2026-27 to 1.50 lakh units, against the 2% decline reported in 2025-26. Exports have emerged as a key growth driver with improved emission compliance, cost competitiveness and OEM-led diversification. Nevertheless, the operating margin for ICRA’s sample set of players is projected to moderate by 100-150 bps in 2026-27, on account of higher input and logistical costs, a consequence of the West Asia crisis.
After two years of muted performance, the turnaround is already visible with domestic volumes up by 14% YoY and exports increasing by a sharp 34% YoY in the first five months of the current fiscal. Growth is being driven by domestic demand, with local sales contributing to over 80% of volumes and roughly 85-90% of equipment purchased on finance.
Providing further insights, Suprio Banerjee, Vice President & Co-Group Head, Corporate Ratings, ICRA, said: “The weakness seen in 2025-26 ran deeper than indicated by the headline volume numbers, with retail registrations falling by 9% over the year. Sluggish infrastructure execution, costlier machines following the CEV Stage-V transition and financing pressure affected demand.”
“The mood, however, has clearly shifted, with Government of India’s capital expenditure surging nearly 30% in the first four months of the current fiscal and MCE retail registrations turning positive in July 2026. Encouragingly, the buyers who had deferred purchases are now returning to the market. ICRA expects the momentum to build through the year, fuelled by the Government’s Rs. 12.2-lakh crore capex push, bigger allocation for the Jal Jeevan Mission and the Pradhan Mantri Gram Sadak Yojana, greater infra funding for states, and the proposed CIE[2] scheme to deepen domestic manufacturing and localisation.” Banerjee added.
The turnaround is primarily attributable to the earthmoving segment, with backhoe loaders (BHL) and crawler excavators together accounting for over 90% of sales. BHL volumes rebounded by 11% YoY in the first five months of the current fiscal, driven by improved project execution and higher infrastructure spending. Excavators proved more resilient, rising 4% in 2025-26 and a further 17% YoY in the current financial year, aided by sustained mining activity and the increasing adoption of specialised equipment, including mini excavators. However, mixed trends prevailed across other segments. Material handling equipment (MHE) volumes declined by 10% in 2025-26 but rebounded sharply by 40% YoY in the first five months of the current fiscal, backed by strong demand for pick-and-carry cranes. Road equipment volumes fell by 5% in 2025-26 and a further 4% YoY in the current fiscal, amid subdued project awarding by the National Highways Authority of India and Ministry of Road Transport Highways, impacting the recovery in the sector.
Exhibit: Trend in Indian MCE industry volumes in last decade
“Exports have emerged as a key growth driver, surging by 30% YoY in 2025-26 and a further 34% YoY in the first five months of the current fiscal, boosted by improved emission compliance, cost competitiveness and OEM-led diversification. The exports volumes nearly doubled to ~17% during the abovementioned period from ~9% in 2024-25. Earthmoving equipment dominates with ~75% share, led by backhoe loaders, crawler excavators and skid steer loaders. Road construction equipment recorded the fastest growth in 2025-26 (+60% YoY). The US remains the largest destination accounting for ~15% of exports, followed by Africa (7%), Saudi Arabia (5%) and the UAE (4%). Shipments to the US have started recovering after tariff moderation, while FTAs[1] with the UK, EU, Australia, New Zealand and the UAE should open additional opportunities. That said, higher steel prices, elevated freight costs and supply chain disruption due to global conflicts remain key risks,” Banerjee added.
On the financial front, ICRA’s sample set of 14 large MCE players is projected to report 11-13% YoY revenue growth in 2026-27, after the flat performance in 2025-26, aided by volume recovery, continued export momentum, modest price hikes and a favourable product mix. Operating margins, however, are expected to moderate by ~100-150 bps to ~6-8% from ~8.4% in 2025-26 owing to higher steel prices, elevated logistics costs and the rising cost of imported components, amid rupee depreciation. Stiff competition and limited pricing flexibility could constrain the pass-through of this cost inflation.
Despite the margin pressure, ICRA expects the credit profile of the OEMs to remain stable in 2026-27 with strong cash accruals, limited external debt and healthy coverage indicators. Accordingly, ICRA maintains a Stable outlook on the Indian MCE industry.
Above views are of the author and not of the website kindly read disclaimer