Derivative Rollover Note 30th September 2026 by Motilal Oswal Wealth Mangement
Nifty remains under pressure as bears drag the index; only short covering to the rescue for October series
Nifty index started the September series on a flattish note but witnessed sustained selling as the series progressed. The index initially moved towards 24100 zones but failed to sustain at higher levels and gradually slipped towards 22500 zones as it approached expiry. Every bounce attracted fresh selling and dragged the index to close near its lower band. On an expiry-to-expiry basis, it formed a bearish candle indicating that sellers retained control throughout the series.
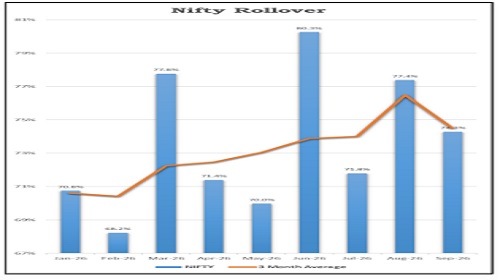
In the September series, open interest increased by 29.8% while the index fell by 6.7% on an expiryto-expiry basis indicating short built up in the index. Rollover of Nifty stood at 74.3%, which is in line with its quarterly average of 74.5%.
On the option front, Maximum Call OI is at 23500 then 23000 strike while Maximum Put OI is at 23000 then 22500 strike. Call writing is seen at 23000 then 22700 strike while Put writing is seen at 22700 then 22000 strike. Option data suggests a broader trading range in between 21800 to 23500 zones while an immediate range between 22200 to 23200 levels.
Nifty closed at 22716 zones and At The Money Straddle (October Monthly 22700 Call and 22700 Put) is trading at net premium of around 660 Points, giving a broader range of 22040 to 23360 levels. Till Nifty holds below 23000 zones sell on bounce could continue towards 22400 then 22200 zones, while resistance can be seen at 23300 then 23500 zones.
September series remained challenging for the broader market with selling pressure across the street keeping bears in control for most of the month. Despite the weakness in benchmark indices, selective sectors and stocks continued to show relative strength. Outperformance was visible in select Auto Ancillary, Engineering, Pharma & Healthcare, Specialty Chemicals and New-Age companies. On the other hand, IT, Auto, PSU Banks, Banking & Finance, Insurance and Realty remained under pressure weighing on the broader market.
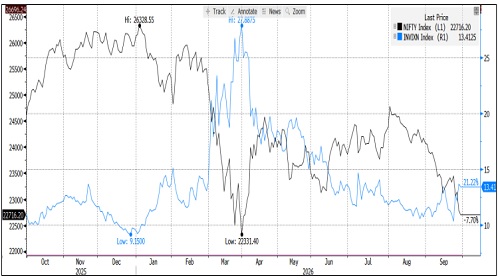
India VIX increased by 21.01% from 11.07 to 13.41 levels in the September series. It spiked above 14.7 levels amidst global tensions and gave some discomfort to the market.
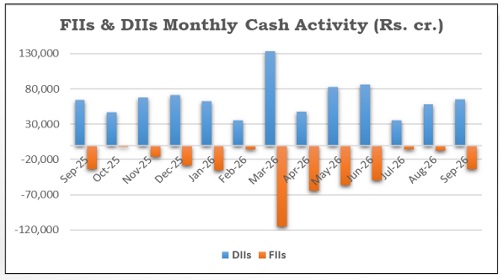
FIIs continued their selling streak of the last fifteen months and sold equities worth 33,864 crores in the month of September so far. On the other hand, DIIs consistently bought to the tune of 64,759 crores in September so far and registered its 38th straight consecutive month of buying. The FIIs Long Short Ratio in index futures remained within a band in the entire series and ranged in between 8.6% to 12.6% and closed at its lowest band.
Bank Nifty index started the September series on a positive note and witnessed buying in the initial phase before facing resistance near 58000 zones. The index witnessed selling at higher levels and gradually slipped towards 53800 zones, amidst heightened volatility. On an expiry-to-expiry basis it formed a bearish candle indicating selling at higher levels. Till it holds below 55500 zones sell on bounce could continue towards 53500 then 53000 zones while on the upside hurdles are placed at 56000 zones.
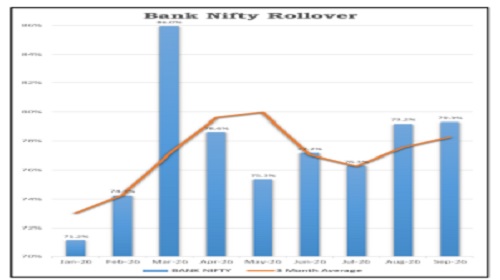
Bank Nifty ended the September series with losses of 5.7% with an increase in open interest by 15.6% indicating short built up in the rate sensitive index. Rollover in Bank Nifty stood at 79.3%, which is in line with its monthly and quarterly average of 78.3%.
For More Research Reports : Click Here
For More Motilal Oswal Securities Ltd Disclaimer
http://www.motilaloswal.com/MOSLdisclaimer/disclaimer.html
SEBI Registration number is INH000000412


Tag News
Quote on Market 30th September 2026 from Vinod Nair, Head of Research, Geojit Investments Li...