Commodity Market Report : Middle East flare-Up pushes oil higher, weighs on gold and base metals by Emkay Global Financial Services Ltd
Market commentary and macro trends
Precious metals
Gold opened the month on a steady note near $4,150 an ounce following a nearly 6% drop in September, as softer-than-expected August core PCE inflation (0.2%) reduced market expectations of an October Federal Reserve rate hike to roughly 34%. However, bullion remains under pressure from multi-decade highs in long-dated US Treasury yields, driven by strong US consumer spending data and the elevated opportunity cost of holding nonyielding assets amid persistent global rate tightening and fiscal deficit concerns.
While the lower inflation reading offers a modest buffer against further rate hikes, markets now await Friday's US jobs report for clarity on the Federal Reserve's near-term policy trajectory
Base metals
As October 2026 begins, copper remained the strongest performer among base metals, maintaining its uptrend and closing September above $14,400/MT. In contrast, aluminum, zinc, lead, nickel, and tin corrected amid a broader risk-off environment driven by a stronger US dollar, higher Treasury yields, and the Federal Reserve's recent rate hike.
Additionally, Chinese markets will remain closed for the Golden Week holidays, reducing trading activity and liquidity across Asian markets. During this period, domestic MCX prices are likely to take cues from currency movements and international developments, with stronger price action expected after LME trading opens in the afternoon (IST).
Base metal prices are expected to remain volatile through October. Our daily report will track technical levels, inventory trends, key economic events, and trading opportunities. For today, metals are expected to trade sideways to slightly weaker.
Energy complex
WTI crude oil prices have steadied near $90/bbl following a three-month streak of gains through September, supported by persistent geopolitical tensions, particularly around USIran relations and the Strait of Hormuz, as well as historically tight fuel inventories, including record-low seasonal US distillate stocks.
Although crude supply flows from the Middle East are nearing pre-war levels, refined fuel output is recovering more slowly, creating product market tightness that underpins prices despite speculation over potential US diesel export limits. Consequently, the near-term outlook remains cautiously bullish as markets balance the geopolitical risk premium and low fuel inventories against the long-term durability of Middle East supply normalization.
Gold technical outlook
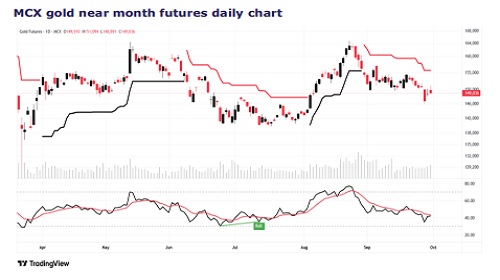
? Gold remains well below both the Super trend resistance line and the major moving averages, confirming prevailing selling pressure on the daily timeframe.
? Prices are heading toward an immediate low around 145,990, with a bearish chart pattern of lower highs and lows.
? The absence of a bullish crossover or divergence in the RSI suggests buying momentum remains subdued, leaving the gold vulnerable to retesting lower structural support levels.
Trend: Bearish
Resistance: 154,600
Support: 145,990
Copper technical outlook
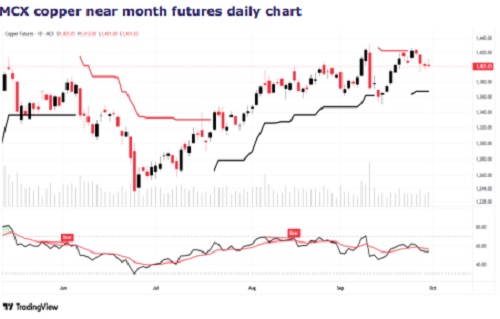
? MCX Copper October futures closed marginally lower at Rs1,401.65, down 0.25%, after an intraday surge to Rs1,412. The metal continues to hold above the 20- day EMA at Rs1,396, keeping the underlying trend positive.
? The RSI stands at 53, remaining comfortably above the neutral 50 mark, which suggests that positive momentum is still intact. However, with prices trading close to recent and all-time highs, some profit bookings cannot be ruled out.
Trend: Bullish
Resistance: 1,412
Support: 1,396
Aluminium technical outlook
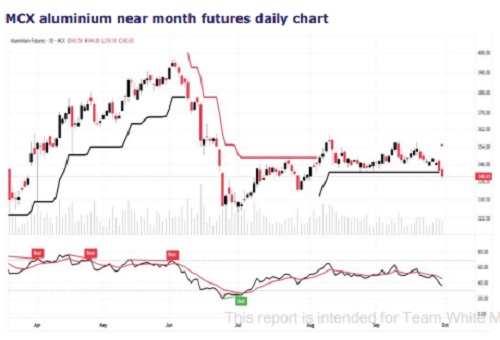
? MCX Aluminium closed lower at Rs340.60, down 0.73%, and has consistently remained below the 20-day EMA at Rs347.70.
? The RSI around 36 indicates continued weakness, while the structural breakdown from the symmetrical triangle on the daily chart reinforces the bearish setup. We expect weakness to persist in the near term.
Trend: Bearish
Resistance: 345
Support: 339
For More Emkay Global Financial Services Ltd Disclaimer http://www.emkayglobal.com/Uploads/disclaimer.pdf & SEBI Registration number is INH000000354