U.S. Wheat Price Outlook Strengthens Amid Higher Global Supplies by Amit Gupta, Kedia Advisory
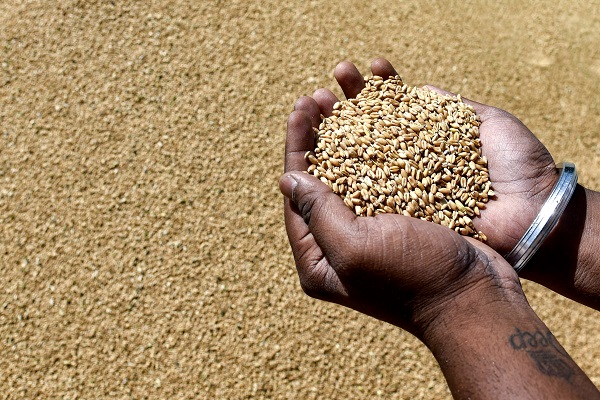
U.S. wheat fundamentals remained broadly stable for 2026/27, with aggregate supply and use categories unchanged, while export projections shifted among wheat classes. White wheat exports rose 20 million bushels, offset by lower Hard Red Winter and Hard Red Spring exports. The U.S. season-average farm price increased $0.20 to $6.40 per bushel, supported by NASS prices, firmer futures and cash expectations, and higher corn prices. Globally, wheat supplies rose 3.5 million tonnes to 1,103.0 million, led by higher production in Australia, Canada and Ukraine. Consumption increased modestly, while trade declined and ending stocks climbed to 276.3 million tonnes.
Key Highlights
• U.S. wheat season-average farm price raised $0.20 to $6.40 per bushel for 2026/27.
• White wheat exports increased 20 million bushels, offsetting reductions in other classes.
• Global wheat supplies increased 3.5 million tonnes to 1,103.0 million tonnes.
• World wheat trade declined 0.9 million tonnes to 211.8 million tonnes.
• Global ending stocks rose 3.0 million tonnes to 276.3 million tonnes.
U.S. wheat fundamentals remained largely unchanged for 2026/27, but the season-average farm price was raised to $6.40 per bushel, up $0.20 from the previous forecast. The increase reflects NASS prices reported to date and expectations for futures and cash prices during the remainder of the marketing year. Higher U.S. corn prices also provide additional support to wheat’s price outlook.
Export expectations within the U.S. wheat balance sheet showed notable shifts by class. White wheat exports were raised by 20 million bushels, while Hard Red Winter and Hard Red Spring exports were reduced by 15 million and 5 million bushels, respectively. The adjustments are based on sales and shipments reported so far, along with the price competitiveness of each wheat class against key international suppliers.
The global wheat outlook turned more supply-heavy this month. World supplies are projected at 1,103.0 million tonnes, up 3.5 million, mainly due to stronger production estimates in major exporting countries. Australia’s crop was raised by 3.0 million tonnes to 31.0 million amid favorable conditions, while Canada increased by 1.0 million tonnes to 36.0 million. Ukraine production rose 0.6 million tonnes to 26.0 million on record yields, partly offset by a 1.0-million-tonne reduction for Kazakhstan.
Global consumption increased 0.5 million tonnes to 826.8 million, driven by higher feed and residual use. However, world trade was lowered 0.9 million tonnes to 211.8 million, with weaker shipments from Russia, Ukraine, Kazakhstan and Egypt. Black Sea logistics disruptions weighed on Russian and Ukrainian exports. Global ending stocks are projected at 276.3 million tonnes, up 3.0 million, led by higher stocks in Russia, Australia and Ukraine.
Overall, sronger global supplies and stocks may limit wheat gains, although firmer U.S. prices and supportive corn markets could provide a cushion against deeper downside.
Above views are of the author and not of the website kindly read disclaimer
.jpg)