SAMHI Hotels Reports 15.6% Revenue Growth in Q2 FY27; Occupancy Reaches 78.6%
Delivered strong double-digit revenue growth, expanding EBITDA
SAMHI Hotels Limited (BSE: 543984, NSE: SAMHI), a prominent branded hotel ownership and asset management platform in India, today announced its unaudited Standalone and Consolidated results for the quarter and financial year ended 30th September 2026.
Q2 FY27 — KEY HIGHLIGHTS
Strong same-store revenue growth of +12.6% YoY – ahead of our long-term guidance of 9 to 11%
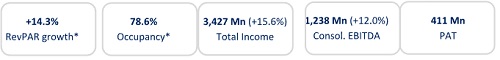
* Occupancy level at 78.6% (up from 75.0% Q2-FY26)
* RevPAR growth of +14.3% YoY led by +9.2% ARR growth
* Flow through of incremental EBITDA to incremental Revenue stood at ~57%
* Domestic travellers constitute ~80% of total room nights we sold in the quarter. More resilient cohort given geo-political instability
* Total Revenue growth of +15.6% YoY with Comparable EBITDA growth of +21.3% YoY excluding impact of GST regulation change (not in base period Q2FY26)
* Consolidated EBITDA margin of 39.1% (ex GST impact); 300 bps dilution due to GST impact resulting in reported margins at 36.1% – scope for improvement in subsequent periods; growth in upscale inventory (not impacted by GST changes) to improve operating margins to ~40%
* The on-going growth pipeline within our core portfolio and the progress in RARE India gives us a formidable path to growth
* PBT (ex-exceptional items) a Rs. 534 Mn (+39.9% YoY Reported)
* PAT (ex-exceptional items) at Rs. 372 Mn (+136.9% YoY Reported); Reported PAT includes exceptional gain of Rs. 39 Mn and Rs. 841 Mn in Q2FY27 and Q2FY26 respectively
* Free Cash Flow at Rs. 827 Mn
* Effective Interest Rate at 7.8% (~300 bps lower than IPO)
* Net Debt-to-EBITDA at ~3.1x (~2.2x on Operating Assets)
CONSOLIDATED FINANCIAL HIGHLIGHTS
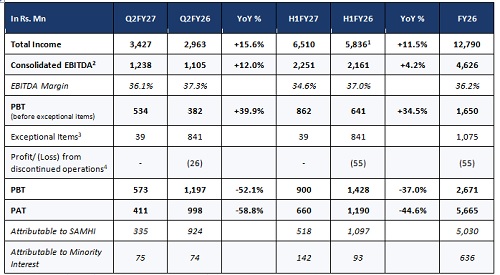
1: Includes the impact of ~ Rs 91mn of one-time other income in H1FY26 on account of a subsidiary capital restructuring related to the GIC transaction
2: Includes the impact of:
a) GST – input tax credit (ITC) impact of ~Rs 103mn and ~rs 194mn in Q2FY27 and H1 FY27 respectively
b) ~Rs 21mn of one-time GIC transaction expenses in H1 FY26
3: This includes :
a) Gain on sale of Hosur land- rs 39mn in Q2 FY27 and H1 FY27
b) Reversal of impairment (Navi Mumbai land) - rs 696mn and Gain on sale of Caspia, Delhi– 145mn in Q2FY26 and H1 FY26
c) Impact of reversal of impairment of PPE, ROU and Intangibles: +Rs 966mn, impact of labor code: –Rs 35mn and Gain on sale of Caspia Delhi: +Rs 145mn in FY26
4: Profit/Loss from discontinued operations represents Caspia Delhi
DEBT PROFILE
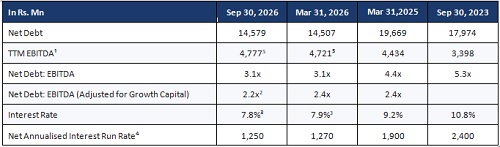
1: Excluding ESOP & One-time Expenses
2: Capital allocated towards W (HITEC Hyd.), Westin Bglr., HRP Apartments, Sheraton Rooms & Apartments, HIEX (Wht. Bglr.), Westin Navi Mumbai and other capital expenditure
3: As on 30th September 2026. Please note that the interest rate includes the upfront fee which is amortized over the estimated repayment period
4: Does not include non-cash finance cost items such as interest on lease, EIR, etc. which are charged to P&L
5: Excludes Caspia Delhi EBITDA on TTM basis
6. 8.0% net annualized interest rate factored in the estimate on account of recent policy rate increase by RBI
MANAGEMENT COMMENTARY
Commenting on the performance, Mr. Ashish Jakhanwala, MD & CEO, SAMHI Hotels Ltd., said:
Strong Operating Environment
We are pleased to report our performance for the quarter. Occupancy held close to 80% and RevPAR grew by about 14%, making this a reassuring period for the business. Revenue growth remained ahead of our long-term guidance. Domestic travellers accounted for about 80% of the room nights sold during the quarter. This cohort has proven more resilient amid ongoing geopolitical instability, reinforcing our confidence in the resilience of the Indian economy and the opportunity it represents.
Building for the Future
Against this strong backdrop, we have been steadily building for the future. For several quarters, our reported growth has been largely driven by same-store performance, as no new inventory came online. This is set to change. We look forward to opening the W Hotel in Hyderabad next fiscal year and have secured a pipeline of approximately 1,700 new rooms through FY2031. These initiatives put us on a path to strong growth, and our focus now is on delivering them on schedule.
We are equally proud of having built this pipeline without compromising our discipline: we add assets only in core markets and at a discount to replacement cost. We are not buying growth through expensive acquisitions; instead, we are building it through the efforts that conversions and turnarounds demand, as demonstrated in Bangalore, and by securing long-term leases, as in Noida and Hyderabad.
Our modest investment in RARE, together with ongoing discussions on a partnership with Marriott, will help RARE build a strong platform in experience-led leisure across the region, with limited capital exposure.
Outlook
We expect H2 FY27 to be operationally stronger. Going forward, incremental EBITDA is expected to translate into free cash flow, with interest outflows remaining stable. This should enable us to increasingly fund future growth investments through internal cash generation, supporting a disproportionate improvement in free cash flow generation.
Our Focus on Doing What Is Right
We released our first Sustainability Report for FY2025-26, covering 31 hotels and 4,899 rooms across 11 states. The report highlights improvements in energy efficiency, waste reduction and renewable energy usage. Building on our FY30 commitments, we will establish quantified targets across key sustainability parameters, with clear baselines to track and benchmark our progress.
Above views are of the author and not of the website kindly read disclaimer