Diwali Muhurat Picks 2026 : Samvat 2083 by Motilal Oswal Wealth Management
Samvat 2083 begins on a cautious note, as an external energy shock overshadows a resilient economy. The West Asia conflict has kept Brent crude above $100/bbl, lifting CPI inflation to 5.54% in September and prompting a 25 bps repo rate hike to 5.50%. Record FII outflows of about USD28b in Jan–Sep’26 and a rupee near ?95/USD have weighed on large caps, with the Nifty down about 12% over Samvat 2082. Yet domestic growth remains robust, with GDP at 7.8% in Q1FY27, while budgeted capex of ?12.2 lakh crore and last year’s tax and GST relief support demand, and record SIP inflows have absorbed foreign selling. Action also remains in the primary market: Jio Platforms’ record IPO and NSE’s listing headlined a busy year, with over 225 companies in the pipeline. Key monitorable include the RBI’s rate trajectory, crude prices, FII flows, trade agreements and earnings growth.
We perceive FY27 to mark a return to double-digit earnings growth, with Nifty EPS expected to grow 16%/14% YoY in FY27/FY28 vs 5% in FY26. Nifty valuations are attractive at 17.5x forward earnings, 16% below the long-term average. After a ~10% correction from record highs, midcaps trade 6% below their long-term average, while smallcaps remain at a 25% premium; thus one needs to follow a selective approach in stock picking. For Samvat 2083, we are positive on BFSI and Capital Markets, Manufacturing, Global Outsourcing/Exports, and Consumption & Digital.
Banks are set for steady loan growth with improving margins, while rising participation supports capital markets segment. Manufacturers in healthcare devices, aerospace and auto components are scaling up on strong order books. Pharmaceutical ingredients, garments and port cargo are expected to gain from global outsourcing and trade agreements, while organized jewellery and quick-commerce platforms continue to gain market share.
Diwali Picks Summary
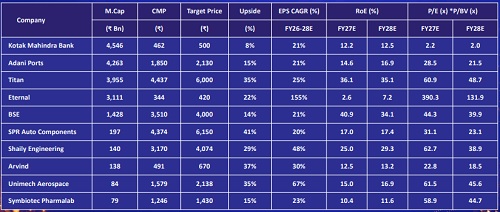
Kotak Mahindra Bank
* Kotak Mahindra Bank is poised for healthy growth across retail, small business and corporate lending, with loan growth guided at ~1.5-2.0x nominal GDP growth.
* Margins should recover as surplus foreign currency deposits are deployed and higher repo rates pass through to loan yields. Unsecured loan quality is improving.
* We estimate net interest income/net profit CAGRs of ~19.7%/24.1% over FY26- 28E, with return on assets of 2.07% in FY27E.
Adani Ports
* Adani Ports is well placed to fund expansion, with strong cash flows, a cash balance of ?125b and net debt to operating profit of 1.8x.
* Port capacity additions, infrastructure projects and global acquisitions provide visibility, with cargo volumes expected to grow at a 14% CAGR over FY26-28E.
* We estimate revenue/operating profit/net profit CAGRs of 17%/18%/21% over FY26- 28E.
Titan
* Titan is India’s leading jewellery brand, backed by strong sourcing and a rising share of studded jewellery, and gains as buying shifts to organised players.
* With 3,551 stores as of Jun’26, store expansion and non-jewellery businesses add growth levers. Stable gold prices could improve margin visibility.
* We estimate revenue/operating profit/net profit CAGRs of 17%/21%/23% over FY26- 29E.
Eternal
* Eternal benefits from its leading food delivery platform and Blinkit’s quick commerce network, with food delivery order value targeted to grow 20%+ long term.
* Blinkit’s store target is raised to 3,500+ by FY27-end and ~5,000 by FY28-end, while food delivery margins stay stable.
* We estimate revenue/net profit CAGRs of ~75%/~155% over FY26-28E.
BSE
* BSE’s futures and options turnover is up 85% in Oct’26 so far, and the partial rollback of closing auction session norms from 7-Dec-26 adds support.
* Growth extends beyond derivatives: 30%+ share of options premium turnover, cash market share at ~9%, and recurring income from mutual fund and co-location services.
* Operating margin rose to 65%+ in FY26 from 9% in FY21. We estimate a ~27% net profit CAGR over FY26-28E.
SPR Auto Components
* SPR Auto Components is evolving from a piston maker into a diversified auto component platform, with >45% market share in pistons.
* Acquisitions contribute ~35% of revenue and lift content per vehicle to over ?30,000, while multi-fuel adoption adds runway.
* We estimate a 21% net profit CAGR over FY26-29E, with core return on capital employed rising from 20% to 28%.
Shaily Engineering
* Shaily Engineering is positioned for strong healthcare growth, driven by rising volumes of GLP-1 pens, capacity additions and new platforms.
* Consumer electronics and semiconductors add growth avenues, and operating margins are expected to exceed 32% by FY28E.
* We estimate revenue/net profit CAGRs of 33%/48% over FY26-28E.
Arvind
* Arvind is evolving into a garments and advanced materials-led business, supported by new capacities and a strong order book.
* The potential India-UK free trade agreement adds a lever. Management expects a stronger second half, with garments up ~15% and advanced materials 18%+.
* We estimate revenue/net profit CAGRs of 18%/30% over FY26-28E.
Unimech Aerospace
* Unimech Aerospace is positioned to capitalise on rising aerospace outsourcing, backed by long-term global contracts and a strong order pipeline.
* A robust nuclear order book and diversification into semiconductors and oil & gas add further growth avenues.
* We estimate revenue/net profit CAGRs of 75%/69% over FY26-28E, with operating margins above 38%
Symbiotec Pharmalab
* Symbiotec Pharmalab is expanding from steroid-based pharmaceutical ingredients (38% global volume share) into contract drug development and complex injectables.
* Exports are 67% of FY26 revenue. With ?16.7b of capex done by FY27, the focus shifts to commercialising new capacity.
* We estimate revenue/net profit CAGRs of 33%/37% over FY26-29E, lifting return on equity to 17%.
For More Research Reports : Click Here
For More Motilal Oswal Securities Ltd Disclaimer
http://www.motilaloswal.com/MOSLdisclaimer/disclaimer.html
SEBI Registration number is INH000000412