Market Explorer - November 2026 by Religare Broking Ltd

MARKET OVERVIEW
Indian equity markets remained volatile in October 2026, with persistent foreign investor selling weighing on sentiment, while domestic institutions continued to provide liquidity support. FIIs/FPIs recorded equity outflows of rs 45,161 crore, whereas DIIs extended their buying streak to 40 consecutive months with investments of Rs 62,220 crore. Gross GST collections grew 11.8% YoY to Rs 2.12 lakh crore, indicating sustained economic activity. The HSBC India Manufacturing PMI strengthened to 57.5 from 55.1, supported by festive demand and higher production. Strong SIP inflows and domestic participation helped cushion markets against elevated crude prices and global uncertainties.
MARKET OUTLOOK
Indian equity markets are expected to remain resilient, supported by healthy Q2FY27 earnings growth, strong domestic SIP inflows and robust economic activity. Government capex, GST collections and festive demand continue to support growth, while healthy corporate earnings provide a strong fundamental base. While elevated crude prices of US$102–115/bbl, CPI inflation of 5.49% and persistent FPI outflows pose near-term challenges, the possibility of a tighter RBI policy stance remains a monitorable. Importantly, valuations across several large-cap stocks have corrected to more reasonable levels, improving their riskreward profile. We remain constructive on the medium-term outlook, with earnings resilience, domestic liquidity and attractive large-cap valuations expected to support market stability and create opportunities for selective accumulation.
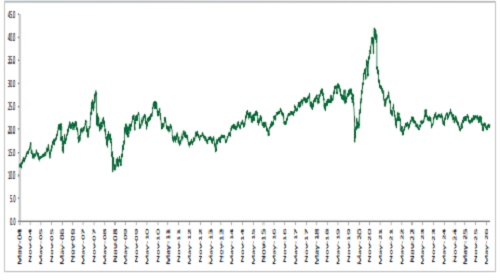
Nifty PE Movement
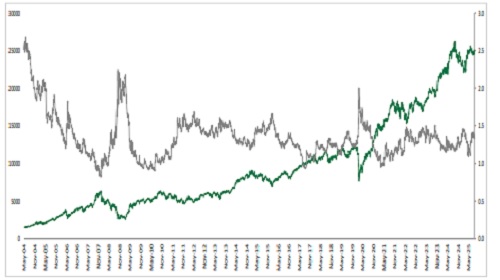
Nifty Dividend Yield Chart
MONTHLY OUTLOOK
The Month That Was:-
Nifty gained 432.65 points in the month of October, 2026.
Below is a summary of Top Nifty Gainers & Losers:
Top Nifty Gainers Oct. 2026
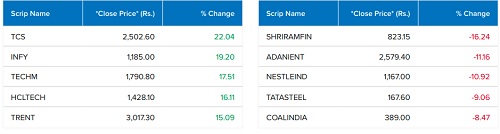
• Breadth was negative in October 2026, with 22 Nifty stocks closing in the green versus 28 stocks in the red.
• Relative comparison showed IT, Pharma, Media emerged as the top-performing sectors, while Metal, Energy, Realty, Auto underperformed in October 2026.
Sector Relative Performance
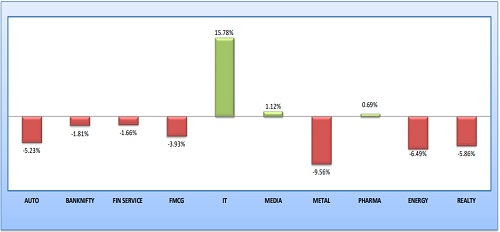
* All the sectors have been compared with Nifty & the zero line represent Nifty. The movement of the sector vis-a-vis Nifty whether they outperform or underperform is shown in the above chart. It shows which sectors have attracted inflows and also the sectors from where money has exited.
Outlook for Nifty 50 (23,053.10)*
Support 23,200/22,800/22,400
Resistance 23,900/24,200, 24,400
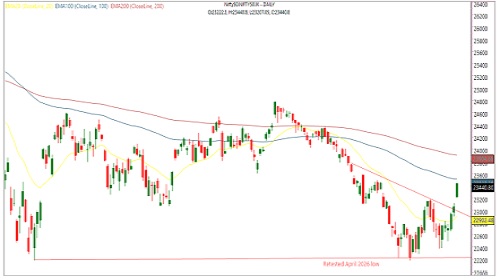
• The Nifty took a breather following the sharp correction in September, trading within a broader range of 22,200–23,200 to eventually close at 23,053.10, gaining nearly 2%.
• Among the sectors, IT clearly emerged as the standout outperformer, gaining over 17%, followed by modest gains in pharma and media. On the other hand, metal index emerged as the weakest performer amid a decline in metal prices, followed by energy, realty and auto, which lost around 4–5%.
• In the previous report, we highlighted Nifty’s proximity to its major support zone, indicating the possibility of a near-term breather. The index subsequently held its 200-WEMA and witnessed consolidation of nearly 1,000 points above this crucial support, providing some stability to the price structure. However, the broader trend continues to remain fragile, with the 23,500–23,600 zone acting as a key near-term hurdle. A decisive breakout above this range could lend strength to the ongoing recovery and pave the way for further upside. On the downside, the 22,900–22,800 zone will now serve as an immediate support area, and holding above it will be crucial to sustain the recovery. Given the prevailing market conditions, traders should remain selective, utilise rebounds cautiously, avoid excessive leverage and adhere to disciplined risk management.
Outlook for Bank Nifty (54,686.95)*
Support 54,500/53,800/52,700
Resistance 56,300/57,000/58,000
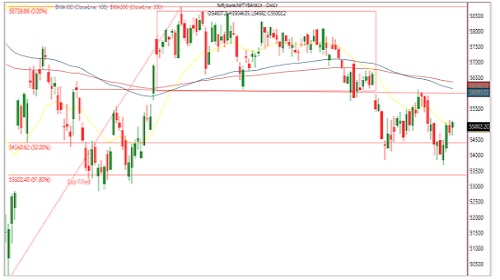
• The banking index lagged the benchmark, struggling to gain meaningful traction amid overhead resistance, and eventually closed nearly flat at 54,686.95.
• Mixed trends were observed among the major banking constituents, with Kotak Bank, Union Bank, PNB and Federal Bank outperforming, while Yes Bank, AU Bank and IDFC First Bank witnessed sharp declines.
• Amid mixed performance among the major banking constituents, the index continues to struggle for a meaningful recovery, with every rebound facing selling pressure near its overhead resistance zone. The 55,200 level will act as an immediate hurdle, while the broader near-term outlook is likely to remain subdued as long as the index trades below 56,000. A decisive move above this level would be required to revive positive momentum. On the downside, 53,800 will act as immediate support, followed by the 52,700 zone. In the prevailing scenario, participants should maintain a cautious stance and adopt a selective approach, focusing on banking stocks exhibiting sustained price strength and relative outperformance.
Please refer disclaimer at https://www.religareonline.com/disclaimer
SEBI Registration number is INZ000174330