How to Plan for Your Child`s Education
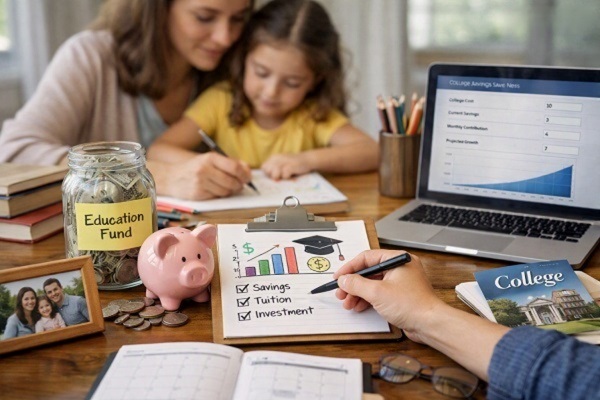
Planning for a child’s education is one of the most important financial goals for parents. Education costs can increase significantly over the years, especially for professional courses, private colleges, and studies abroad. Starting early can make the goal easier to manage and reduce financial pressure later.
Here are some practical steps parents can follow to build a strong education fund.
1. Start Planning Early
The earlier you start, the more time your money has to grow. Even a small monthly investment can become a meaningful corpus over 10, 15, or 20 years because of the power of compounding.
Parents should ideally begin planning as soon as possible rather than waiting until the child reaches school or college age.
2. Estimate Future Education Costs
Don't plan only according to today's education fees. Costs may rise because of inflation.
For example, if a course currently costs ?10 lakh, it could cost considerably more when your child is ready to enrol. Consider:
* School and college fees
* Professional courses
* Books and study materials
* Accommodation
* Transportation
* Technology such as laptops
* Coaching or entrance-exam preparation
* Overseas education expenses, if applicable
Having an approximate future target makes the investment plan more realistic.
3. Consider Education Inflation
Education costs can increase over time. Therefore, simply saving today's estimated fee may not be enough.
Parents should factor inflation into their calculations and regularly review the target amount. A financial goal that looks sufficient today may fall short several years later.
4. Decide How Much You Need to Invest
Once you have estimated the future cost, calculate how much you need to save or invest regularly.
For example, if your target is several years away, you may be able to invest a fixed amount every month through a systematic investment approach. As your income increases, you can also increase the investment amount.
A step-up approach can be useful because it allows your contribution to rise gradually with your income.
5. Choose Investments According to the Time Horizon
The investment strategy should depend on how many years remain before the money is needed.
For a long-term goal, parents may consider growth-oriented investments such as equity mutual funds, depending on their risk tolerance. As the education goal gets closer, gradually moving a portion of the corpus toward relatively less volatile investments can help protect the accumulated money.
There is no single investment option that is suitable for every family.
6. Don't Depend Entirely on Education Loans
Education loans can help bridge a funding gap, but parents should not assume that borrowing will automatically solve the problem.
Building an education corpus in advance can reduce the amount that the family or child may need to borrow later.
The objective should be to create a balance between saving, investing and using loans only when necessary.
7. Keep the Education Fund Separate
It can be helpful to keep the education corpus separate from everyday savings.
Having a dedicated investment or savings plan makes it easier to track progress and reduces the temptation to use the money for unrelated expenses.
8. Review the Plan Regularly
Financial circumstances can change over time. Your income may increase, education costs may rise faster than expected, or your child's career plans may change.
Review the plan at least once a year and check:
* Current investment value
* Expected future education cost
* Monthly contribution
* Investment performance
* Remaining time
* Whether the target needs to be increased
Regular reviews can help identify a shortfall early.
9. Don't Sacrifice Retirement Completely
Parents often prioritise their children's education so heavily that they neglect retirement planning.
This can create a problem later. Unlike education, retirement generally cannot be funded through a loan.
Therefore, try to maintain both goals simultaneously. Your child's education is important, but building financial security for your own later years is important too.
10. Teach Your Child About Money
Financial planning doesn't have to remain only a parent's responsibility.
As children grow older, teach them basic concepts such as saving, budgeting, investing and responsible spending. When they understand the cost of education, they may also make more informed decisions about courses, colleges and career choices.
Conclusion
Planning for your child's education is a long-term financial goal that requires consistency rather than last-minute decisions. Start early, estimate future costs, account for inflation, invest according to your time horizon and review the plan regularly.
Most importantly, balance your child's education goal with other financial priorities such as emergency savings, insurance and retirement planning. A well-planned education fund can give your child more opportunities while helping your family avoid unnecessary financial stress.