Diwali Picks 2026 : Larsen & Toubro Ltd for the Target Rs. 4,510 by Axis Securities Ltd
Strong Order Book to Support Sustained Earnings Growth
Larsen & Toubro (L&T) is well positioned to benefit from sustained infrastructure spending in India and continued investments in energy and industrial infrastructure across the Middle East. Its presence across infrastructure, energy, hi-tech manufacturing and technology services provides diversified growth opportunities, while its strong execution capabilities and established client relationships support its competitive position. With a record order book and a healthy project pipeline, revenue visibility remains strong. We believe sustained order inflows, better execution and an improvement in project profitability will drive earnings growth over the next two years.
Strong Order Inflows Provide Revenue Visibility: L&T’s order book grew 28% YoY to Rs. 8.54 lakh crore at the end of Q2FY27, providing strong revenue visibility over the medium term. Order inflows stood at Rs. 1.48 lakh crore during the quarter, reflecting healthy project wins across the energy and infrastructure segments. Going ahead, sustained infrastructure spending in India, a gradual recovery in private-sector capex and continued investments in the Middle East’s energy sector should support order prospects. We estimate order inflows of Rs. 4.79 lakh crore in FY27 and Rs. 5.27 lakh crore in FY28, keeping the order pipeline healthy. The sizeable backlog underpins our growth outlook, with the focus now shifting to execution, conversion of orders into revenue and the ability to secure fresh orders at healthy margins.
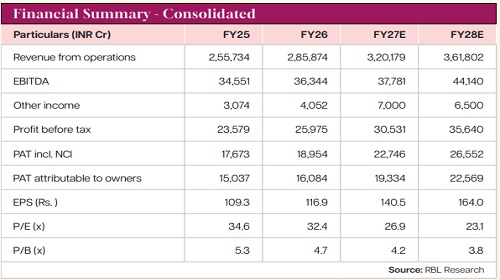
Execution to Drive Revenue and Earnings Growth: We expect L&T’s revenue growth to be driven by execution of its sizeable order book, supported by fresh wins across infrastructure and energy, including continued investments in the Middle East. We estimate revenue to grow from Rs. 2.86 lakh crore in FY26 to Rs. 3.62 lakh crore in FY28, a CAGR of around 12.5%, as the strong backlog converts into execution. EBITDA is expected to increase from Rs. 36,344 crore to Rs. 44,140 crore, supported by operating leverage, improved project mix and execution efficiencies. Our estimates factor in gradual margin improvement, with the pace of earnings growth dependent on timely project execution and cost discipline.
Margin Improvement and Working-Capital Discipline Remain Key: Profitability remains dependent on project mix, execution efficiency and input costs. Margins in certain businesses have been affected by execution challenges and cost pressures, making a sharp recovery unlikely without sustained improvement at the project level. However, progress on ongoing projects and disciplined bidding should support gradual improvement. Working-capital management remains a strength, with net working capital at 1.7% of revenue in September 2026. We estimate owners’ PAT will increase from Rs. 16,084 crore in FY26 to Rs. 22,569 crore in FY28, implying a CAGR of approximately 18.4%. Achieving this growth will require consistent execution and better profitability across projects
Emerging Businesses Provide Long-Term Opportunities: L&T’s presence in green energy, offshore wind, semiconductor-related activities and AI data centres provides opportunities beyond its traditional engineering and construction business. While these segments could contribute to growth over time, their impact will depend on execution, investment requirements and commercial viability.
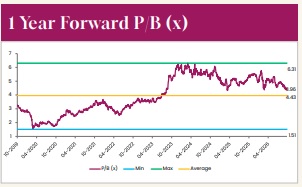
Valuation and Outlook: L&T offers an attractive play on India’s infrastructure capex cycle and rising global energy investments, with its record order book providing strong revenue visibility over the medium term. We expect execution-led growth, operating leverage and gradual margin improvement to drive an 18.4% CAGR in owners’ PAT over FY26–FY28E. With earnings growth supported by a diversified business mix and a strong project pipeline, we initiate a coverage with a BUY rating and a target price of Rs. 4,510, based on a blended P/E and P/B valuation using FY28E estimates.
For More Axis Securities Disclaimer https://simplehai.axisdirect.in/disclaimer-home
SEBI Registration number is INZ000161633