Diwali Muharat Pick : Buy Hexaware Technologies Ltd for the Target Rs.693 by Sushil Finance
A STICKY, DIVERSIFIED FRANCHISE THAT COMPOUNDS THROUGH ITS EXISTING ACCOUNTS:
Hexaware's revenue is anchored by a sticky, highly diversified base across regulated sectors like BFSI and Healthcare, backed by long-standing Fortune 500 relationships averaging 15 years. The company successfully compounds this foundation using a land-and-expand model, demonstrated by steady growth across key client brackets ($1M+, $5M+, and $20M+ accounts) and balanced geographic and vertical mixes. This durable, low-concentration franchise delivers strong cash flow generation and provides a reliable platform for future growth.
MODERNIZATION AND VENDOR CONSOLIDATION DRIVE GROWTH, AND MARGINS HAVE ROOM TO EXPAND:
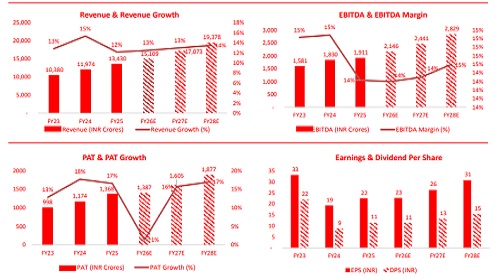
Hexaware’s growth is driven by enterprise legacy modernization and vendor consolidation wins, shifting its pipeline toward larger $10M+ programs that enhance revenue visibility. Earnings are projected to outpace revenue as margins recover from normalized bases and scale over time. Overall, from CY26E to CY28E, the model projects revenue compounding at ~13% (reaching Rs.19,378 Cr) and PAT growing at ~16% annually, with EPS rising to Rs.30.8.
PROPRIETARY AI PLATFORMS DEFEND THE CORE AND CATALYZE CROSS-SELLING:
Hexaware counters industry-wide risks of AI billable-hour erosion by proactively delivering productivity gains and targeting new generative AI revenue archetypes. The company operationalizes this through proprietary platforms like Tensai and Agentverse—offering over 600 pre-built agents and enterprise-grade governance tailored for regulated sectors. Supported by a disciplined monthly innovation cadence and early commercial wins as an anchor AI partner, these platforms serve primarily as strategic account defense mechanisms and cross-sell catalysts.
OUTLOOK & VALUATION
We expect the company’s topline to grow at a CAGR of ~13% to Rs. 19,378 Cr in CY25-28E. EBIT margin is likely to expand to a healthy level, ~13%, on account of operating leverage and a higher offshore delivery mix. Hence, with an expected net profit margin of 9.7% in CY28E, we expect the PAT and EPS to be at Rs. 1,877 Cr and Rs. 30.8 respectively. We have assigned a P/E multiple of 22.5x to arrive at a price target of Rs. 693 which provides an upside of ~38% within 24 to 36 months from the current market price of Rs. 502.
KEY RISKS
* Deal Ramp Delays & Conversion Risk: Slower-than-anticipated progress or elongated timelines in scaling large modernization programs can delay expected revenue realization.
* Macro & Client-Specific Volatility: Unforeseen softness or budget rationalization within key segments such as Global Capability Centers (GCCs) or specific banking accounts can create near-term revenue friction.
* Intense Pricing & Margin Pressures: A highly competitive, buyer-driven market environment, combined with wage hikes and seasonal working-day headwinds, could constrain near-term profitability expansion.
Please refer disclaimer at https://www.sushilfinance.com/Disclamier/disclaimer
Member : BSE/ NSE/ MSEI. SEBI Registration No.-INZ000165135