Diwali Picks 2026 : Bajaj Finance Ltd for the Target Rs.1,096 by Axis Securities Ltd
Sustained AUM Growth and Operating Leverage to Drive Earnings Compounding
Bajaj Finance is a leading diversified NBFC with a strong consumer-finance franchise, extensive distribution network and growing presence across SME, commercial, mortgage and rural lending. Its large customer base, multi-product strategy and technology-led underwriting provide structural advantages in customer acquisition, cross-selling and risk management. The company’s focus on customer centricity, technology leadership and disciplined risk management under its FY26–FY30 strategy provides a foundation for sustained growth. Strong execution across lending segments and improving operating efficiency should support earnings growth despite near-term margin and credit-cycle uncertainties.
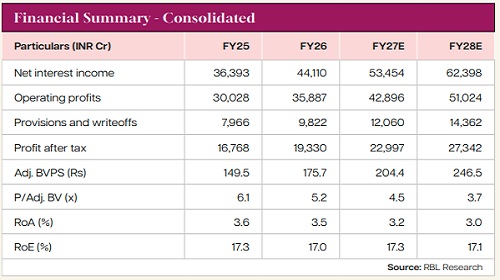
Diversified Lending Franchise to Sustain AUM Growth: Consolidated AUM grew 26.5% YoY to Rs. 5.85 lakh crore in Q2FY27, with quarterly net additions of approximately Rs. 37,680 crore. Growth remained broad-based, led by urban consumer finance (+43%), rural consumer finance (+63%), microfinance (+54%) and commercial vehicles and tractors (+89%). The customer base expanded 16% YoY to 128.85 million, while new loans booked increased 11% to 13.45 million. Management expects AUM growth of 26–27% in FY27 and anticipates an improvement in MSME growth during H2FY27, while maintaining its medium-term growth ambition of 23–25%. We estimate NII to grow at a CAGR of 18.9% over FY26–FY28E, supported by sustained AUM expansion, deeper customer penetration and cross-selling opportunities across its diversified lending franchise.
Operating Leverage to Offset Margin Pressure: NII grew 24% YoY to Rs. 13,335 crore in Q2FY27, while pre-provisioning operating profit increased 23% to Rs. 10,699 crore. The operating expensesto-net total income ratio remained controlled at 33.0%, and management expects a further 25– 40 bps improvement during FY27. Technology-led automation, AI-enabled customer servicing and cross-selling should improve productivity as the franchise scales. However, management anticipates marginal NIM compression amid further interest-rate increases and rising funding costs. Consequently, our earnings thesis relies primarily on balance-sheet expansion and operating efficiencies rather than aggressive margin expansion. These factors support our estimated 19.2% FY26–FY28E PPoP CAGR.
Disciplined Underwriting to Support Earnings Resilience: Consolidated GNPA and NNPA stood at 1.06% and 0.42%, respectively, in Q2FY27. Loan losses and provisions to average assets under finance declined to 1.56% from 1.88% a year earlier, and would have been 1.32% excluding the additional Rs. 337 crore macroeconomic provision. Management highlighted improving delinquency trends across recent loan vintages and expects the gradual run-down of its captive lending portfolio to provide further credit-cost benefits. While household leverage, unsecured lending and economic uncertainty remain monitorables, prudent provisioning and stronger underwriting should support earnings resilience. This underpins our estimated 18.9% FY26–FY28E PAT CAGR.
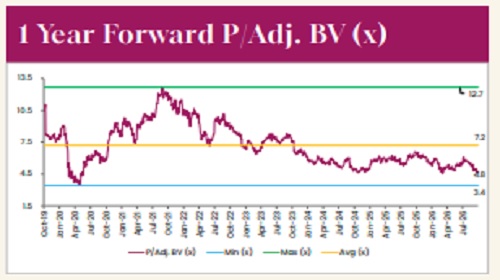
Valuation and Outlook: We initiate coverage on Bajaj Finance with a BUY rating and a target price of Rs. 1,096. We estimate FY26–FY28E CAGRs of 18.9% in NII, 19.3% in PPoP and 18.9% in PAT, driven by sustained AUM growth, a diversified lending franchise and operating leverage. Its extensive customer base and cross-selling capabilities should support growth, while disciplined underwriting remains critical to containing credit costs. Following the recent price correction, valuations offer a more favourable entry point, with the stock’s earnings growth potential providing support to the investment case. We believe Bajaj Finance is well placed to deliver sustained earnings compounding over the medium term, supporting our positive view on the stock.
For More Axis Securities Disclaimer https://simplehai.axisdirect.in/disclaimer-home
SEBI Registration number is INZ000161633