Daily Derivatives Insights September 15 2026 by Axis Securities
Nifty Futures: 23,485.2 (0.0%), Bank Nifty Futures: 56,869.2 (0.5%).
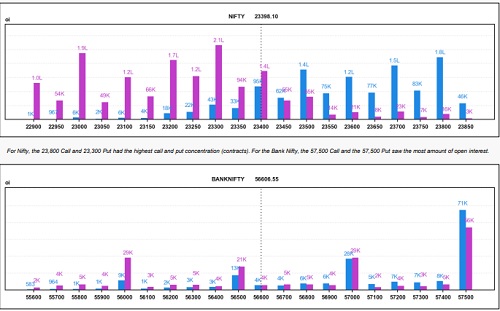
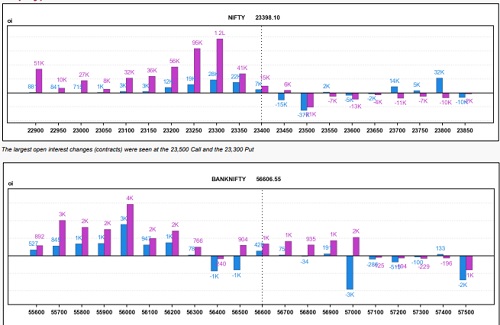
The Nifty Futures advanced 1.2 points as Open Interest contracted by 0.1 percent (down 0.15 lakh shares to 218.89 lakh), signalling mild Short Covering. Conversely, Bank Nifty Futures climbed 273.0 points alongside a 1.1 percent Open Interest expansion (up 0.26 lakh shares to 248.12 lakh), confirming resolute Long Build-up. Domestic equities resumed their downward trajectory at the opening bell, tumbling nearly one percent as Brent crude briefly spiked to 110 dollars per barrel. However, energy prices violently retraced to 105.15 dollars, permitting a substantial market recovery. Heavyweight private lenders, spearheaded by HDFC Bank, witnessed sustained institutional accumulation, establishing a structural floor that averted systemic capitulation. Capital allocators executed a panic-driven rotation, punishing structural commodities and cyclicals while retreating into financials, pharma, and technology. Meanwhile, futures carry costs inflated drastically; the Nifty premium expanded to 87 points from 6 points, and the Bank Nifty basis grew to 263 points from 124 points. Options market-makers defined ceiling resistance at 23,600 and foundational support at 23,200, witnessing simultaneous unwinding at the 23,500 strike.
Global Movers:
Wall Street benchmarks ended lower on Monday as losses in mega-cap chipmakers weighed heavily on the broader market, compounded by surging global bond yields. The technology sector took a massive hit after leaders of major artificial intelligence companies, including Anthropic and OpenAI, warned about the risks of rapid AI development and called for an industry slowdown. S&P 500 dropped 37 points (-0.48%) to close at 7,620. Dow Jones declined 152 points (-0.29%) to settle at 52,426. Nasdaq, the tech-heavy index fell 147 points (-0.55%) to close at 26,186. Energy markets spiked violently following reports of drone strikes originating from Iraq that forced the shutdown of Saudi Arabia's East-West oil pipeline. Brent crude surged nearly 3% to trade as high as $108.47 per barrel, exacerbating concerns over a prolonged conflict and instability around the critical Strait of Hormuz.
Stock Futures:
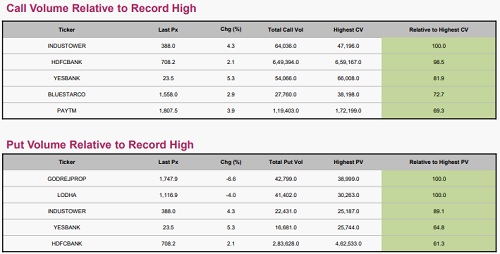
Yes Bank (YESBANK) rallied 5.8% on Long Addition, expanding futures open interest by 1.5% to 39,098 contracts with 587 added. The volume-backed rally positioned the equity among top private banking gainers, fundamentally propelled by strategic treasury maneuvers involving the mobilization of low-cost FCNR deposits via a special central bank swap window to optimize leverage and capital efficiency. The futures premium expanded to 0.29 points. A declining Put-Call Ratio (PCR) from 0.70 to 0.58 indicates heavy overhead call writing, with 4,278 new calls outpacing 1,151 puts, reflecting tactical capping despite strong spot accumulation.
One 97 Communications (PAYTM) surged 5.1% via Long Addition, driving derivative open interest up 1.5% to 25,730 contracts with 376 added. Strong bullish momentum was reinforced by a global brokerage initiating a "top pick" coverage note with an aggressive target, citing merchant lending expansion, operating leverage, and potential upside from a favourable UPI MDR framework. The futures premium expanded by 19.2 points to 21.4. A rising PCR from 0.66 to 0.78 confirms strong option flooring, backed by 3,249 new puts written against 1,125 calls, signalling robust buyer conviction.
Cochin Shipyard (COCHINSHIP) plummeted 9.0% through Long Unwinding, contracting futures open interest by 1.9% to 15,957 contracts with 313 unwound. Market participants reacted severely to management guiding normalized FY27 EBITDA margins down to ~14% (versus 17% in Q1), driven by lower expected margins in core shipbuilding (10–12%). The futures premium compressed by 7.7 points to 4.0. A sliding PCR from 0.50 to 0.45 confirms heavy tactical overhead resistance, as 8,703 new calls outstripped 3,416 puts, cementing near-term sell-side pressure.
Godrej Properties (GODREJPROP) fell 6.5% via Short Addition, pushing derivative open interest up 1.9% to 28,622 contracts, adding 546. Selling pressure was triggered by the company confirming a ?70 crore financial impact resulting from a final settlement agreement resolving a Gurugram project dispute. The basis premium expanded slightly to 19.3 points. A declining PCR from 0.63 to 0.55 highlights persistent overhead distribution and sell-side momentum, as 6,122 new calls heavily overwhelmed 2,494 puts.
Put-Call Ratio Snapshot:
The Nifty Put-Call ratio (PCR) rose to 1.01 from 0.77 points, while the Bank Nifty PCR rose from 0.86 to 0.94 points.
Stock Option Volume highlights:
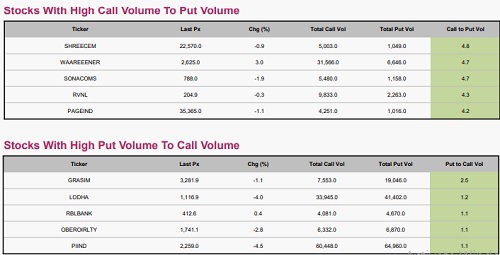
WAAREEENER (2,625.00, +3.0%) shows long build-ups; 31,566 calls top 6,646 puts (4.7 call-to-put, 0.45 PCR), targeting 2,700/3,000 resistances over 2,500/2,600 supports for the current monthly F&O expiry, signalling strong bullish accumulation. RVNL (204.90, -0.3%) marks short build-ups; 9,833 calls beat 2,263 puts (4.3 call-to-put, 0.41 PCR), sliding to 190/200 supports under 220/230 resistances for the current monthly F&O expiry, signaling rising bearish conviction. GRASIM (3,281.90, -1.1%) marks short build-ups; 19,046 puts outpace 7,553 calls (2.5 put-to-call, 0.93 PCR), sliding to 3,000/3,040 supports under 3,300/3,540 resistances for the current monthly F&O expiry, highlighting active distribution pressure. LODHA (1,116.90, -4.0%) marks short build-ups; 41,402 puts outpace 33,945 calls (1.2 put-to-call, 1.08 PCR), sliding to 980/1,000 supports under 1,200/1,300 resistances for the current monthly F&O expiry, underscoring active bearish conviction.
Stock Open Interest highlights:
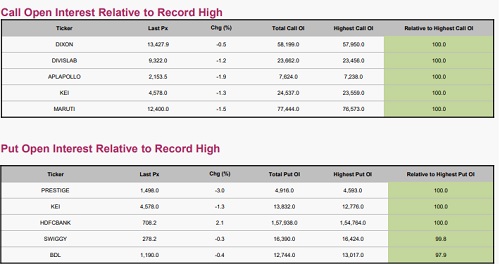
DIXON (13,427.90, -0.5%), DIVISLAB (9,322.00, -1.2%), and MARUTI (12,400.00, -1.5%) attain peak annual Call ceilings, capping upside within expiry bounds (Support: 13,000, Resistance: 15,000; Support: 9,000, Resistance: 10,000; and Support: 12,000, Resistance: 14,000) under PCRs of 0.42, 0.78, and 0.41 that signal short-accumulation, steady short-accumulation, and active short-accumulation sentiments respectively, while KEI (4,578.00, -1.3%) and HDFCBANK (708.2, +2.1%) scale their maximum yearly Put capacity alongside SWIGGY (278.2, -0.3%) which maintains Put accumulation at 99.8% of its annual ceiling, anchoring defensive downside floors (Support: 4,500, Resistance: 5,000; Support: 700, Resistance: 720; and Support: 275, Resistance: 290) where respective PCRs of 0.56, 0.53, and 0.78 validate short-accumulation, short-accumulation, and steady short-accumulation sentiments.
Participant-wise Open Interest Net Activity:
Index Futures witnessed a light turnover of 3,582 contracts, heavily defined by local proprietary desks absorbing foreign fund distribution. Proprietary traders spearheaded the long side by adding 3,065 contracts, supported by a minor 517-contract addition from retail Clients. This domestic buying provided immediate exit liquidity for a broad-based institutional pullback, cleanly absorbing supply offloaded by FIIs (-3,038 contracts) and DIIs (-544 contracts).
In Stock Futures, where 32,401 contracts changed hands, retail traders and local proprietary desks united to lead the single-stock long absorption wave. Retail Clients took dominant command of the single-stock long side by accumulating 19,515 contracts, supported by a 12,886-contract addition from Proprietary desks. This domestic buying completely underwrote the single-stock market, cleanly absorbing an aggressive, dual-institutional exit as FIIs dumped 22,318 contracts alongside a 10,083-contract distribution sweep by DIIs.
Nifty
Bank Nifty
For More Axis Securities Disclaimer https://simplehai.axisdirect.in/disclaimer-home
SEBI Registration number is INZ000161633