Wealth Building in Your 20s: Why Financial Discipline Matters More Than Income
Building wealth is often associated with earning a high salary, making large investments or owning valuable assets. However, long-term financial success usually begins with something much simpler: developing the right money habits early in life.
Your 20s can be an important period for establishing a strong financial foundation. Even with a modest income, consistent saving, responsible spending and informed investment decisions can help create financial stability over time.
Start With a Clear Financial Plan
The first step towards building wealth is understanding where your money goes. Tracking monthly income and expenses helps identify unnecessary spending and opportunities to save. Setting realistic financial goals, such as creating an emergency fund, purchasing a home or planning for retirement, makes it easier to manage money with purpose.
A simple budget can help divide income between essential expenses, savings, investments and personal spending. The objective is not to eliminate every expense but to ensure that money is being used wisely.
Make Saving a Consistent Habit
Saving should not depend on how much money remains at the end of the month. A better approach is to set aside a fixed portion of income as soon as it is received.
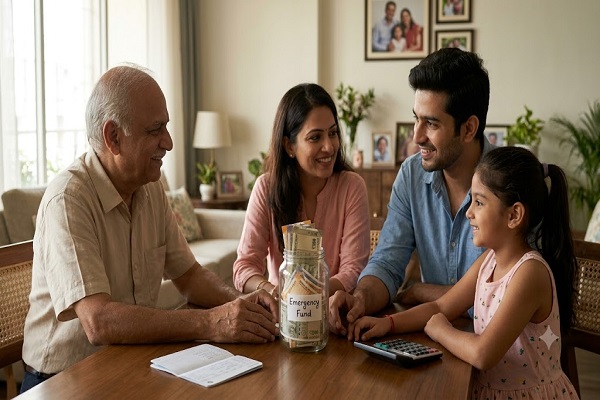
An emergency fund is also essential. It provides financial protection against unexpected expenses such as medical bills, job loss or urgent repairs. Keeping this money accessible can prevent individuals from relying on loans or withdrawing long-term investments during difficult situations.
Understand the Power of Compounding
Compounding allows investment returns to generate additional returns over time. This makes consistency and investment duration important factors in long-term wealth creation.
Starting early can provide an advantage because investments have more time to grow. However, investors should understand the risks associated with different financial products and select options based on their goals, time horizon and risk tolerance.
Mutual funds, exchange-traded funds, stocks, bonds and other investment instruments serve different purposes. Research and diversification can help investors avoid depending entirely on a single asset or market.
Avoid Lifestyle Inflation
As income increases, spending often rises as well. Upgrading gadgets, purchasing expensive vehicles and increasing discretionary expenses can gradually reduce the amount available for savings and investments.
Enjoying financial success is important, but allowing expenses to grow faster than income can make wealth creation difficult. Maintaining a balance between present needs and future financial goals is a key part of financial discipline.
Focus on Financial Knowledge
Financial markets and investment products can appear complicated, particularly for beginners. Understanding basic concepts such as inflation, interest rates, taxation, asset allocation and risk management can improve financial decision-making.
Investors should also be cautious about guaranteed high-return promises and unverified investment advice. Making decisions based on research rather than short-term excitement can help reduce avoidable financial mistakes.
Conclusion
Building wealth is not necessarily about becoming rich quickly. It is about making informed financial decisions consistently over many years. Starting early, saving regularly, investing according to personal goals and controlling unnecessary expenses can create a stronger financial future.
Ultimately, financial discipline is not determined by how much a person earns but by how effectively they manage the money they have.