The Eagle Eye : Global macro clouds deepen as FII selling resurfaces - Motilal Oswal Financial Services Ltd
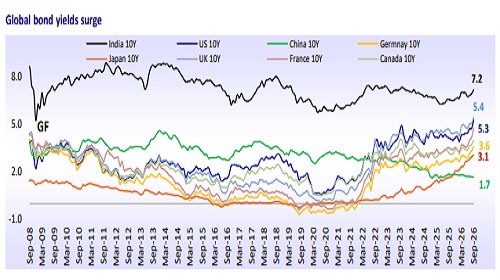
Rate hikes begin, pushing global bond yields to multi-year highs
* As inflation outpaces the central banks’ comfort zones, major central banks have begun tightening their monetary policies.
* The Fed/ECB/BoJ have already hiked rates following concerns over energy-driven inflation. These major central banks hiked rates by +25bp each, to 3.75%-4.00%/2.50%/1.25%, respectively.
* Global tightening of monetary policies is increasingly visible in the bond markets, as 10Y government bond yields reach multi-year highs across major economies. UK/US/JPN/GER/IND yields stands at 5.4%/5.3%/3.1%/3.6%/7.2%.
* The RBI’s upcoming 7th Oct’26 MPC meeting has the market in wait-and-watch mode, as the five-meeting repo rate hold may be accompanied by a hawkish stance (+25bp to 5.50%). The stance is likely to reflect inflation expectations of above 6% in 3QFY27, meaningfully above the RBI’s projection of 5%, as elevated food and energy prices continue to pressure Indian markets.
MSCI EM weights: India, China at multi-year lows, while Taiwan, Korea at highs
* The ongoing correction in Indian equities, particularly in heavyweight stocks, along with continued weakness in China, has led to a sharp decline in their respective weights in the MSCI EM Index, with India falling to a near six-year low and China to a more than a decade-low level.
* In contrast, Taiwan and Korea have continued to gain weight, driven by strong performance in AI-led semiconductor and chip manufacturing stocks. Their sharp market gains have lifted their index weights, with the combined weight of Taiwan and Korea now surpassing that of India and China.
* The shift is particularly striking as TSMC, Samsung Elec. and SK Hynix together account for ~28% of the MSCI EM Index, more than twice India’s weight. Taiwan has emerged as the largest EM market, reflecting the growing influence of AI-driven semiconductor demand on the index.
Elevated commodity prices pose an extended margin risk
* Crude prices have spiked since Feb’26 and remain elevated amid West Asia tensions and supply disruptions, raising concerns over growth, current account deficit (CAD), inflation, INR depreciation, and fiscal balances.
* Rise in HRC and TMT prices to nearly four-year highs can benefit metal companies; however, it may put pressure on margins for companies that use metals as inputs.
Market returns cool off sharply, improving risk-reward and reversion potential
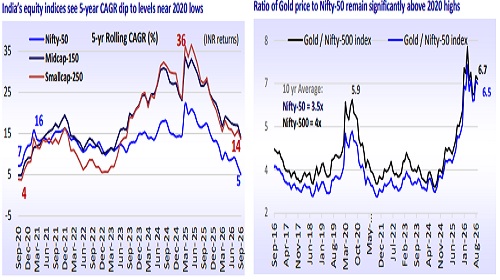
* Two years of market consolidation and correction have significantly cooled key return indicators from their highs, with several now approaching the 2020 lows.
* India’s five-year rolling returns, Gold-to-equity return ratio, sharp underperformance vs. MSCI EM, and valuation correction suggest that the period of market underperformance has persisted, improving the potential for mean reversion and creating a more favorable risk-reward profile.
* As global headwinds stabilize, these indicators could support a reversal in India’s relative market performance.
SMIDs’ share of Indian market cap at an all-time high
* Ongoing underperformance in Indian Large-caps, alongside strong investor interest in Mid- and Small-cap companies across emerging and highgrowth sectors, has driven a significant shift in market capitalization toward SMIDs. Consequently, the combined market-cap share of SMIDs reached an all-time high of 43.7% in Sep’26, while the Large-cap share dipped to a fresh low of 56.3%.
For More Research Reports : Click Here
For More Motilal Oswal Securities Ltd Disclaimer
http://www.motilaloswal.com/MOSLdisclaimer/disclaimer.html
SEBI Registration number is INH000000412