FOMC: Take a hike! by Emkay Global Financial Services Ltd

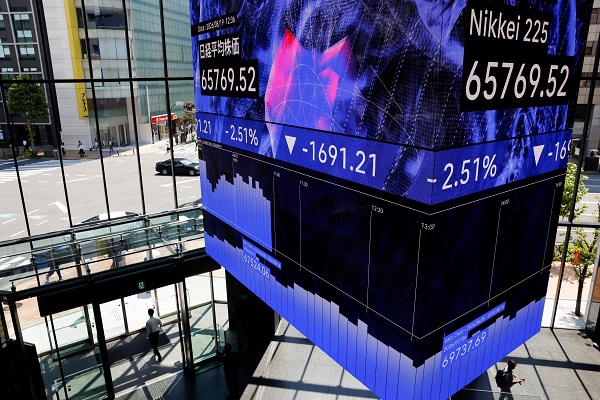
* September marks an inflection point for a broad DM hiking cycle, with the Fed joining the ECB, BoJ, RBA, RBNZ, and Norges Bank on tightening paths. As widely expected, the Fed hiked 25bps, with policy signaling that this cycle will continue and one more hike is likely in Dec-26. The Fed’s renewed inflation focus drove front-end US yields and the dollar higher, while US shares retreated.
* Two other elements of the decision tilted the outcome hawkish. First, the vote was unanimous – a signal that bolsters institutional independence and the new Chair's leadership. Second, there was broad support for further hikes: the median dots project one more 25bp hike this year, with only two committee members projecting none (Chair Warsh did not submit a dot).
* For 2027, the median projection is for rates to hold steady, flanked by eight dots favoring additional hikes against just four expecting easing. This marks a notable shift from Jun-26, when the median FOMC voter anticipated only one hike this year, expected to be reversed in CY27.
* The Summary of Economic Projections (SEP) depicted the Fed still sees a resilient economy, and a gradual descent in inflation, nudging forecasts for growth higher and unemployment rates lower. However, even with an upward revision in the neutral policy rate to 3.25%, the SEP continues to expect inflation to fall sharply next year. Core PCE inflation is expected to drop from 3.4% in 2026 to 2.5% next year, unchanged from Jun-26. This immaculate disinflation path puts a lot of weight on the transitory supply-side elements of inflation fading.
* Reduced to just 30 minutes, Chair Warsh's presser was less eventful than in Jul-26. A few times he was asked about what rate hikes would do to offset inflation driven by supply shocks and on short-run vs long-run neutral rates, but he did not directly answer either question.
* Warsh strongly indicated that he sees no operational value in the concept of a neutral rate – yet his repeated comment, both in prepared remarks and in Q&A, that this hike removes ‘accommodation’ belies an implicit neutral rate in his thinking. Warsh also expressed distaste for ‘data dependency’, presumably meaning too much weight placed on any single month of data – a view shared by most. Instead, he pointed to 6M and 12M run-rates of PCE inflation as the better gauge of his preferred ‘trend’ measure, which seems to guide him more.
Synchronized DM, fragmented EM on rate cycle; RBI likely to act in Oct-26
Looking ahead, as we mark an inflection point DM hiking cycles this month with nearly all key CBs acting, markets are currently focused on the latest inflation data and the recent spike in oil prices driving the hiking cycle. However, we feel the underlying driver of this shift toward hiking is growing evidence that current policy rates may not be restrictive enough to contain a cyclical upturn and its pass-through to inflation.
The path forward for EM central banks is far less uniform. Domestic conditions are driving considerable divergence across countries: this week, Brazil remains on an easing path, while Taiwan is likely holding steady, supported by the AI-led growth boom and ongoing disinflation. India, meanwhile, saw an upside surprise in Aug-26 core CPI last week – the final tipping point after hawkish MPC minutes, the recent spike in energy prices, and firmer-than-expected growth. A 25bp hike in Oct-26 by the RBI looks more likely, but we also expect this to be a shallow hiking cycle (50-75bps) and will await more clarity at the Oct-26 review.
For More Emkay Global Financial Services Ltd Disclaimer http://www.emkayglobal.com/Uploads/disclaimer.pdf & SEBI Registration number is INH000000354