DSP Mutual Fund's Tathya: A high frequency macro dashboard
Key highlights:
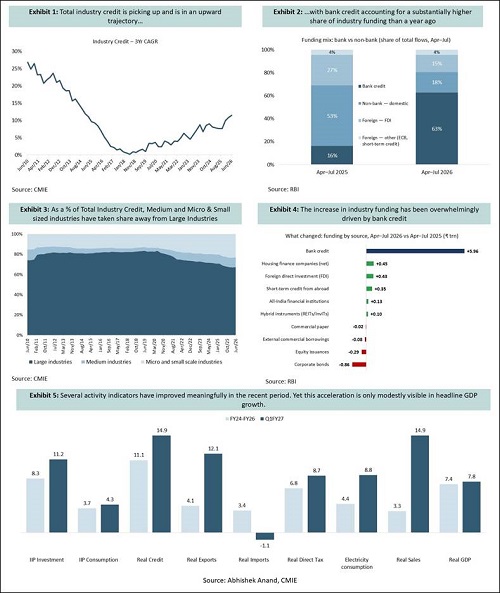
* The double-digit YoY growth in several demand indicators continues to be aided by a favorable base. On an absolute basis, consumption indicators have improved, but the pickup remains uneven across segments.
* Manufacturing continues to fare reasonably well. Credit growth, capital goods production and infrastructure activity remain considerably stronger than they were a year ago. However, manufacturing PMI has softened recently while WPI remains elevated.
* The indicators below have shown some pickup compared to the past year (compare absolute 12M avg numbers with the past year). The improvement is more visible in credit-related indicators than in services activity indicators. Notably, housing loans, a segment that had held up well, continues to hover around low double-digit growth.
* Expenditure and revenue profiles, have not picked up meaningfully as compared to the past year (compare absolute 12M avg numbers with the past year).
* We are comfortable, as far as liquidity is concerned. However, we should not confuse this with comfortable money supply.
India needs higher credit growth.
* Despite higher crude prices, India's external position remains considerably more comfortable than what the trade deficit alone would suggest. Forex reserves remain near historical highs and continue to provide resilience against external volatility.
* When valuations for India equities were sky high, we highlighted how fragile the system had become to foreign investment outflows. Today we are at the other end.
It is at such valuations that the environment becomes particularly conducive to flows. But MF equity flows, which remained rather strong through most of the bull market, have begun to look patchy now.
Above views are of the author and not of the website kindly read disclaimer



Tag News
Baroda BNP Paribas Asset Management India announces closure of OPAT