Diwali Muhurat Picks 2026 : Buy Viyash Scientific Ltd for the Target Rs.314 by Sushil Finance
INDUSTRY DYNAMICS FAVORABLE FOR THE GROWTH
The most potent catalyst for the Indian CDMO sector is the implementation of the United States BIOSECURE Act. This legislation aims to restrict US entities from utilizing federal funds to procure biotechnology equipment or services from specific foreign adversarial companies, citing national security concerns. The Act explicitly targets prominent Chinese CDMOs and genomics firms, including WuXi AppTec, WuXi Biologics, BGI, MGI, and Complete Genomics. China currently commands a 30% to 35% share of the global API and CDMO market, representing roughly US$ 60 billion to US$ 75 billion in annual revenue. So even a fraction shift in the market share to India, should benefit the Indian companies.
Global pharmaceutical innovators and large generic conglomerates are under immense pressure to decouple their supply chains from Chinese manufacturers due to geopolitical tensions and environmental disruptions. By offering a fully localized, USFDA-compliant manufacturing ecosystem rooted in India, Viyash secures long-term, high-volume contracts by guaranteeing supply security to its partners
BACKWARD INTEGRATION AND PRODUCT AND GEOGRAPHIC EXPANSION TO DRIVE GROWTH
While near-term growth is supported by existing capacity, backward integration and volume optimization, the true structural inflection in Viyash’s earnings profile is back-ended and tied to its complex R&D engine. The company has deliberately pivoted away from commoditized, high-volume generic APIs toward high-barrier, complex therapeutic areas such as oncology and central nervous system (CNS) treatments. Developing these highly potent active pharmaceutical ingredients (HPAPIs) and cytotoxic drugs requires specialized containment infrastructure (OEB-4/5 levels) and a long gestation period, typically taking five to seven years from development to commercialization. The company has guided for a revenue of $1bn by 2032 and a $150-200 mn companion ambition for the long term with high potency API launches around 2029, while it is confident to achieve Rs.4000 cr in FY27, with improving margins due to focus on high potent APIs.
OUTLOOK & VALUATION
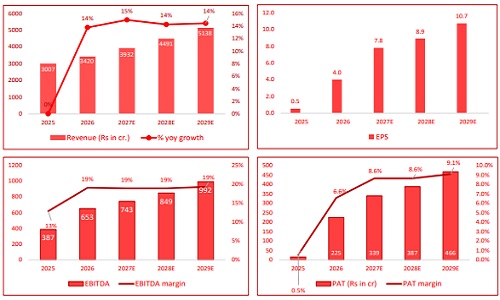
We expect the company’s topline to grow at a CAGR of ~15% to Rs. 5,138 cr in FY26-29E. On conservative basis, we have expected EBITDA margin to remain at healthy level, 19%. Hence, with an expected PAT margin of 9% in FY29E, we expect the PAT and EPS to be at Rs. 466 cr and Rs. 10.7 respectively. We have assigned a P/E multiple of 30x to arrive at a price target of Rs. 314 which provides an upside of ~35% within 18 to 24 months from the current market price of Rs.232.
Carlyle-backed Viyash Scientific Ltd is an integrated global pharmaceutical company formed by the merger of Sequent Scientific, India’s largest pure-play animal health company, with Viyash Life Sciences, creating a single listed entity spanning APIs, formulations and CDMO across more than 150 countries.
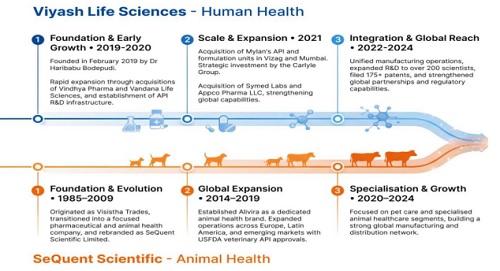
SeQuent's line runs back to 1985. The company "originated as Visistha Trades, transitioned into a focused pharmaceutical and animal health company, and rebranded as SeQuent Scientific Limited. From 2014, it built the Alivira animal health brand and expanded across Europe, Latin America and emerging markets with USFDA veterinary API approvals, then spent 2020–2025 deepening its geographic and specialty footprint. Global private equity firm Carlyle took a majority stake in September 2020 and held ~53% as of March 2025.
Viyash is the newer strand. Dr Haribabu Bodepudi, a PhD in organic chemistry who spent ~20 years at Mylan rising to Global COO and CEO of Mylan India, founded Viyash Life Sciences in February 2019 alongside Dr Srihari Raju Kalidindi 56. It grew fast through acquisitions: Vindhya Pharma and Vandana Life Sciences in 2019–20, then in 2021 Mylan's API and formulation units in Vizag and Mumbai, a strategic Carlyle investment, and Symed Labs and Appco Pharma.
The merger that created today's company
Announced in September 2024: SeQuent and Viyash proposed a strategic merger to create "a global animal health leader with endto-end integrated capabilities”. The through-line is integration: a 1985-born animal health specialist and a 2019-born human pharma challenger, both Carlyle-backed, merged into one company that makes its own active ingredients, turns them into finished doses in its own plants, and sells them through its own distribution across four continents
Management quality
• Dr. Haribabu Bodepudi: MD & Group CEO: PhD in Organic Chemistry, with decades at Mylan, rising to CEO of Mylan India and Global COO of Mylan. He built Mylan’s ARV business to over 50% market share.
• Mr Rajaram Narayanan: Whole Time Director & CEO-Animal Health: MBA from IIFT Delhi, and an Advanced Management Program from Harvard Business School, joined Sequent’s board in April 2022, previously MD of Sanofi India, Chief Marketing Officer at Airtel, and 18 years at Hindustan Unilever building consumer brands across India and Asia.
Viyash leverages shared research and development resources and manufacturing scale to drive substantial operating leverage. The business model is segmented into four primary, synergistic verticals.
The Human Active Pharmaceutical Ingredients (APIs) and Intermediates division represents the historical core and a continued growth engine. This division focuses on highly complex therapeutic areas including oncology, immunology, cardiovascular, central nervous system (CNS), and anti-infectives. Management has diverted from low-margin, high-volume commodity APIs, toward complex synthetic chemistry. The division's product pipeline features molecules targeting patent expiration cliffs between 2030 and 2040, positioning Viyash for "Day 1" commercial launches that capture peak generic pricing and maximize market share.
The Animal Health division, encompassing both Veterinary APIs and Formulations, originates from the legacy Sequent Scientific business and operates via the globally recognized 'Alivira' brand. While historical revenues in this segment were stagnant at approximately Rs.350cr annually for several years, recent strategic overhauls have resulted in a breakout to a >Rs.400 cr run rate. The formulation portfolio spans injectables, oral solutions, powders, and premixes, serving both production livestock (farm animals) and the rapidly expanding companion animal market across more than 100 countries.
The Custom Development & Manufacturing Services (CDMO/CRO) segment operates at the highest end of the value chain. Currently generating Rs.200 cr in annual revenue, this segment functions under three distinct engagement models: NCE (New Chemical Entity) development for innovators moving from Phase III clinical trials to commercialization; lifecycle management for post-patent innovator molecules; and specialty generic contract manufacturing for global pharmaceutical firms lacking complex in-house infrastructure. Backed by rigorous Intellectual Property (IP) protection protocols, specialized cytotoxic containment suites, and a flawless regulatory track record, Viyash commands deep client stickiness among top-tier global generic and innovator companies.
The Finished Dosage Formulations (FDF) division captures the final margin profile of the value chain. Viyash’s human formulation business is anchored by its US-based subsidiary, Appco Pharma LLC, which is supported by low-cost, vertically integrated API manufacturing in India. For Animal Health, the formulation manufacturing footprint is geographically decentralized across Spain, Turkey, and Brazil (with EU-GMP and local GMP certifications) to cater seamlessly to regional demands and facilitate rapid geographical extension of existing dossiers
Industry dynamics favorable for the growth
The global pharmaceutical industry is undergoing a structural change generating a multi year tailwinds for integrated Indian players possessing complex capabilities. The driving force for the change is the geopolitical push to de-risk supply chains away from the Chinese reliance, recently codified in the US BIOSECURE ACT. Global innovators and top-tier generic firms are aggressively auditing Indian CDMOs to secure alternative, compliant capacity. Viyash’s flawless USFDA track record across 10 facilities makes it a primary beneficiary of this shift. Crucially, the manufacturing of OEB 4/5 cytotoxic compounds has historically been heavily concentrated in China; Viyash’s dedicated Taloja and Vizag containment sites position the company to make the most of the opportunity.
Concurrently, the global pharmaceutical industry is facing an unprecedented "Patent Cliff" / Loss of Exclusivity (LOE) cycle, with hundreds of billions of dollars in branded drug revenues going off-patent between 2026 and 2030. Viyash’s R&D engine is heavily geared toward this cliff. Management has confirmed that over 50% of their human API development pipeline consists of "First-toFile" or "Day 1 Launch" opportunities. The molecules are highly complex (mostly oncology and high potent drugs), where post patent price erosion is typically contained to 50-60% compared to 95% erosion witnessed in commoditized oral solid dosages
Global Animal Health Sector Trends
The global Animal Health market represents an approximately US$ 56 bn opportunity, structurally divided into livestock and companion animal segments. The livestock segment, commanding roughly 60% of the market, is driven by secular trends in global protein consumption, intensive farming practices, and stringent governmental mandates to prevent infectious disease outbreaks. The veterinary pharmaceutical sector is exhibiting secular, non-cyclical growth characteristics, primarily driven by the companion animals. Pet animal ownership has shot up post-Covid 19; Europe alone boasts over 186 million cats and dogs (94 million dogs and 92 million cats in the US market alone). While the human generic market is heavily saturated, generic penetration in the companion animal space remains nascent, hovering around a mere 15%. As pet populations grow and veterinary care costs rise against a backdrop of structurally low insurance coverage (only ~15% in Europe), consumers are being forced toward affordable generic alternatives. Viyash has presence in the animal API portfolio, is aggressively forward integrating this advantage into finished dosages to capture the entire value chain. Unlike human generics, animal health generics retain superior pricing power, often stabilizing at 60-70% of the innovator's original price, ensuring robust, long-tailed margin profiles
Backward and Product and Geographic expansion to drive growth
The company has established a formidable backward integration and chemistry moat. Through an aggressive network optimization strategy over the past two years, management has achieved greater than 85% backward integration across its key molecules, substantially reducing reliance on external Key Starting Materials (KSMs). This structural shift from raw material sourcing to in-house manufacturing severely insulates gross margins against generic price erosion and supply-chain volatility, a fact validated by the 321 basis point gross margin expansion observed in FY26. Annualized operational synergies of Rs.50-60 cr are already being realized through plant rationalization and corporate function consolidation, with management expecting this to scale toward Rs.125-150 cr over the next 12 to 18 months. Furthermore, the company’s advanced chemistry capabilities—specifically its OEB 4/5 containment facilities for highly potent APIs (HPAPI) and cytotoxic compounds—create prohibitive barriers to entry. The technical complexity required to operate these facilities at scale secures Viyash’s position as a preferred partner for global innovators facing complex chemistry challenges
Second, Viyash operates a de-risked, dual-engine business architecture that balances human health CDMO operations with a rapidly scaling animal health formulation business. The amalgamation of Viyash Life Sciences and Sequent Scientific, formalized via a National Company Law Tribunal (NCLT) order on November 18, 2025, has resulted in an integrated pharmaceutical powerhouse. The resulting entity, Viyash Scientific Ltd, is no longer a fragmented, commoditized Active Pharmaceutical Ingredient (API) manufacturer but a sophisticated global Contract Development and Manufacturing Organization (CDMO) and specialty pharma platform. The human health division is aggressively targeting high-margin CDMO revenues, with management guiding for 40% growth in innovator lifecycle management contracts in FY27.
The Animal Health division (operating under the Alivira brand) is executing a strategic pivot from low-margin production animal products to high-growth companion animal therapeutics. The companion animal market in Europe represents an addressable market of approximately $1 bn (excluding vaccines). This market is characterized by low insurance penetration (around 15%), which naturally drives volume toward affordable branded generic options as pet ownership increases. Unlike human generics, which face up to 95% price erosion upon loss of exclusivity, animal health generics typically experience a much shallower 30-40% price erosion, thereby preserving long-term profitability and extending the lifecycle of the product portfolio. Capital allocation remains highly strategic, evidenced by the October 2026 acquisition of BioForLife Italia for an upfront consideration of EUR 15 mn. With reported CY25 sales of EUR 9 mn, this asset serves as a direct, high margin launchpad for Viyash’s proprietary companion animal portfolio into Europe's lucrative veterinary clinic channels
KEY RISKS
1.Regulatory & Quality Compliance Risk: Viyash’s investment thesis is highly levered to its flawless regulatory record across 10 USFDA-approved sites. The US generic pipeline hinges heavily on the Vizag and Taloja facilities. Any escalation of routine FDA observations into Official Action Indicated (OAI), Warning Letters, or Import alerts would instantly paralyze the high-margin US human and animal API revenue streams
2.Raw Material Volatility & Freight Costs: Despite achieving 85% backward integration, Viyash relies heavily on bulk solvents. Management acknowledged minor impacts from geopolitical freight disruptions and solvent price volatility in late FY26. Prolonged geopolitical shocks could squeeze gross margins if the company loses pricing power against large generic buyers.
3. Foreign Exchange Exposure: With manufacturing facilities in Turkey and Brazil, Viyash is exposed to severe emerging market currency volatility. Specifically, hyperinflationary accounting dynamics in Turkey represent an ongoing translational risk to reported INR revenues and earnings, necessitating rigorous, proactive FX hedging postures
Please refer disclaimer at https://www.sushilfinance.com/Disclamier/disclaimer
Member : BSE/ NSE/ MSEI. SEBI Registration No.-INZ000165135