Commodity Weekly Insights 17 November 2026 by Geojit Investments Limited

LME zinc continued to trade near its yearly highs, supported by persistent supply tightness across the global market. Production disruptions at key mines and smelters, along with historically low treatment charges, have constrained refined metal output and reinforced concerns over raw material availability. With the zinc market remaining in deficit and supply recovery progressing slowly, prices have continued to find support despite periodic profit-taking and broader market volatility.
• LME zinc futures steadied after easing from yearly highs marked in September, and hovered above USD3700 per metric tonne.
• In MCX, zinc futures posted a second monthly decline from all time high hit on September posting a decline of more than 3% over the last monthly period.
• LME zinc inventories have recovered from their multi-year lows; however, persistent physical market tightness and constrained refined metal availability continue to draw down stocks, highlighting the underlying supply deficit in the zinc market.
• China's producer inflation accelerated to 5.7% in October, marking its fastest pace in nearly four-and-a-half years, as higher global oil prices drove up manufacturing costs.
• India's Hindustan Zinc plans to expand its annual production capacity to 2 million tonnes from the current 1.1 million tonnes over the next three years.
• Most global benchmark equity indices finished the week in positive territory, except China’s SSE index.
• The U.S. Dollar Index jumped above 103 marks, gaining more than 1% against major counterparts, as Fed rate hike hopes increased.
• The Euro and Japanese Yen slipped lower while Chinese Yuan moderated against USD last week.
• The Indian rupee weakened against the U.S. dollar last week.
Zinc Prices Retreats from 4-Year High, Supply fears Still Persist
LME zinc futures surged above USD 3860 per tonne in late October before retreating, though prices continue to remain elevated above USD 3700 per tonne, supported by ongoing concerns over mine supply constraints and tightening availability outside China. Meanwhile, MCX zinc futures are on track for a second consecutive monthly decline after touching a record high in September. The zinc market has remained underpinned by persistent supply-side challenges, with the effects of the May supply shock continuing to ripple through global supply chains. Shrinking mine supply has driven treatment charges to record lows, squeezing smelter margins and prompting cutbacks in refined zinc production, thereby reinforcing supply tightness across the global market. These challenges have been further exacerbated by fresh disruptions in China, where mine output adjustments and scheduled smelter maintenance are expected to remove nearly 2500 tonnes of zinc production in the near term.
Supply-side pressures have also been evident among major global producers. Glencore reported a 21% year-on-year decline in own-sourced zinc production during the first half of 2026, although the company maintained its full-year production guidance. Meanwhile, Boliden's zinc concentrate production fell 16.8% quarter-on-quarter, while MMG recorded a 1% year-onyear decrease in zinc production during the second quarter. These production setbacks have contributed to concerns that mine supply may struggle to keep pace with demand growth.
Fundamental market balances continue to indicate a supply deficit. Global refined zinc production totaled 5.82 million tonnes during the January-May period, while apparent consumption reached 5.96 million tonnes. As a result, the zinc market recorded an implied deficit of 141564 tonnes over the first five months of the year.
Although the current deficit remains significant, it represents an improvement compared to previous periods. The market deficit stood at 169528 tonnes during the corresponding period last year, while the full-year deficit in the previous year reached 298575 tonnes. The narrowing deficit suggests that supply conditions have improved somewhat; however, the market remains undersupplied, providing continued support to prices.
Zinc Inventory levels LME zinc stocks continued to tighten after a recovery over the last two months, with inventories falling by 5100 MT week on week to 141275 MT, whereas SHFE warehouse inventories edged fell by 6275 MT to 120166 MT.
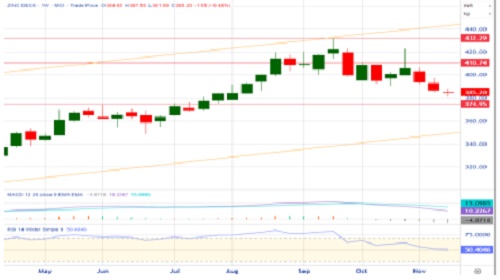
MCX: MACD bearish divergence and a neutral RSI suggest underlying weakness in the near term. Sustained trading above the Rs.375 level could support a recovery, while a break below this mark may intensify downside pressure.
SHFE: Prices may attempt a recovery if they hold the support at CNY 24300 level. However, a high-volume decline below this support could invite mild bearish pressure in the near term.
For More Geojit Financial Services Ltd Disclaimer https://www.geojit.com/disclaimer
SEBI Registration Number: INH20000034