Buy Tata Motors Ltd For Target Rs.482 By Geojit Financial Services Ltd
Volume-Led Growth; Iveco Unlocks Next Leg
Tata Motors Ltd is a leading automobile manufacturer in India that designs, manufactures and sells commercial vehicles (CVs).
* Consolidated revenue rose 19.3% YoY to Rs. 20,667cr in Q1FY27, driven by stronger domestic/export CV volumes.
* Commercial Vehicle revenue increased 19.8% YoY to Rs. 20,384cr, led by strong CV wholesales, resilient freight demand, new launches and export growth.
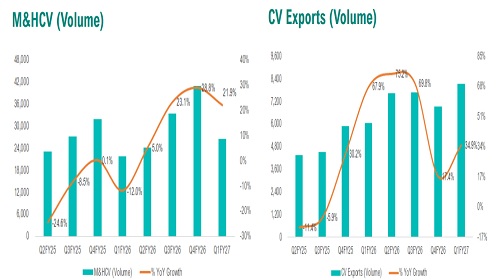
* Total CV sales grew 26.7% YoY to 108,488 units, supported by broad-based CV demand and export traction, including Indonesia-related orders.
* EBITDA rose 8.3% YoY to Rs. 2,145cr; however, EBITDA margin declined 106bps YoY to 10.4%, primarily due to commodity inflation in steel, aluminium, copper and other raw materials.
* Adjusted profit after tax (PAT) increased 5.7% YoY to Rs. 1,484cr, driven by volume growth and lower finance costs.
Outlook & Valuation
Tata Motors delivered a healthy performance in the quarter, driven by broad-based volume growth across all segments, strengthened eCV leadership, successful new product launches in the SCV portfolio and market share gains YoY. Near-term demand remains healthy, with management guiding for double-digit YoY volume growth in Q2FY27. The Indonesia order is expected to be fulfilled over the next two years, EV supply-chain debottlenecking is anticipated to be complete shortly, and the Iveco tender offer is expected to close in the coming months. Further, the Fleet Edge-Freight Tiger integration and new platform launches across ICE, CNG and EV segments are expected to support business growth. Additionally, management noted that demand post September is expected to pick up strongly as tipper utilisation recovers after the monsoon and infrastructure activity resumes. The company has secured final clearance from the European Central Bank for the €3.8 bn Iveco acquisition. We have upgraded our rating on the stock to BUY from HOLD, with a target price of Rs. 482 based on SOTP valuation.
Key highlights
* Freight Tiger became a subsidiary after the acquisition of an additional 18.1% equity stake in May 2026 for Rs. 95.66cr, taking total holding to ~63.6% from earlier minority position.
* Tata Motors initiated deliveries for its Indonesian order of 35,000 units each of the Yodha and the Ultra T.7 during Q1FY27, with ~2,000 vehicles shipped and consistent ramp-up post-quarter.
* The Lucknow plant crossed its cumulative production milestone of 10 lakh CVs in Q1FY27, demonstrating long-term manufacturing scale and operational capability.
* About 4,500 government CV passenger orders remain on hand for delivery during Q2FY27, spanning defence and state transport undertaking requirements and including 850 e-buses.
* The company is expected to deliver healthy double-digit YoY volume growth in Q2FY27, based on strong recent demand trends; H2 outlook depends on September onwards post-GST correction base comparison.
* Commodity cost pressure is expected to continue in Q2FY27, particularly in steel, rubber and other raw materials; management is confident that price hikes and internal cost actions will offset the headwinds.
* Tata Motors announced it has obtained every regulatory clearance needed for its €3.8 bn Iveco Group takeover, with the European Central Bank granting final approval covering Iveco's French financial services units.
For More Geojit Financial Services Ltd Disclaimer https://www.geojit.com/disclaimer
SEBI Registration Number: INH200000345