Buy DCX Systems Ltd For Target Rs.192 by Choice Institutional Equities Ltd
Order Book Supports Visibility; Profitability Remains Weak
DCX Systems reported a consolidated revenue of INR 1,402 Mn in Q2FY27, declining 27.3% YoY, while its net loss narrowed down to INR 3 Mn (from INR 90 Mn in Q2FY26). Despite the improvement in reported loss, consolidated operating profitability remains weak.
As of September 2026, the consolidated order book stood at approximately INR 3,190 Cr (4.3x FY26 revenue), providing mediumterm revenue visibility. The company operates across system integration, cable and wire harness manufacturing and electronic manufacturing services (EMS), supported by relationships with global defence OEMs, including Israel Aerospace Industries (IAI). Its increasing focus on nonoffset projects and backward integration through Raneal Advanced Systems are also noteworthy. However, the pace of order execution and conversion of the order book into profitable revenue remain key monitorables.
We have shifted our valuation methodology from P/E to EV/Sales, as weak and volatile consolidated earnings make earnings-based valuation less meaningful at the current stage. We value the company at 1.0x average FY28E–FY29E revenue, arriving at a revised target price of INR 192 (INR 150 earlier). Accordingly, we upgrade our rating to ‘BUY.’
The sizeable order book of INR 3,190 Cr provides a strong execution opportunity, while the significant narrowing of consolidated losses indicates early signs of a profitability recovery. We believe a transition to consolidated profitability, alongside improved order execution, could unlock significant upside potential. Further clarity on the sustainability of the recovery and execution trajectory remains key.
Revenue and EBITDA Miss Estimate; Margin Improves Sequentially
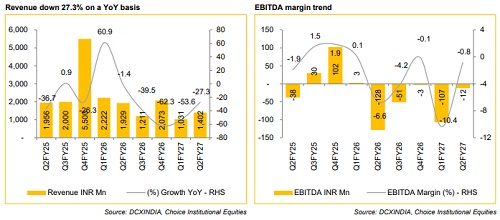
* Revenue for Q2FY27 was down 27.3% YoY and up 35.9% QoQ at INR 1,402 Mn (vs CIE estimate of INR 2,160 Mn)
* EBIDTA came at INR -11.9 Mn (vs CIE est. of INR 6 Mn). EBITDA margin stood at -0.6%, expanding by 176 bps YoY and 825 bps QoQ (vs CIE estimate of 0.3%)
* PAT came in at INR -2.6 Mn (vs CIE estimate of INR 60 Mn). PAT margin improved by 152 bps YoY and 703 bps, reaching -0.1% (vs CIE estimate of 2.8%)
For Detailed Report With Disclaimer Visit. https://choicebroking.in/disclaimer
SEBI Registration no.: INZ 000160131