Automobiles Sector Report :Strong pre-festive season demand across segments By Motilal Oswal Financial Services Ltd
Growth likely to moderate amid high base
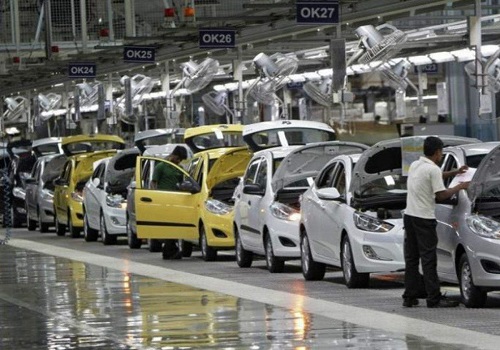
* The Sep’26 YoY growth rates across segments remained strong, aided by a low base last year as OEs deferred dispatches to take advantage of GST rate cuts. ICE 2Ws recorded ~11% YoY growth for the month, while PVs posted ~22% YoY growth. For 2QFY27, PVs clocked a strong 31.2% YoY growth, CVs posted a ~29% YoY growth, while ICE 2Ws lagged with a 10.4% YoY growth.
* As the GST rate cuts came into effect toward the end of Sep’25, a low base aided strong 1HFY27 growth rates. ICE 2Ws experienced a 13.4% YoY growth, relatively underperforming the other segments, while PVs and CVs registered a strong showing with 28.3% and 23.8% YoY growth, respectively. However, going forward, these growth rates are expected to moderate as the base catches up.
* The 2W sales underperformed mainly due to lower growth in the motorcycle segment (on account of higher Sep volumes from Hero). Tepid growth rates in the economy segment as a result of shifting consumer preferences were a drag on overall motorcycle wholesales (+10%), while ICE scooters (+19%) continued their strong outperformance.
* In the 2W ICE segment, EIM (+23%), TVSL (+18%), and HMCL (+14%) outperformed other top players during 1HFY27. HMSI posted a slightly slower growth of 13% YoY, while BJAUT was the only player to post a YoY dip of 7.2%.
* PV growth during 1HFY27 was largely led by the UV segment (+31%) although passenger cars also posted a strong 23% YoY growth. UV mix currently stands at 67.6%, up ~160bp YoY.
* In PVs, TMPV (+43%), MSIL (+36%) and Kia (+29%) outperformed peers during 1HFY27 while MM (+20%) and Hyundai (+12%) underperformed due to supply constraints and production issues.
* Strong YoY CV growth of 24% was mainly on account of ~30% YoY growth in MHCVs goods segment, while the MHCV passenger segment was a key laggard with only ~12% YoY growth. LCVs on the other hand saw broad ~22% YoY growth in both goods and passenger segments.
* TMCV (+28%) and AL (+24%) were the key outperformers in the broader CV segment, while MM (+19%) underperformed. Market share remained broadly stable among the top four players in 1HFY27.
* Our top OEM picks are MM, MSIL and TVSL. Among auto ancillaries, our top picks are MSWIL, SAMIL, SPR, TENNIND, and HFL.
ICE 2Ws: Scooters drive 2W growth, while motorcycles underperform
* Domestic 2W ICE sales grew ~11% YoY in Sep’26 and a 10.4% YoY during 2QFY27. While scooters and mopeds posted a healthy 15.4% YoY growth each, motorcycles relatively underperformed with a 7.4% YoY growth for the quarter.
* Motorcycles grew 2.8% YoY in Sep’26, largely impacted by a sharp ~19% YoY decline in BJAUT’s wholesales. Scooters on the other hand saw a strong 28.2% YoY growth for the month, far outperforming the other two segments. Mopeds posted a relatively flattish 3.3% YoY growth.
* Consequently, RE, HMCL, and HMSI gained ~30bp/50bp/~330bp market share, respectively, while TVSL and BJAUT lost ~15bp/315bp share respectively.
* For 1HFY27, however, RE, TVSL and HMCL gained 95bp/80bp/20bp of market share, respectively, while BJAUT lost 190bp. HMSI maintained its share as the second-largest player, falling ~170bp behind the market leader HMCL.
Valuation and view
* Auto volumes remained strong across segments in 2QFY27, supported by a favorable base in 2QFY26 and increased channel push ahead of the festive season. In the CV segment, sustained freight activity despite macroeconomic headwinds further supported robust double-digit growth during the quarter despite challenging macros. Overall, 1HFY27 witnessed strong demand momentum across the automotive industry. However, with the low base gradually normalizing across segments, headline growth rates are expected to moderate, warranting a more cautious outlook for the coming quarters.
* While OEMs and ancillaries have guided for continued pressure from commodities, the majority of the impact has already been reflected in 1Q results, and the price hikes taken by OEMs to offset this cost should cushion the blow during 2Q. As a result, we expect margins for the sector to revive gradually beyond 2Q. Remaining monitorable are the probable impact of El Niño expected in the current year and the escalation of the West Asia crisis again. In this scenario, OEMs with a healthy launch pipeline are likely to be preferred over others. Our top OEM picks are MSIL, TVSL, and MM. Among auto ancillaries, our top picks are HFL, MSWIL, SAMIL, SPR, and TENNIND.
For More Research Reports : Click Here
For More Motilal Oswal Securities Ltd Disclaimer
http://www.motilaloswal.com/MOSLdisclaimer/disclaimer.html
SEBI Registration number is INH000000412



Tag News
Auto Sector Update : Early Sense of Auto Retail Sales: October 2026 by Choice Institutional ...

More News
Real Estate Sector Update : Bengaluru RE pulse: Showcasing fundamental strength by Motilal ...