Auto Insights October 2026 by Choice Institutional Equities
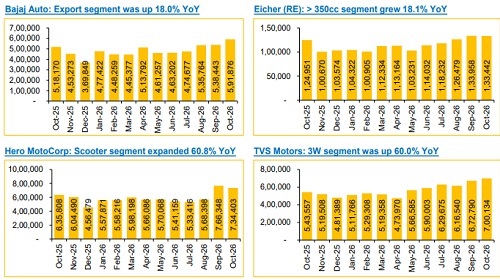
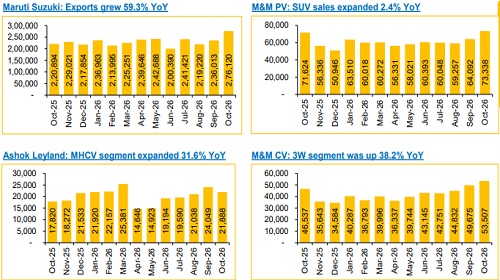
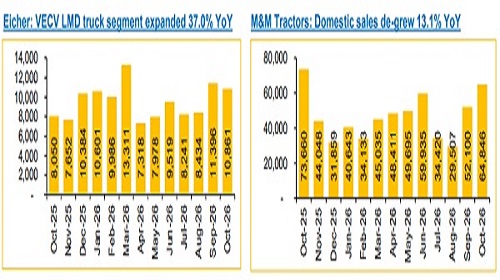
Auto OEM Dispatch - In Oct-2026, 2W sales showed healthy growth; TVSL sales grew 28.8% YoY and HMCL was up 15.5% YoY. The PV segment, driven by strong domestic demand from product launches, recorded healthy growth in domestic sales, with MSIL up 25.0% YoY. The CV segment saw solid growth, with AL, EIM-VECV and M&M sales up by 22.8% / 34.9% / 15.3% YoY, respectively.
Auto Retail Sales - The automotive industry posted a 23.8% YoY decline in retail sales in October 2026, primarily due to a high base created by last year’s GST-led festive demand surge, as purchases deferred ahead of GST 2.0 implementation were converted into registrations during October 2025. Rising vehicle prices and affordability pressures remain key monitorables for sustaining the recovery
CNG and EV Penetration - CNG penetration in PVs increased on a YoY basis amid a shift towards cleaner fuels. EV penetration across segments improved, though overall levels remained low, as adoption is constrained by infrastructure and range concerns.
Inventory Analysis - Dealer inventory levels showed mixed trends across major vehicle segments in October 2026. Overall inventory trended lower during the month, led by MSIL, BJAUT and HMCL
Auto OEM Dispatches
* In October 2026, 2W OEMs reported healthy volume growth, led by TVSL and HMCL, which recorded YoY growth of 28.8% and 15.5% YoY, respectively, supported by festive demand and strong domestic sales. BJAUT and EIM-RE reported growth of 14.2% and 6.8% YoY, respectively, reflecting steady demand across their portfolios.
* PV OEMs also delivered strong wholesale growth, supported by festive buying, improved affordability following GST rationalisation and new launches. MSIL and TTMT recorded YoY growth of 25.0% and 23.1%, respectively, driven by broad-based demand. M&M reported moderate growth of 2.4% YoY, while Hyundai Motor India posted growth of 17.7% YoY.
* The CV segment sustained strong momentum in October 2026, with AL, EIM-VECV, M&M and TTMT reporting growth of 22.8%, 34.9%, 15.3% and 27.0% YoY, respectively. Growth was supported by healthy demand across MHCV and LCV segments, freight activity and replacement demand. In contrast, tractor volumes remained subdued, with M&M and Escorts declining 12.0% and 10.0% YoY, respectively, reflecting a high base and uneven rainfall weighing on rural sentiment and farm-linked demand overall.
Auto Retail Sales:
Automobile Market Trend: Subdued YoY performance The automotive industry recorded a 23.8% YoY decline in retail sales in October 2026, reflecting a high base following the GST-led demand surge in October 2025 and a shift in festive purchases to November this year. Two-wheeler sales declined 28.4% YoY, while PV sales fell 14.5%, as the comparison was impacted by last year’s postGST pent-up demand and festive buying. In contrast, CV retail was flat, while 3W and tractor sales grew 4.0% and 3.6% YoY, respectively, indicating resilience in commercial mobility and farm-linked demand. The headline decline should therefore be interpreted cautiously, as the festive calendar and base effects distort the YoY comparison. Looking ahead, Q3FY27E demand should benefit from the ongoing festive and wedding season, continued GST-led affordability gains and new launches; however, elevated PV inventory, commodity-cost inflation and the need for sustained retail conversion remain key monitorables.
CNG and EV Adoption:
CNG penetration in 3Ws declined 704 bps YoY to 21.8%. PVs recorded a 170 bps YoY increase to 24.7%, indicating a growing preference for cleaner fuels in the segment. The CV segment recorded a decline in penetration of 40 bps YoY to 11.9%. On the EV front, 2W penetration grew 499 bps YoY to 9.7%, while PV penetration increased by 376 bps to 7.3%, and CV EV penetration grew by 267 bps to 4.3%, showing strong adoption of EV vehicles. The automotive industry is transitioning towards cleaner energy, especially in PVs, but EV uptake remains gradual amid concerns over charging infrastructure, range anxiety, battery life and performance.
Inventory Analysis: Assessing Dealer Inventory Level across Key Segments
For PVs, MSIL’s October 2026 dealer inventory was at lower levels below its one-year average (-1 days). However, M&M’s average inventory level was higher than MSIL’s. Its current dealer inventory stands at 21 days, lower than its oneyear average (24 days). In the 2W segment, inventory levels remained elevated during Dec 2024–Sep 2025 as subdued retail demand led dealers to accumulate stock. However, inventory levels normalised following GST 2.0 implementation, supported by a sharp recovery in retail demand and improved dealer offtake. In October 2026, inventory levels showed a mixed trend across OEMs. HMCL, BJAUT and EIM dealers continued to operate with lean inventory, reflecting disciplined dispatches and healthy retail absorption. In the CV segment, AL’s dealer inventory was at 25 days in October 2026. The company is currently operating at a lower inventory level (1-year average 32). We believe companies with low current inventory levels, such as MSIL, HMCL and BJAUT, are likely to report strong dispatch volumes over the next few months
For Detailed Report With Disclaimer Visit. https://choicebroking.in/disclaimer
SEBI Registration no.: INZ 000160131

.jpg)



More News
Oil and Gas Sector Update : Crude Compass: Supply Risks Outweigh Recovery Choice Institution...